

- The Core PCE index rose 3.0% YoY in August versus expectations of 3.3% YoY, which immediately weakened bond yields and the dollar.
- The Q2 US GDP revision boosted economic growth momentum from 1.5% to 2.2% annualized, driven by a 0.6% MoM real surge in consumer spending.
- Contracts on stock indices in New York open the session in green: the tech-heavy Nasdaq 100 (US100) is up 0.35%, and the broad S&P 500 (US500) gains 0.23%.
Wednesday trading on the last day of the month and quarter on Wall Street begins in a mood of moderate risk-on, triggered by a key package of macroeconomic data from the US economy. Published at 8:30 AM New York time, the BEA report brought long-awaited cooling to the Fed's preferred measure of inflation. Capital immediately flowed into equities that had been discounted in recent days, while Treasury yields and dollar quotes dropped to daily lows. Buyers' optimism is reinforced by the fact that the decline in price dynamics is accompanied by a still remarkably resilient consumer: Americans' real spending recorded its largest monthly jump in over a year. Investors' attention now shifts to the labor market (Friday's NFP report) and Micron Technology's financial results scheduled for tonight, which will serve as a litmus test for the valuations of AI-related companies.
Disinflationary Core PCE impulse and strong consumer take pressure off the Fed
The key event before the opening bell was the release of the August Personal Consumption Expenditures (PCE) index. Core PCE, excluding volatile food and energy prices, rose 0.2% month-on-month (below the 0.3% consensus) and 3.0% year-on-year, coming in significantly cooler than the projected 3.3% YoY. The headline PCE index grew at a rate of 0.3% MoM and 3.4% YoY. At the same time, the Bureau of Economic Analysis revised up the US Q2 GDP growth rate to 2.2% annualized from the preliminary estimate of 1.5%.
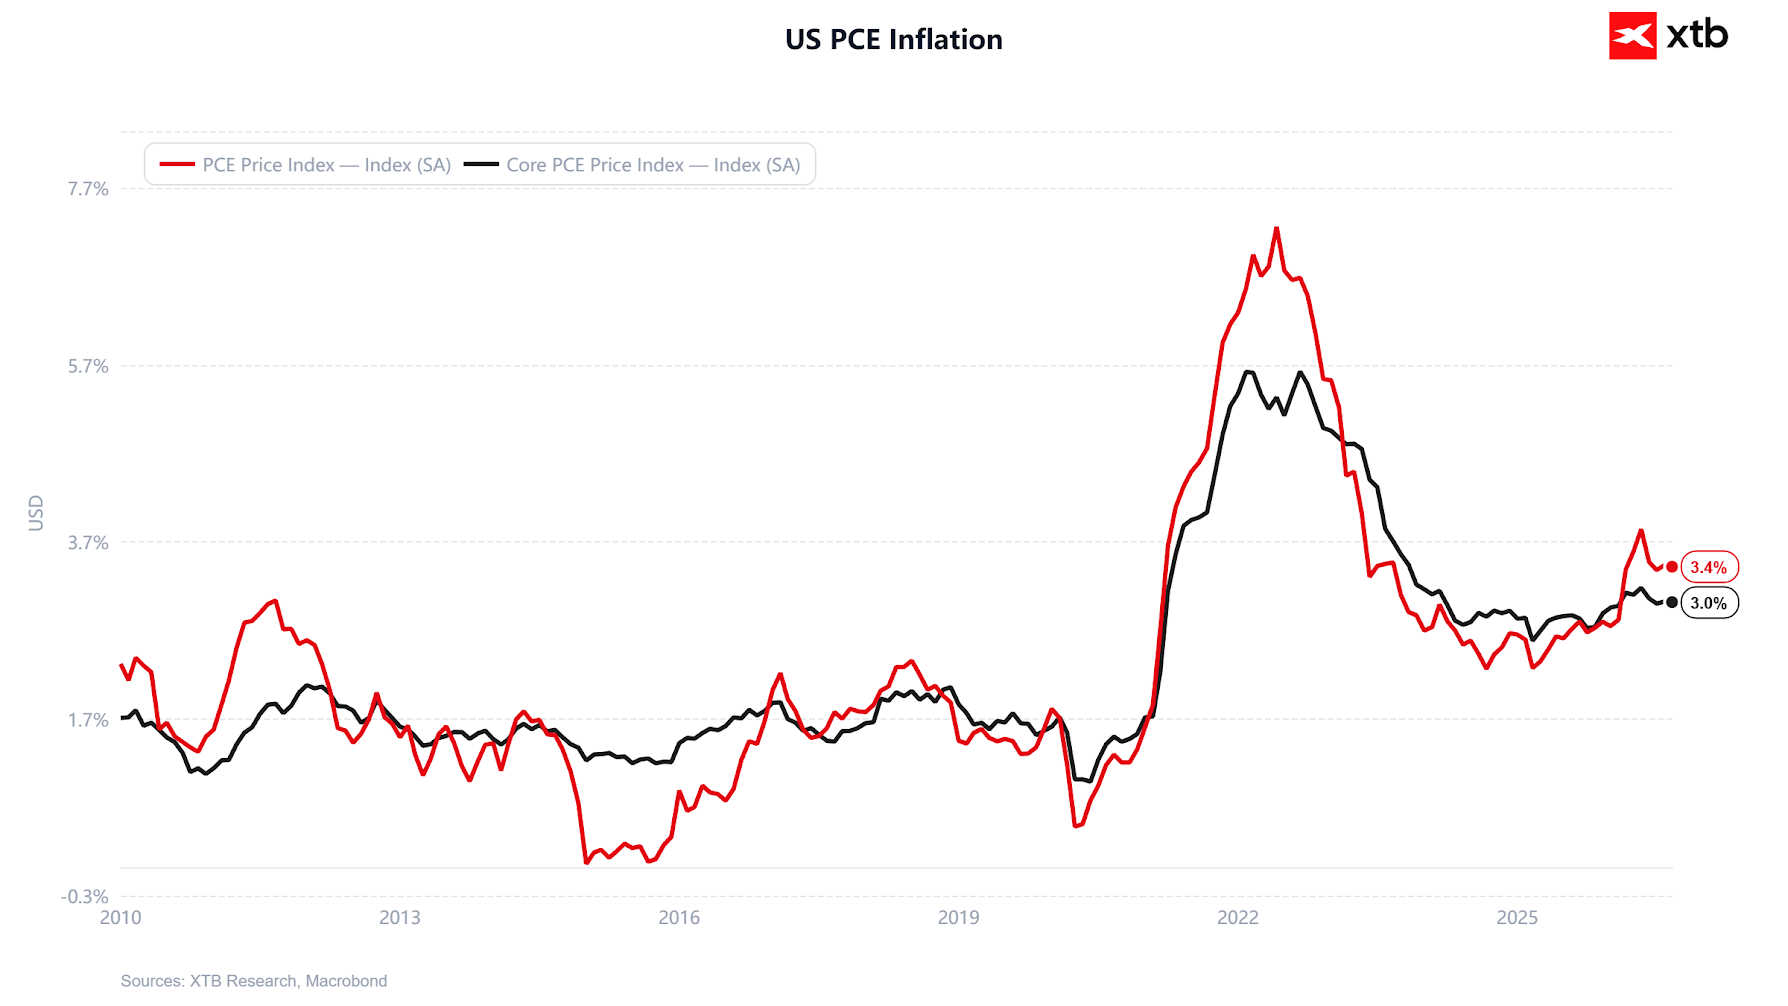
In response to these data, 10-year US Treasury yields pulled back sharply from multi-year highs, and the dollar index dropped to session lows today. The easing of cost pressures alongside a 0.9% MoM increase in consumer spending (0.6% MoM in real terms) supports the soft-landing scenario and reduces market fears of further aggressive interest rate hikes before the FOMC meeting scheduled for October 28.
Positioning at the session opening reflects a return of demand for risk assets:
- US500: 7755.4 pts (+0.23%, -0.64% weekly) – the broad market index responds with gains to the lower core inflation reading, defending key support zones after morning pressure on futures.
- US100: 30757.8 pts (+0.35%, -0.53% weekly) – the technology sector gains on falling Treasury yields and a rebound in the semiconductor segment.
- US30: 51741.0 pts (-0.01%, -0.83% weekly) – the traditional industrial index consolidates near yesterday's close under pressure from some commodity and defense stocks.
- US2000: 2839.3 pts (+0.28%, -0.71% weekly) – small caps benefit from relief in the debt market, dynamically trimming weekly losses.
US500 Technical Analysis
On the US500 daily chart (D1), a broad uptrend structure is visible, initiated by a dynamic upward move from the March 2026 low at 6368 pts (100.0% Fibonacci retracement). Currently, price action trades around 7760 pts, remaining above key moving averages: the fast 25-period SMA at 7707.2 pts and the slower 50-period SMA at 7680.8 pts.
The situation on the daily chart indicates that after reaching a local peak near 7853.6 pts, the market entered a slight correction phase, which successfully tested a broad horizontal demand zone in the 7500–7595.7 pts range (reinforced by the 23.6% Fibo retracement at 7503.1 pts). Recent daily candles show base formation above 7719.2 pts support and a strong defense of the 25 SMA.
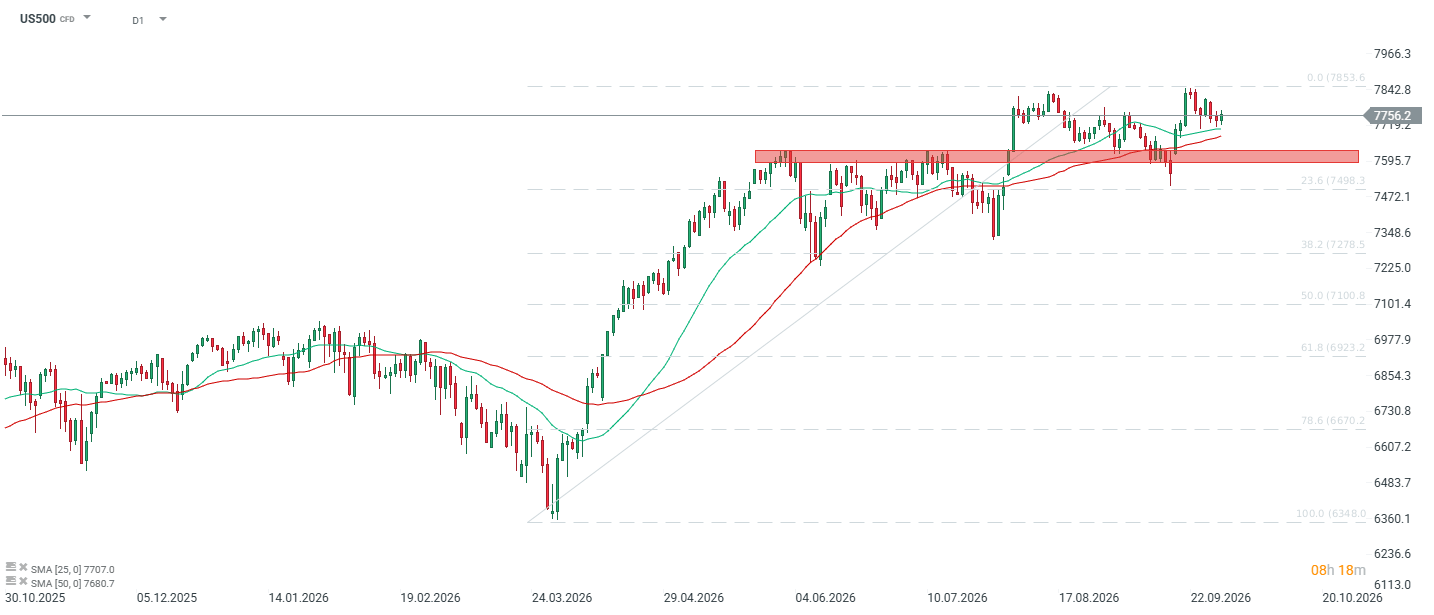
Bullish scenario: Holding above 7719 pts and the 25 SMA (7707 pts) opens the way for bulls to test local highs again at 7842.8–7853.6 pts. A breakout above this resistance will confirm impulse continuation towards the psychological barrier of 8000 pts.
Bearish scenario: A break below the 25 and 50 SMAs (D1 candle close below 7680 pts) will invalidate the short-term bullish signal and drag prices back to the key support zone around 7595.7–7503.1 pts (23.6% Fibonacci retracement).
Top Corporate News
- Defense tenders and government contracts drive polarization: Boeing (BA.US) gains 2.0% after winning a prestigious US Navy contract to produce next-generation fighters for the Top Gun program, beating an industry rival. As a result, shares of the losing contender, Northrop Grumman (NOC.US), fall 4.3% at the open.
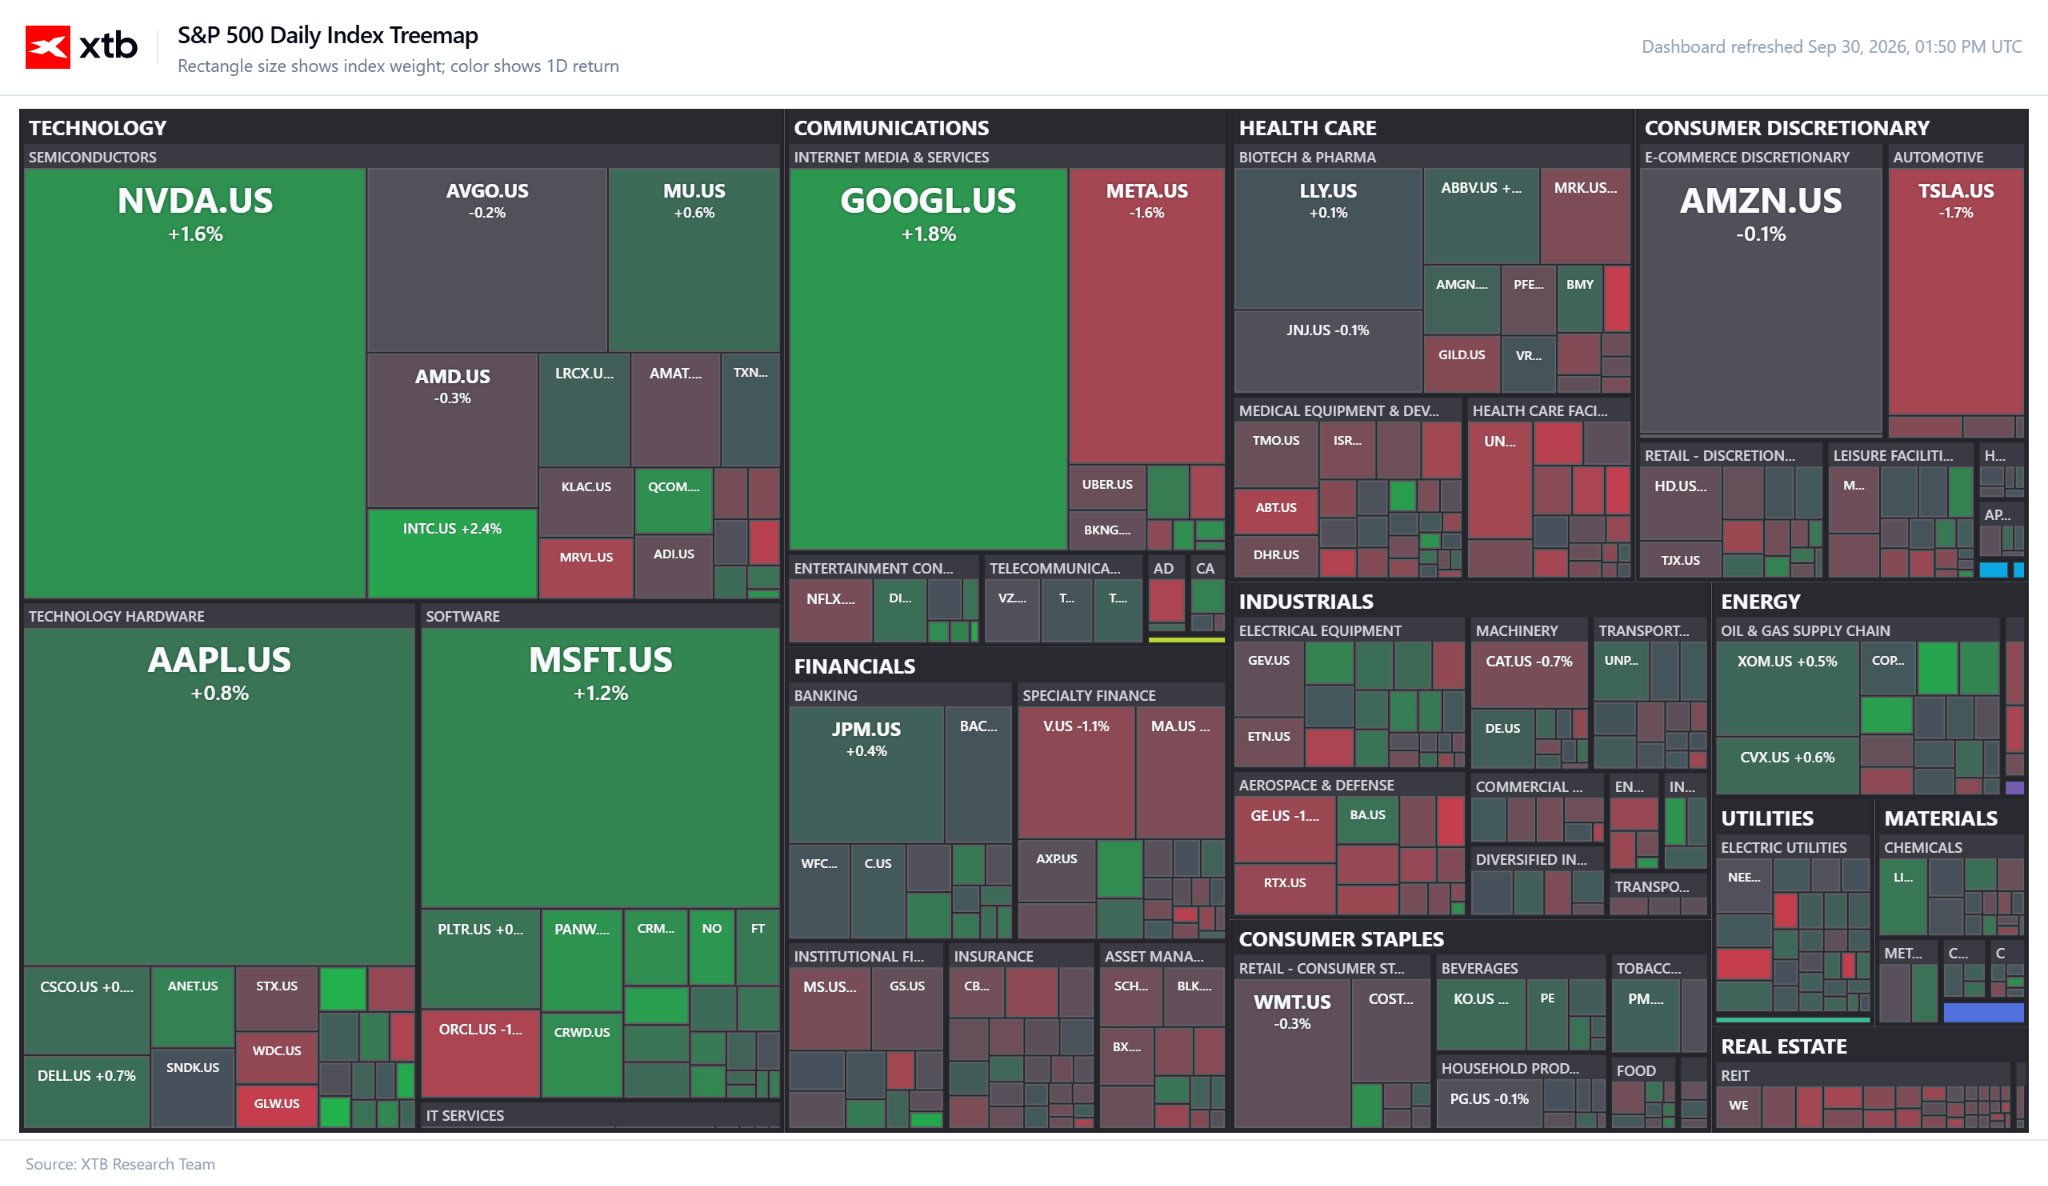
- Big Tech and cloud infrastructure influenced by AI releases: Tech stocks experience selective revival following the Core PCE print.
- Alphabet (GOOGL.US) advances 1.90% to $346.02 (RSI 47.41, P/E 17.07, Wall Street average target price $433.94),
- Microsoft (MSFT.US) rises 1.20% to $515.78 (consensus 4.83/5, target $561.39),
- Apple (AAPL.US) increases 0.8% to $332.67.
- AI leader, Nvidia (NVDA.US), gains 1.43% to $230.41 (P/E 28.44, consensus buy rating with a target of $301.86), boosted partly by news that CoreWeave will offer "Vera CPU" chips dedicated to autonomous AI agents.
- Meanwhile, Amazon (AMZN.US) inches up 0.14% to $246.95 (P/E 19.66, target recommendation $314.42), supported by a multi-year deal with Synopsys worth over $1 billion for proprietary silicon IP solutions for AWS cloud.
- On the flip side, Meta Platforms (META.US) drops 1.93% to $724.60, and struggling Tesla (TSLA.US) declines 1.75% to $346.70 (-21.5% YTD, RSI at 44.87).
- Advanced Micro Devices (AMD.US) opens 0.48% higher at $610.03 (the company comes off a massive +183.5% YTD rally with a high P/E of 154.11 and a target of $498.29).
- Strong momentum is visible across the hardware supply chain – Applied Materials (AMAT.US) climbs 5.19% to $511.87, and Lumentum Holdings (LITE.US) surges 5.60% to $969.98, while Wall Street's focus centres on Micron Technology's quarterly results due after the bell.
- A severe drop is recorded by Fair Isaac (FICO.US), whose shares plummet 26.99% to $612.00.
- The decline also drags down Equifax (EFX.US) (-3.41% to $140.63).
- Meanwhile, FactSet Research Systems (FDS.US), despite initial pre-market losses due to a weaker-than-expected long-term EPS forecast for 2027, rebounds during regular trading by 0.78% to $260.86.
- Moderna (MRNA.US) falls 6.0% following a downgrade by Citigroup analysts to "sell", who assessed that the optimism surrounding oncology drugs is already fully priced in on the chart.
- On the opposite side, Vanda Pharmaceuticals (VNDA.US) rises 4.0% after announcing that Hetlioz met its primary endpoint in Phase III trials for circadian rhythm disorders.
- Additionally, Achieve Life Sciences (ACHV.US) advances 3.0% as Stifel initiated coverage with a "buy" rating, pointing to potential market success for its smoking cessation drug candidate.
- Weakness affects retailer Lululemon Athletica (LULU.US), which drops 3.62% to $96.86.
- Broker Robinhood Markets (HOOD.US) gains 2.0% following the rollout of AI agent tools assisting with investment strategies and the launch of perpetual futures contracts on select cryptocurrencies.
- Meme favorite GameStop (GME.US) rises 1.0% after an SEC filing revealed that Chairman and CEO Ryan Cohen purchased $10.6 million worth of additional company shares.
Retail Pulse
- Retail investor communities on forums like WallStreetBets and r/StockMarket welcomed the morning macro readings with relief.
- Threads regarding the decline of annual Core PCE to 3.0% quickly dominated discussions, with users interpreting the lower reading as a clear signal of easing hawkish pressure at the Federal Reserve.
- The second hottest topic of the day remains the upcoming quarterly results from Micron Technology (MU) – forums show a clear split between aggressive call option positioning and fears of profit-taking amid high expectations for the semiconductor sector.
- Retail traders' attention was again drawn by Ryan Cohen, whose $10.6 million GameStop share purchase renewed speculation of returning "meme momentum", though the stock price upside (+1%) remains subdued compared to multi-million institutional capital flows.
- At the same time, lively debate continues on forums regarding portfolio diversification beyond the Big Tech bubble, fueled by reports of record hedge fund participation in the Treasury market (exceeding $30 trillion) and the fact that only one of the ten largest US companies currently offers a yield higher than long-term 30-year debt.
Calendar
Key upcoming releases and events:
- Today after the close (September 30): Financial report of Micron Technology (MU.US) for Q4 fiscal year (a key test of valuation in the semiconductor industry).
- Friday (October 3): US labor market report for September (Non-Farm Payrolls, unemployment rate, wage growth).
- October 28: Federal Open Market Committee (FOMC) interest rate decision.


US PCE lower than expected, GDP beats expectations🗽Wall Street reacts


Micron Preview: A Record Quarter Is No Longer Enough
Micron earnings due after the bell today. Will the AI stock rally get fresh fuel?

Economic Calendar: Wall Street Awaits PCE Data and Micron Earnings (30.08.2026)