

- US index futures post modest gains, as investors await the FOMC decision and the release of the latest macroeconomic projections and dot plot.
- Strong US retail sales data: August sales unexpectedly rose 1.2% MoM (versus expected +0.8% MoM), rebounding after July's decline.
- Semiconductor sector supports Nasdaq: Intel (INTC.US) gains in pre-market trading and early session following reports of talks with SK Hynix regarding initial memory production in the US.
- Slump in JB Hunt shares (JBHT.US): The transport company falls more than 12% after issuing a profit warning and citing rising operating costs.

- US index futures post modest gains, as investors await the FOMC decision and the release of the latest macroeconomic projections and dot plot.
- Strong US retail sales data: August sales unexpectedly rose 1.2% MoM (versus expected +0.8% MoM), rebounding after July's decline.
- Semiconductor sector supports Nasdaq: Intel (INTC.US) gains in pre-market trading and early session following reports of talks with SK Hynix regarding initial memory production in the US.
- Slump in JB Hunt shares (JBHT.US): The transport company falls more than 12% after issuing a profit warning and citing rising operating costs.
Market Situation and Indices
August CPI readings and stronger-than-expected retail sales data (+1.2% MoM) sparked market discussion around Federal Reserve action. The market is pricing in an over 90% probability of a 25 bps rate hike at today's meeting. Close attention will be paid to the conference message and the updated dot plot, which will determine whether a hawkish stance will persist in upcoming quarters. Moderation in crude oil price increases and stabilization in the Treasury market offer mild relief.
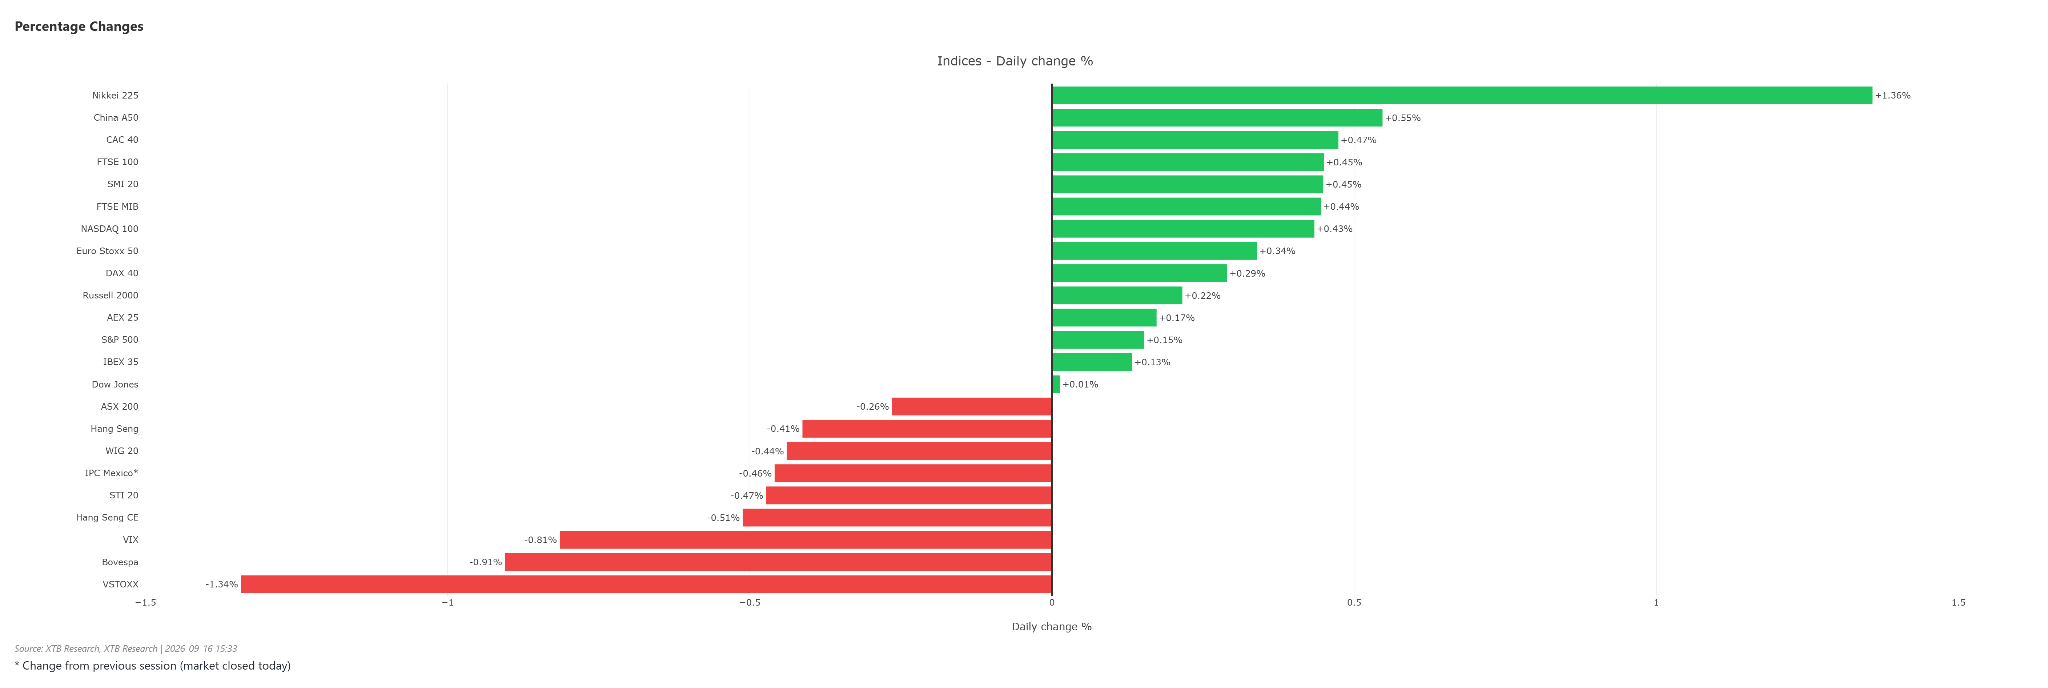
On the cash market and futures contracts, we observe attempts to defend following recent declines:
- US500 (S&P 500 futures): The contract gains approx. +0.2% - +0.3%, trying to form a local bottom around 7606 pts.
- US100 (Nasdaq 100 futures): Gains +0.4% - +0.5%, making up for weakness from previous sessions thanks to relative strength among tech leaders and semiconductors.
- US30 (Dow Jones futures): Loses modestly at 0.2%, remaining influenced by mixed reports from the industrial and transport sectors.
- US2000 (Russell 2000 futures): Rebounds +0.4%, though small-cap stocks remain highly sensitive to elevated bond yields.
Technical Analysis US500 (D1)
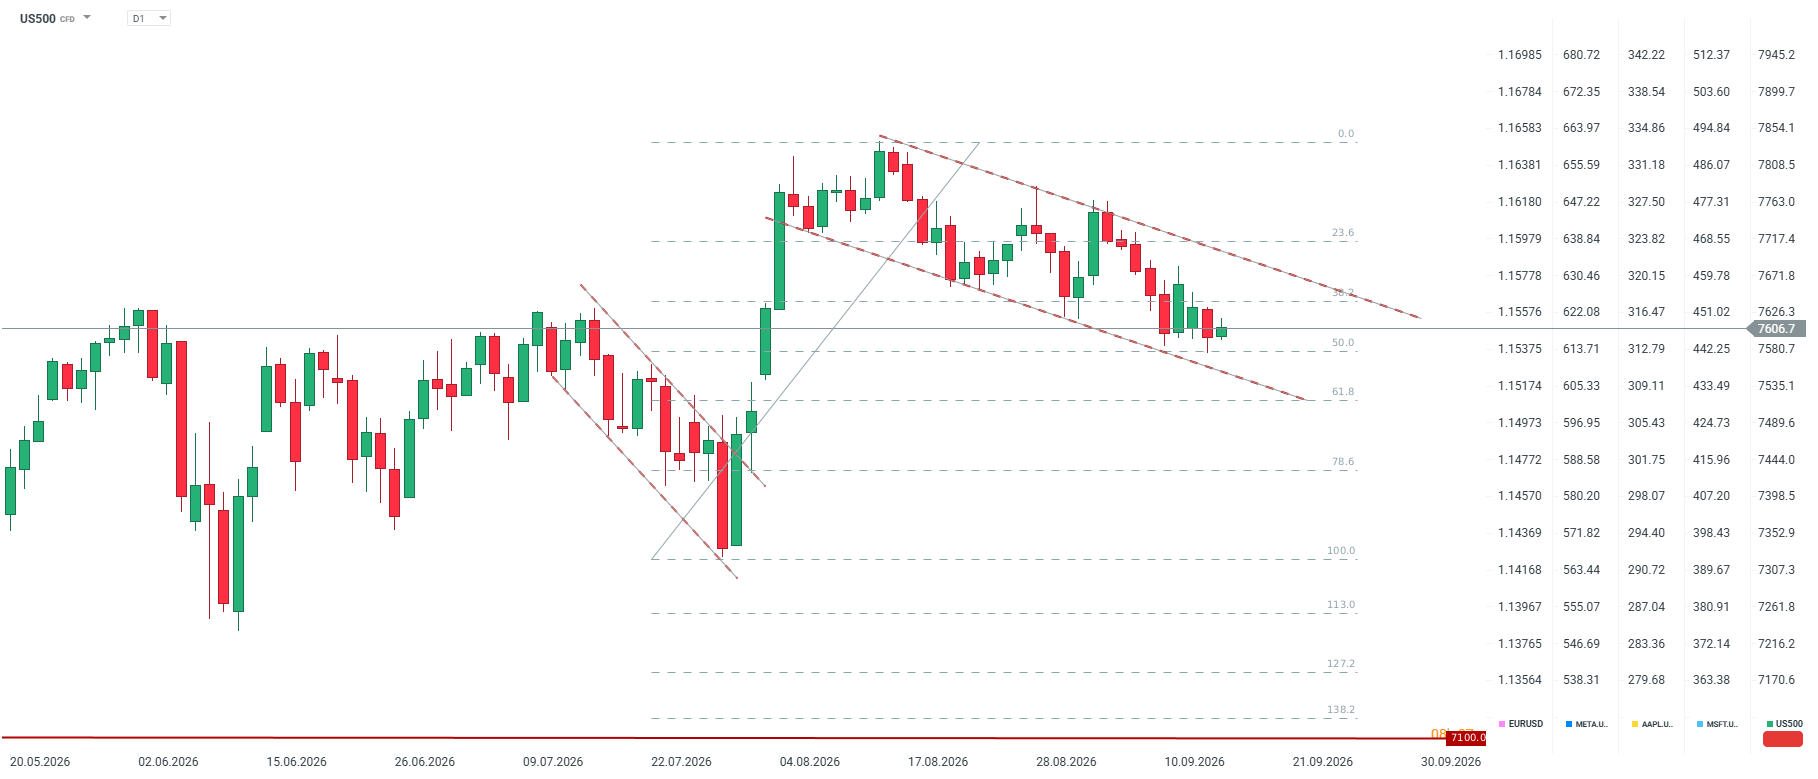
From the peak at 7854 pts in mid-August, the index has been moving in a clear downward channel. The ongoing correction is orderly, characterized by small candle bodies, strong overlap of price ranges, and an absence of capitulation sessions. This technical picture indicates a correction within a trend rather than a sharp market collapse.
Applying Fibonacci retracements to the upward impulse from the July low (~7353 pts) to the August peak (7854 pts) places the current price in a key decision zone. The 38.2% retracement level at 7626 pts was lost, and the market is currently testing support at 50.0% (7581 pts). Extended lower wicks on candles over the last four sessions confirm demand activity in this region.
Key Levels:
- Resistance (~7700 / 7717): Upper boundary of the downward channel + 23.6% Fibo retracement
- Resistance (7763): Local price reaction zone
- Resistance (7808 / 7854): August all-time highs
- Support (7581): 50.0% Fibo retracement (currently tested)
- Support (7535): 61.8% Fibo retracement + lower boundary of the downward channel
- Support (7444 → 7353): 78.6% Fibo retracement and July low
Scenarios:
A daily candle breakout above ~7700 pts negates the downward structure and opens the path toward testing 7763–7854 pts again. Conversely, a session close below 7535 pts will break both the 61.8% retracement and the channel's lower boundary (the only strong technical confluence on this chart), triggering a fall toward 7444 pts, with a potential full retracement to 7353 pts. The extension levels at 113.0% (7262 pts) and 127.2% (7171 pts) represent a stagflationary scenario rather than a purely technical one.
In the 7535–7700 pts range, neither side holds a lasting advantage (~95 points upside and ~70 points downside potential), qualifying this zone as a wait-and-see area.
Important caveat: all the above technical setups could be invalidated immediately following the FOMC announcement (8:00 PM CET). With a hike priced in at 92%, the tone of the dot plot and the press conference led by Kevin Warsh will prove crucial for determining the direction out of the 7535–7700 pts range.
Key Company Updates
-
Intel (INTC.US) (+4.4%): Gains following press reports regarding advanced talks with SK Hynix concerning US-based memory chip manufacturing.
- JB Hunt Transport Services (JBHT.US) (-12.3%): Sharp sell-off following management warnings regarding rising operating costs and weaker earnings outlook at a Morgan Stanley conference.
- Alvotech (ALVO.US) (+8.5%): Shares rise following a double upgrade by Barclays to "overweight" ahead of an upcoming FDA decision.
- Rocket Pharmaceuticals (RCKT.US) (+1.1%): Moves higher following a rating upgrade by Needham to "buy" (from "hold") due to progress in discussions with the FDA regarding rare disease trial designs.
- SimilarWeb (SMWB.US) (+0.71%): Upgraded to "buy" by Needham following a series of meetings with company management.
- Bloom Energy (BE.US) (+5.3%): Gains fit into strong demand for AI energy infrastructure companies.
- Expedia (EXPE.US) (-1.7%): Declines following a downgrade by Morgan Stanley to "underweight" with a $235 price target.
- Ardagh Metal Packaging (AMBP.US) (-1.4%): Drops following a court ruling in Luxembourg blocking asset sales in its metal packaging division. However, the company managed to significantly trim initial losses.
- Magnificent Seven Companies: Trading modestly higher overall: Nvidia (+0.8%), Meta Platforms (+1.5%), Alphabet (-0.1%), Tesla (+0.8%), Amazon (-0.3%), Apple (+1.2%), while Microsoft (-0.45%) posts slight losses.
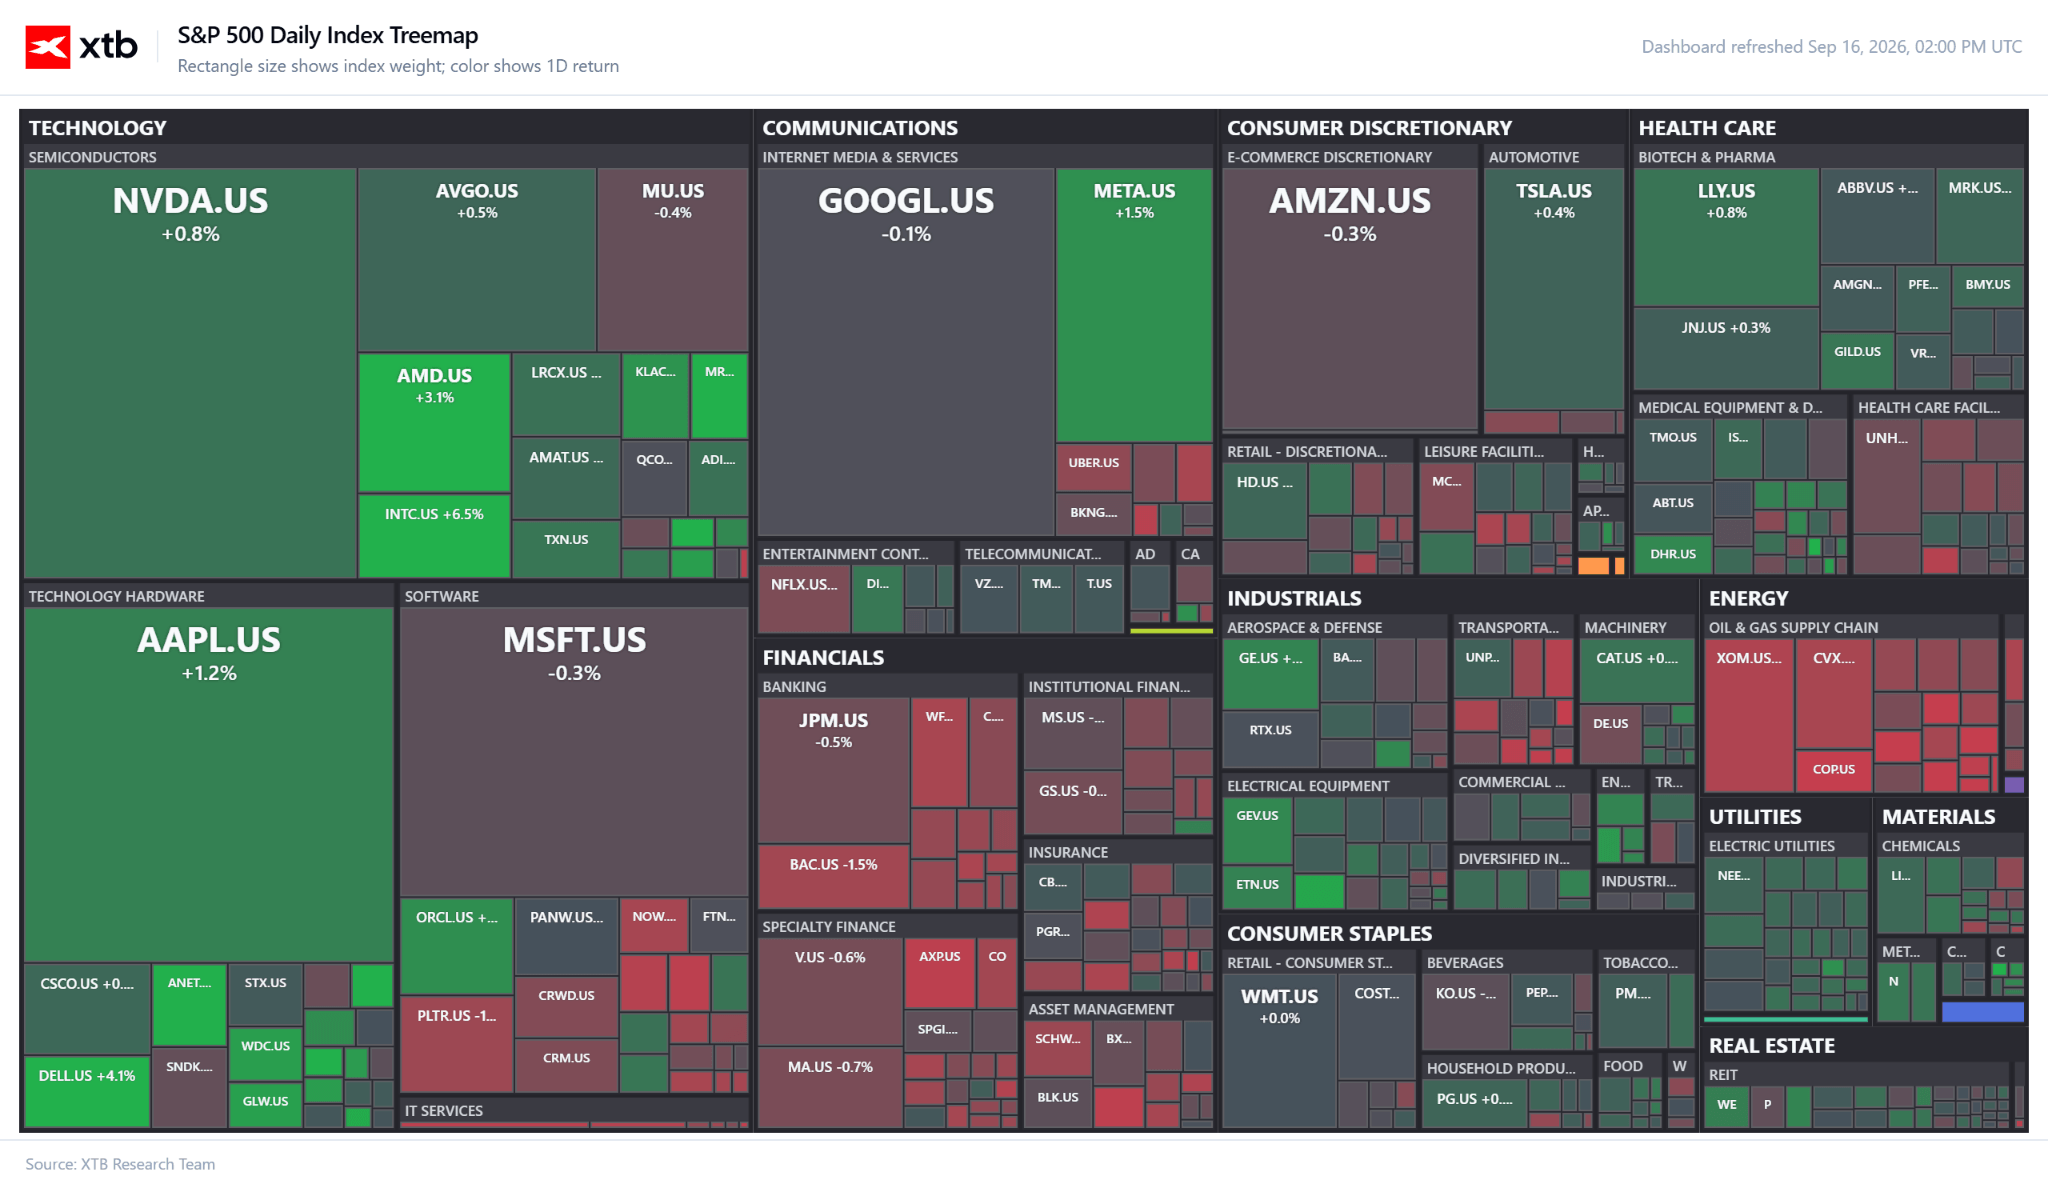



Chart of the Day: What’s next for the US stock market? (16.09.2026)



Morning Wrap: Market seeks balance ahead of Fed decision (16.09.2026)

Morning Wrap: Brent at $107, AI sell-off (15.09.2026)

Daily summary: AI slowdown does not slow the rise in yields