


US index futures are moving higher, with the S&P 500 (US500) once again testing record highs and gaining around 0.3%, broadly in line with Nasdaq 100 futures, while the largest technology stocks are also strengthening.
- US ADP Employment Change: 23.75k vs 20k in the previous week
- US Trade Balance: -$105.6 billion vs -$102.05 billion expected and -$88.6 billion previously
Labor market data are slightly positive, as weekly ADP employment growth accelerated, although the scale of improvement remains moderate. At the same time, the significantly wider-than-expected trade deficit, which increased to more than $105 billion, may point to stronger import demand but could also act as a short-term drag on US GDP growth.
Market sentiment is also being supported today by lower oil prices and a rebound in bonds. Brent has slipped toward $98 per barrel, partially easing inflation concerns, while US Treasuries are recovering after the 10-year yield reached its highest level since 2002 on Monday. The US dollar remains relatively stable. Positive sentiment is also visible in Europe, with the Stoxx 600 up around 0.7% and French and Italian bonds rebounding after the recent sell-off. The euro is also attempting to recover after falling to a 17-month low.
Risk appetite is additionally supported by strong corporate earnings and the continued wave of investment in artificial intelligence. OpenAI is reportedly in talks with UAE investors over a potential $30 billion financing round, while DeepSeek and Moonshot AI are also said to be raising fresh capital. Alphabet, meanwhile, has signed a nuclear energy agreement with Constellation Energy. French bonds remain stable despite ongoing political tensions, while the spread over German Bunds continues to narrow, although markets remain focused on the country’s fiscal outlook and high debt burden.
S&P 500 earnings gain momentum
Estimated Q3 2026 earnings growth for S&P 500 companies now stands at 29.5% y/y, up from 26.7% expected at the end of June. If confirmed, this would mark the third consecutive quarter with earnings growth above 25%.
- Guidance remains strong: 72 companies have issued positive EPS guidance, compared with 44 issuing negative guidance.
- Early reports are solid: among the 16 companies that have already reported, 14 beat EPS expectations and 12 exceeded revenue estimates.
- Valuation remains moderate: the S&P 500 forward 12-month P/E ratio stands at 19, below the 5-year average of 19.8 and the 10-year average of 19.1.
Looking at the US500 futures chart, the contract is setting fresh all-time highs today and is gradually approaching the 7,900-point level.
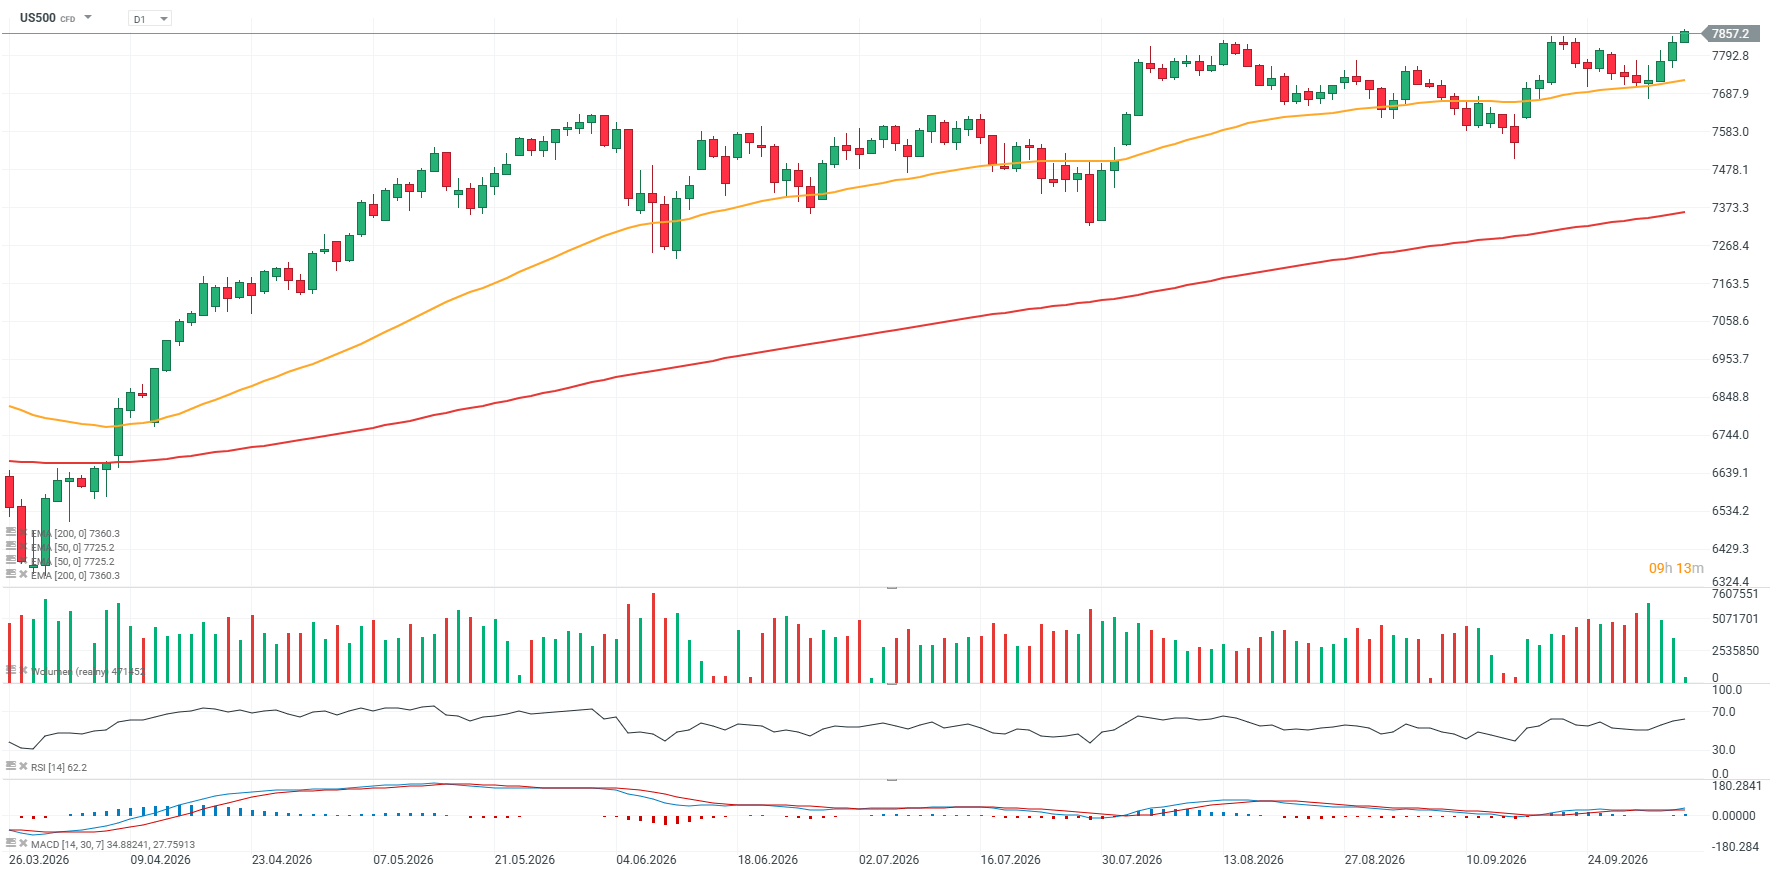 Source: xStation5


US Open: Wall Street Pushes Back Expectations of Another Fed Hike

Marvell: Memory-market problems and opportunities
Morning Wrap: Stock Indices Rise as Bonds Extend Their Losing Streak (06.10.2026)


Daily Summary: Yields at their highest since 2002, yet Wall Street is still rising🚨