


The Q2 2026 earnings season is now almost complete and, so far, the picture remains very solid. Nearly all S&P 500 companies have reported, while the scale of positive surprises remains high for both earnings and revenues. At the same time, earnings growth has clearly exceeded expectations from before the start of the season, while the balance of guidance for the next quarter suggests that companies remain relatively optimistic about the near-term outlook.
- In Q2, as many as 86% of S&P 500 companies reported EPS above analysts’ expectations, while 77% delivered a positive revenue surprise.
- The blended earnings growth rate for the index currently stands at 52.0% YoY. If this figure holds through the end of the reporting season, it would mark the strongest earnings growth since Q2 2021, when growth reached 91.6%.
- The improvement versus earlier expectations is especially notable. As recently as June 30, analysts expected Q2 earnings growth of 23.1% YoY, less than half of the growth rate currently being reported.
- Analysts expect S&P 500 earnings to rise by 28.2% YoY in Q3 and by 25.8% in Q4 2026, while full-year 2026 earnings growth is projected at 31.2% YoY. Both Q3 and the holiday-heavy Q4 appear to have meaningful room to surprise current analyst expectations.
- In 10 of the 11 S&P 500 sectors, current earnings are stronger than expected at the end of June. This reflects both positive EPS surprises and upward revisions to analyst estimates.
- The outlook for Q3 also remains relatively constructive. So far, 63 companies have issued positive EPS guidance, while 35 have provided guidance below previous market expectations.
- Despite strong earnings, the index still trades at a somewhat elevated valuation by historical standards. The S&P 500 forward 12-month P/E ratio stands at 19.6x, slightly below its 5-year average of 19.9x but above the 10-year average of 19.0x.
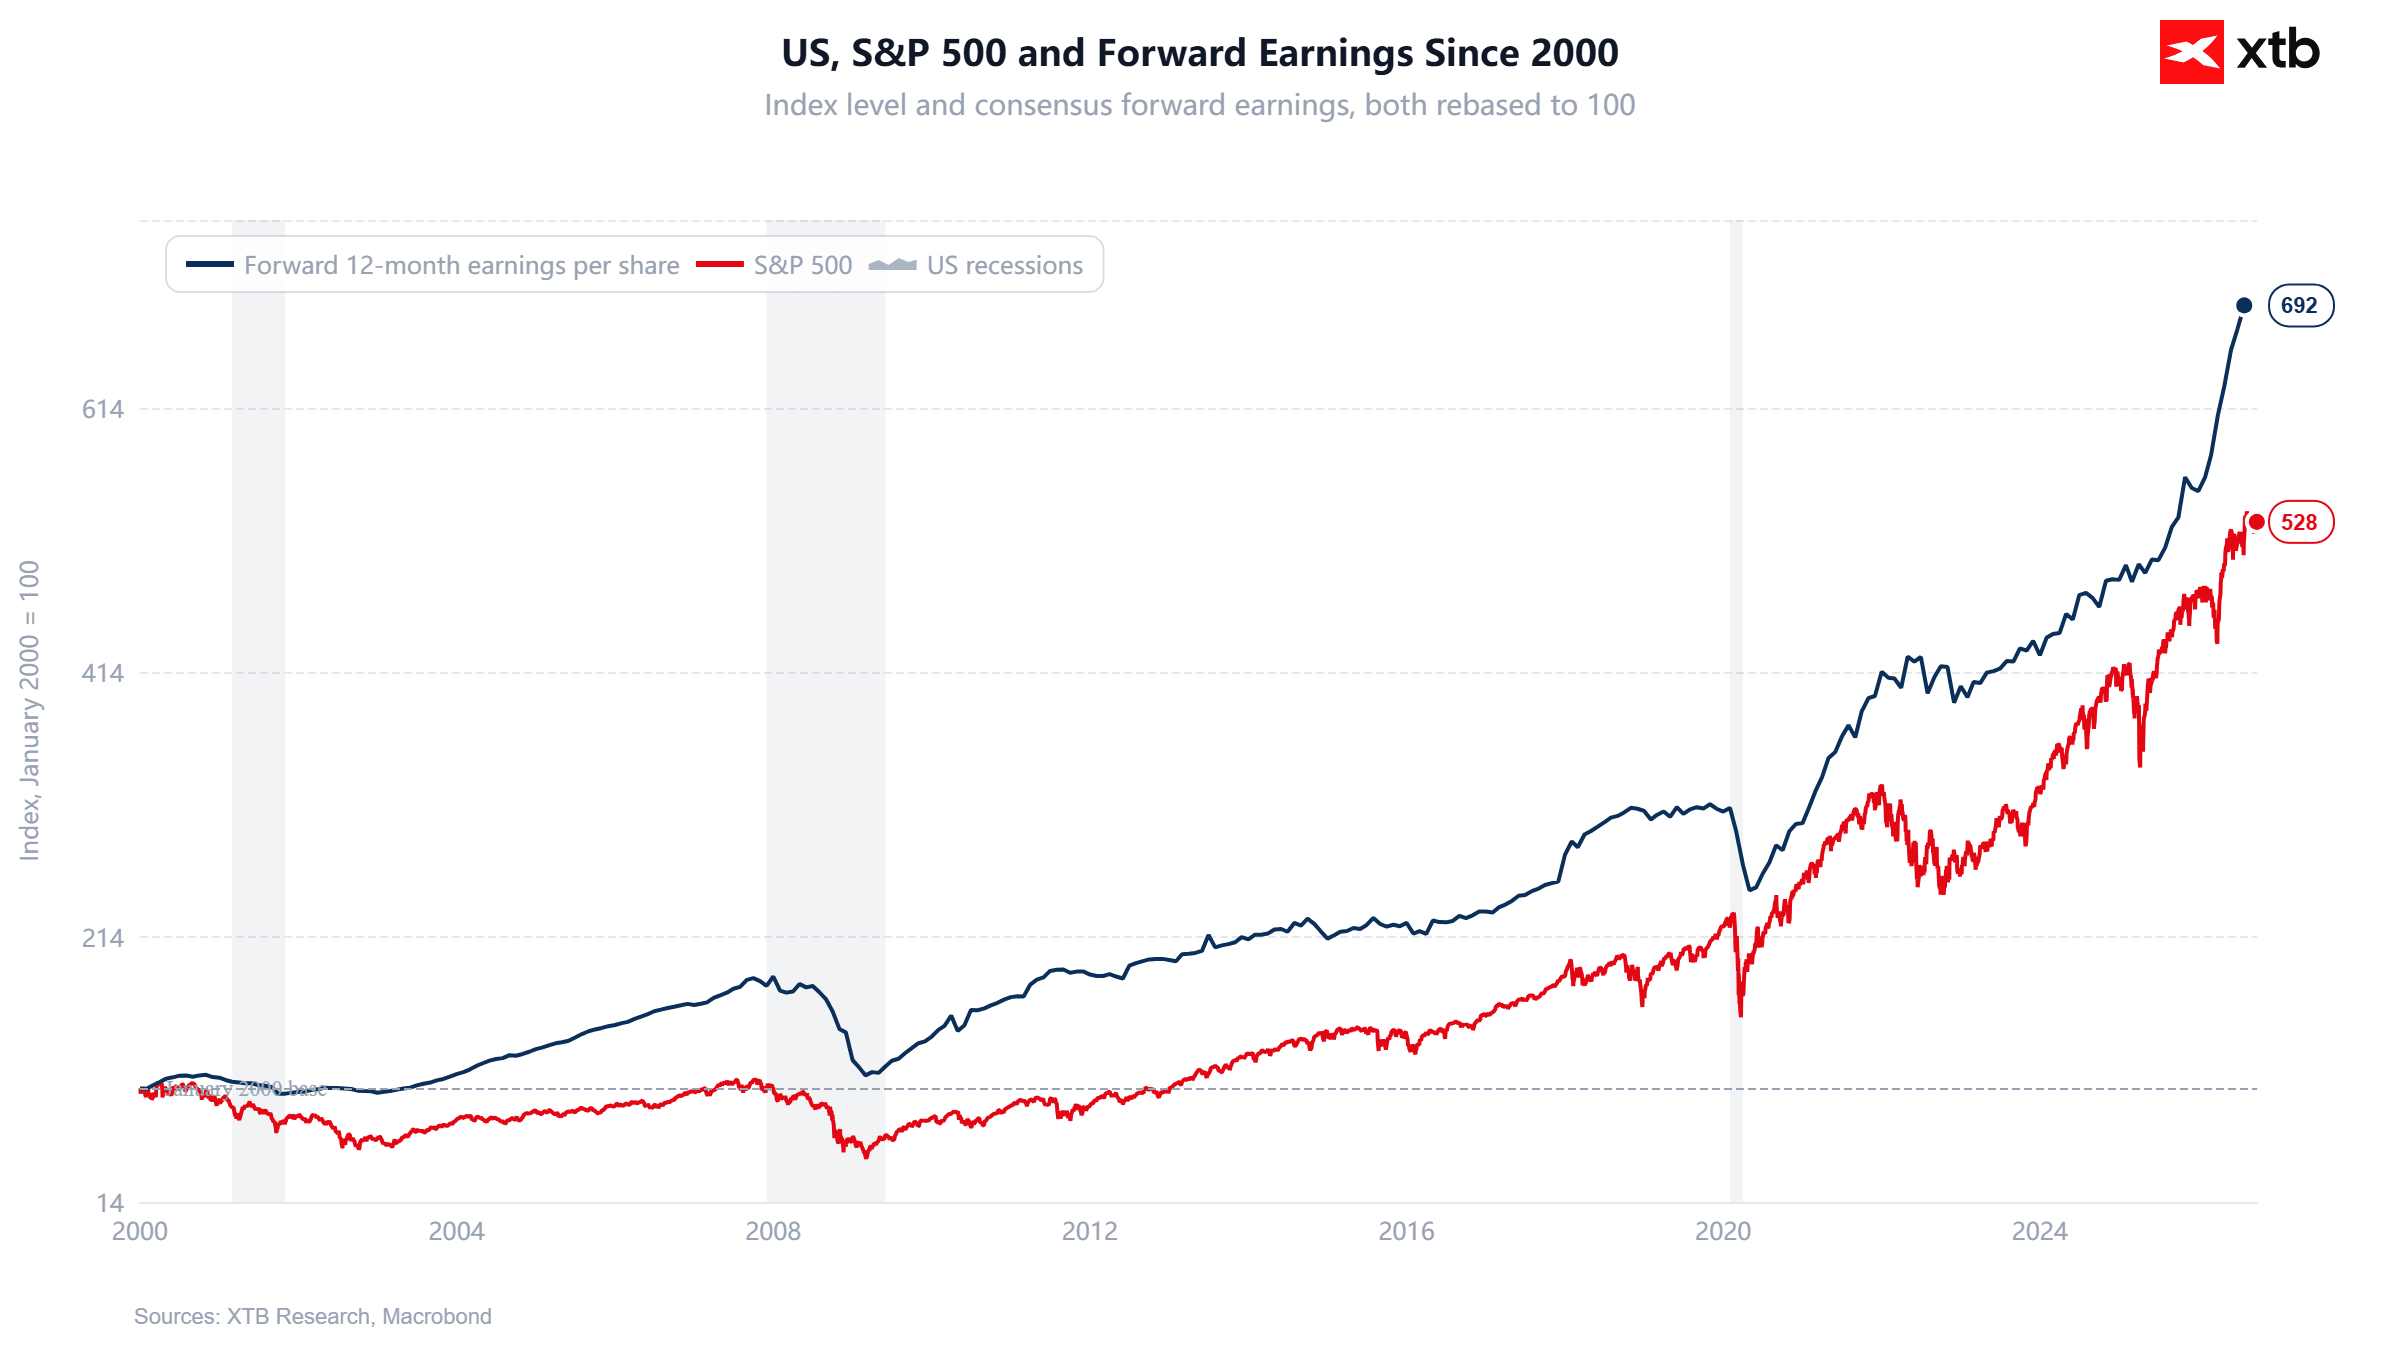
Since the beginning of 2000, the rise in the S&P 500 has been supported to a large extent by improving earnings expectations, although the two series have diverged more visibly in recent years. The forward 12-month EPS index has now risen to around 692 points, assuming a base of 100 in 2000, while the S&P 500 itself is near 528 points, suggesting that the market’s long-term advance still has substantial support from earnings fundamentals. At the same time, history shows that forward earnings estimates can fall sharply during recessions, meaning that current EPS strength provides an important valuation buffer but does not eliminate the risk of a correction if economic conditions deteriorate materially. However, with no clear signs of a downturn in the US economy and the services sector remaining particularly resilient, the current valuation of the S&P 500 does not appear especially demanding and may still offer a degree of “margin of safety.”
 Source: XTB Research
The Scale of Positive Earnings Surprises Is Exceptionally High
Aggregate S&P 500 earnings for Q2 are currently 26.5% above analysts’ prior expectations. This is well above the average surprise seen over the past year (+9.2%), five years (+7.0%), and ten years (+7.4%), and it also exceeds the previous record of 23.2% set in Q2 2020.
However, it is important to note that the overall result has been significantly boosted by unusually large investment gains at Alphabet and Amazon. Excluding those two companies, the earnings surprise for the S&P 500 falls to 10.8%, which is still solid but much closer to historical norms.
Magnificent 7 Earnings Continue to Impress
All Magnificent 7 companies have now reported their Q2 2026 results. At first glance, the numbers look exceptionally strong, with aggregate earnings growth for the group reaching 118.5% YoY, well above prior expectations. However, a substantial part of that growth was driven by one-off investment gains at Alphabet and Amazon, so the underlying picture looks more moderate once those two companies are excluded.
- As of June 30, analysts expected Magnificent 7 earnings to rise by 30.8% YoY in Q2. The actual increase reached 118.5%, the strongest growth rate for the group since at least Q4 2020.
- Six of the seven companies, or 86%, reported EPS above expectations. This was the same percentage as for the S&P 500 overall, although the scale of the positive surprises was much larger.
- Aggregate Magnificent 7 earnings exceeded analyst estimates by 66.2%, compared with a positive earnings surprise of 26.5% for the S&P 500 as a whole.
- For the remaining 493 companies in the S&P 500, earnings growth reached 31.8% YoY. This was also a very strong result and the highest growth rate for that group since Q4 2021.
- The five largest contributors to S&P 500 earnings growth were Alphabet, Amazon, Micron Technology, NVIDIA, and Chevron. Three of the top five therefore came from the Magnificent 7.
- The key caveat concerns Alphabet and Amazon. In both cases, FactSet uses GAAP EPS, which in Q2 was significantly boosted by higher other income related to investment gains.
- Alphabet reported around $98 billion in other income, mainly due to net unrealized gains on equity securities. Amazon, meanwhile, reported around $53.4 billion in similar income, driven primarily by its investment in Anthropic.
- Excluding Alphabet and Amazon, Magnificent 7 earnings growth falls from 118.5% to 43.2%, while the positive earnings surprise declines from 66.2% to just 4.4%. This means the earnings season for the Magnificent 7 remains strong, but the headline growth rate above 100% clearly overstates the improvement in Big Tech’s underlying operating performance.
US500 Chart (D1 Interval)
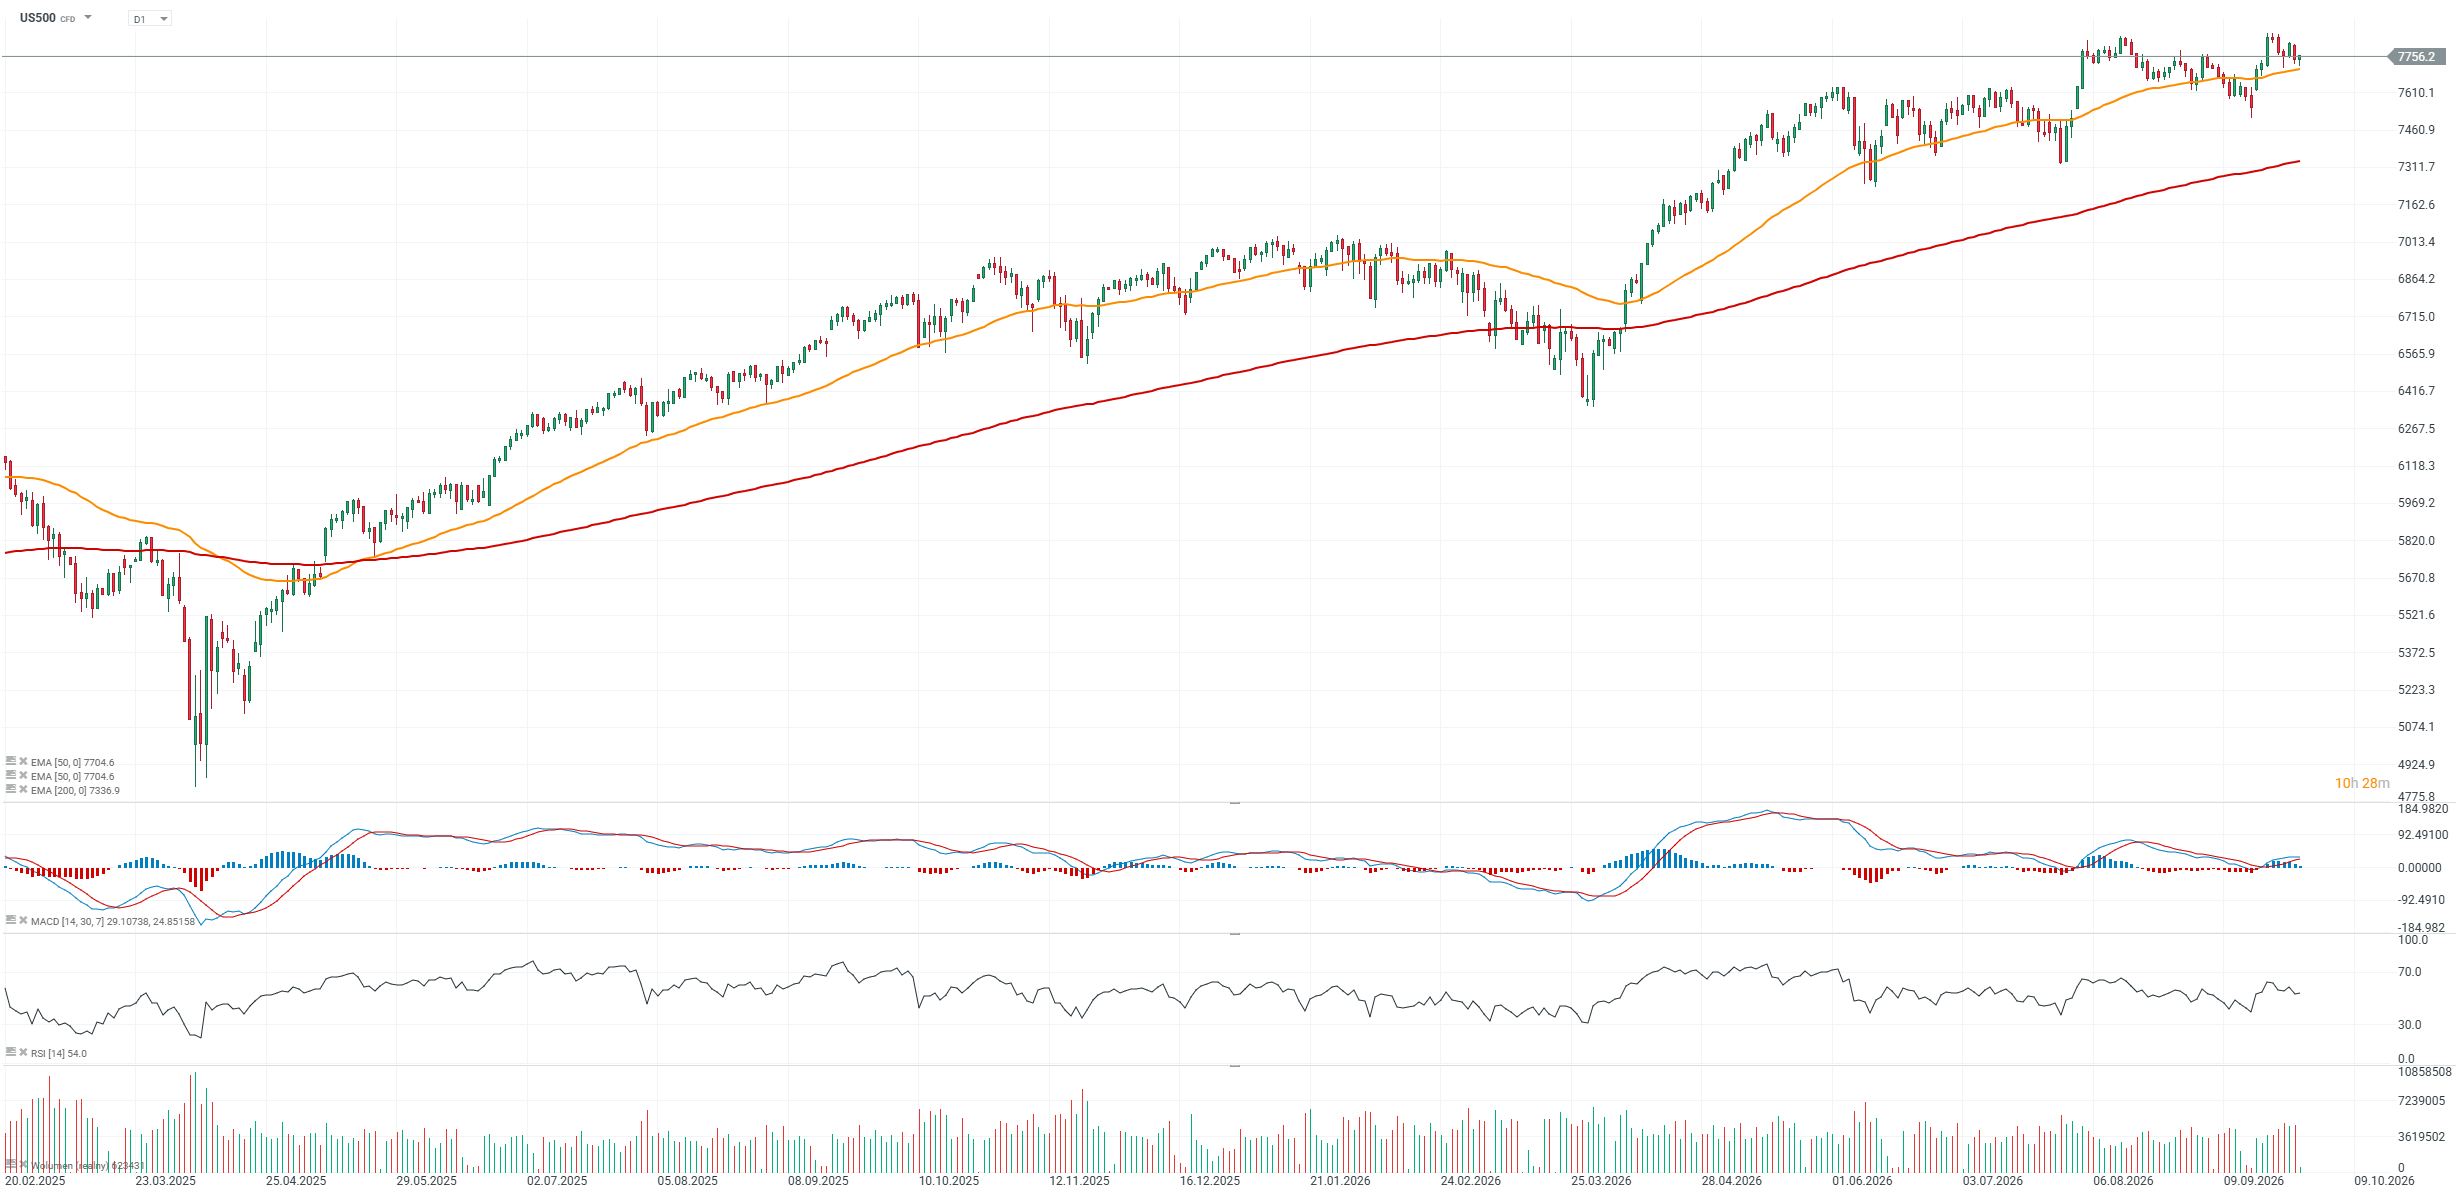
US500 remains in a well-established uptrend, with prices still trading clearly above the rising EMA 50 and EMA 200, technically confirming the continued dominance of buyers. At the same time, momentum does not appear overheated: RSI remains close to neutral levels, while MACD points to only a moderate bullish advantage, suggesting consolidation near the highs rather than an euphoric phase of the move. From a macro perspective, the key question is whether incoming inflation, labour-market and bond-yield data will allow current valuation multiples to be sustained and, with another potentially solid earnings season ahead, whether they will leave room for further multiple expansion.
 Source: xStation5.


AMD Goes Shopping: Is Its $8.2 Billion Investment a Good Move?



Morning Briefing: Higher Rates in Australia and Further Rise in Oil Prices


Daily Summary: Lack of progress in negotiations weighs on Wall Street and precious metals (28.09.2026)


US Open: Wall Street starts the week in red (28.09.2026)