


The market is increasingly pricing in the risk of more persistent disruptions to wheat supply from the Black Sea region, which currently appears to create a bullish setup for Chicago-listed wheat futures (WHEAT). Grain flows from the Black Sea have remained constrained since July, while further incidents along key shipping routes are increasing the risk of another decline in export availability. Recent attacks on vessels near Bulgaria and Romania show that the problem may extend beyond Russian and Ukrainian ports to routes through the Danube and waters belonging to EU member states.
Turkey remains one of the key participants in efforts to stabilize regional trade, but according to CRM AgriCommodities, reaching an effective agreement could take months. With no clear signs of de-escalation in the Russia-Ukraine war, the market may therefore continue to price an elevated geopolitical risk premium into wheat. Only a lasting improvement in shipping security and a meaningful recovery in export flows would likely reduce that premium.
Key wheat market developments
- Since July, wheat supply from the Black Sea region has remained severely constrained, while according to IFX, Russian wheat exports fell 75% y/y in September to 1.36 million tonnes.
- US winter wheat planting progress stands at 36%, compared with the five-year average of 46% and analyst expectations of 43%, according to Crop Progress data.
- Kansas, the largest US winter wheat-producing state, is particularly far behind schedule, with around 24% of acreage planted versus a 40% average for this time of year.
- Russia has announced an intensification of attacks on Ukrainian territory, while on Tuesday, October 7, two merchant vessels, including one carrying grain, were hit by drones off the coast of Bulgaria, following an earlier attack on a vessel near Romania.
- Forecasts point to limited rainfall across much of the Corn Belt in the near term, while NOAA expects wetter conditions across the eastern United States further out, together with above-normal temperatures in parts of the Midwest and Great Plains.
Weather and demand support wheat prices despite weaker US exports
Another factor supporting prices is the delay in US winter wheat planting. Weather remains a mixed factor, but in the short term limited rainfall may increase concerns about insufficient soil moisture for newly planted crops, particularly across the Great Plains. Wetter conditions forecast by NOAA further out could partially ease this risk, although their impact will depend on whether the rainfall reaches the most important wheat-producing regions. US winter wheat planting is clearly lagging its typical pace. Crop development is also slower, with emergence at 16% versus a five-year average of 20%, while heavy rainfall over recent weeks, especially across the southern Great Plains, has been the main cause of planting delays by limiting field access for farm machinery.
Despite a temporary shift toward drier weather, conditions are still not fully comfortable. A tropical storm may develop in the Gulf of Mexico next week, while another system could move across the northern Great Plains, potentially bringing another round of heavy rain and local flooding. At the same time, drought conditions remain in parts of key growing regions despite recent rainfall, meaning additional moisture will still be needed before winter. This setup continues to support a degree of weather premium in wheat prices, particularly if rainfall increases again next week.
The main factor limiting upside potential remains the weaker pace of US exports. Wheat export inspections totaled 11.1 million bushels in the week ending October 1, down 10% from the previous week, while cumulative shipments remain well below year-ago levels. However, this may not be enough to reverse the current upward pressure if supply from the Black Sea region continues to be constrained.
At the same time, there are early signs of improving demand. A large Saudi purchase suggests that some importers are returning to the market after the recent decline in wheat prices, while a somewhat weaker US dollar improves the competitiveness of US grain in international markets. Overall, the current balance of factors looks moderately bullish for wheat prices: supply and geopolitical risks currently outweigh weaker US exports, although the durability of the move will depend on developments in the Black Sea region, weather conditions and Friday’s USDA WASDE report, scheduled for 18:00 Polish time.
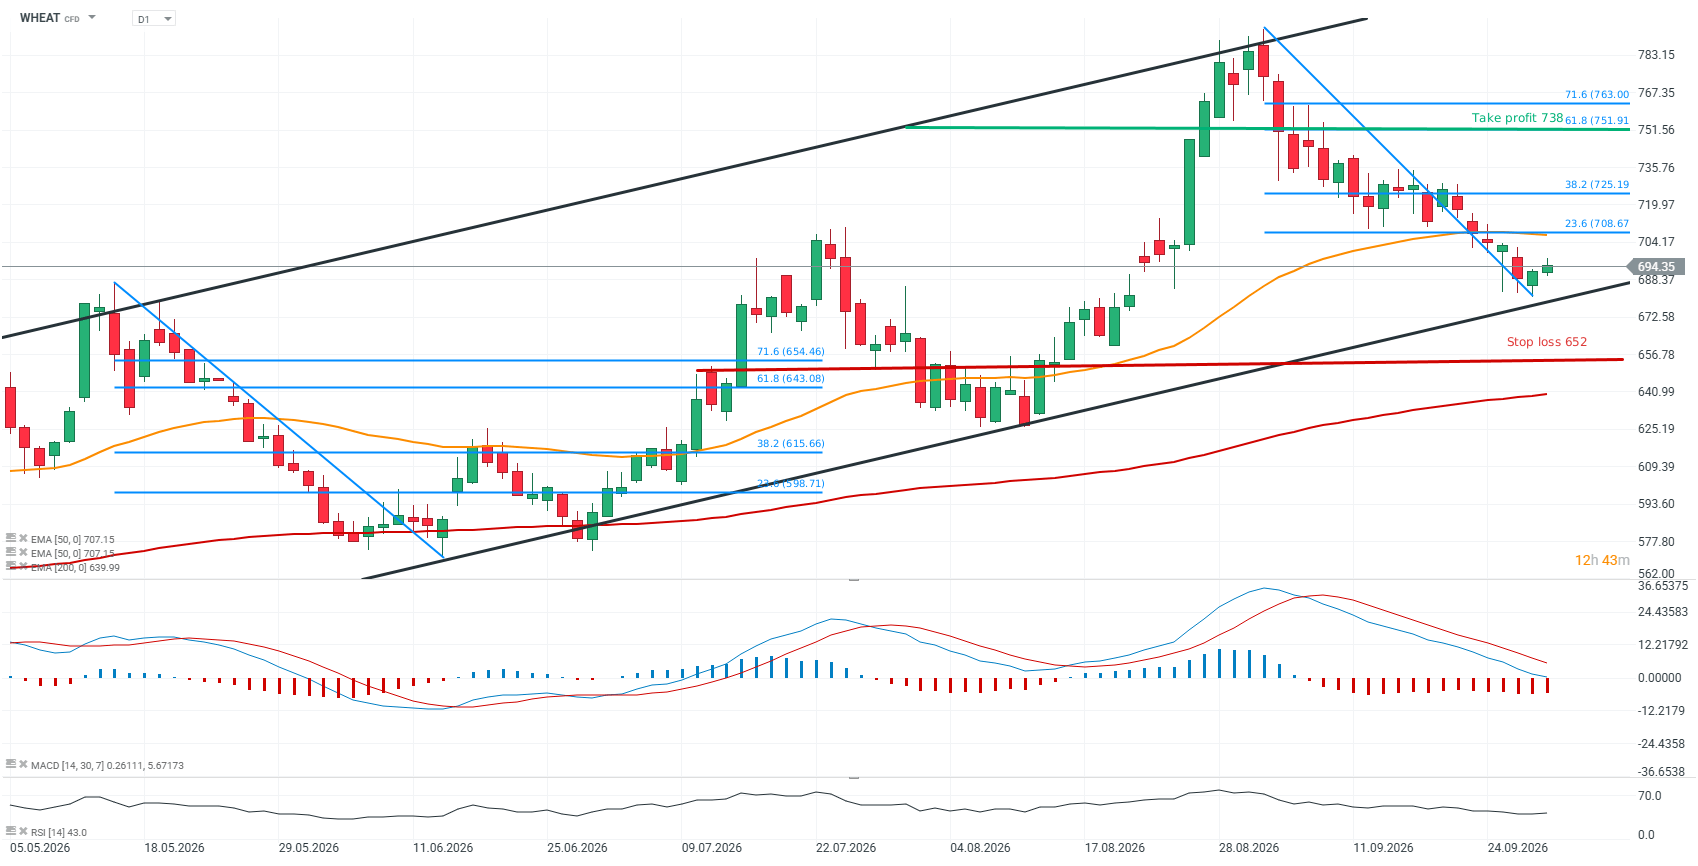 Source: xStation5


Large decline in crude inventories 🛢️📉

📉 Gold loses 1.7%


US Open: Wall Street in the Red 🚩 Nasdaq Falls 1% From Record Highs, Constellation Brands Back at March 2020 Level

Bitcoin Hits a Wall. Will “Uptober” Bring a Crypto Correction?