


Canada CPI NSA (M/M) Dec: -0.2% (est -0.3%; prev 0.1%)
- CPI (Y/Y): 2.4% (est 2.2%; prev 2.2%)
- CPI Core - Median (Y/Y): 2.5% (est 2.7%; prev 2.8%)
- CPI Core - Trim (Y/Y): 2.7% (est 2.7%; prev 2.8%)
Canada's December CPI surprised to the upside at 2.4% year-over-year, exceeding expectations of 2.2%, driven primarily by soaring food costs and resilient restaurant prices signaling persistent service-sector inflation despite cooling goods categories. Core inflation metrics showed improvement, with both CPI median and trim edging down to 2.5% and 2.7% respectively, suggesting underlying price pressures are moderating—a positive signal for the Bank of Canada's disinflation narrative. The surprise headline beat, combined with month-over-month deflation of -0.2%, masks a troubling bifurcation: while tradable goods face deflationary pressure, non-tradable services and food remain sticky, with grocery prices up 5.0% year-over-year and frozen beef surging 17.7%.
For the Bank of Canada, this report reinforces a mixed outlook that complicates rate-cut decisions; headline inflation remains above the 2% target, and robust restaurant price growth evidences strong consumer demand, arguing against aggressive easing. The technical benefit from GST/HST changes falling out of the year-over-year calculation masks underlying stickiness in shelter and food, keeping medium-term inflation risks alive and likely pushing BoC toward a more cautious stance than market pricing had anticipated. This should support the Canadian dollar near-term, as expectations of sustained elevated rates relative to other central banks become more plausible; markets may recalibrate rate-cut odds downward, underpinning CAD through reduced rate differential compression with the USD.
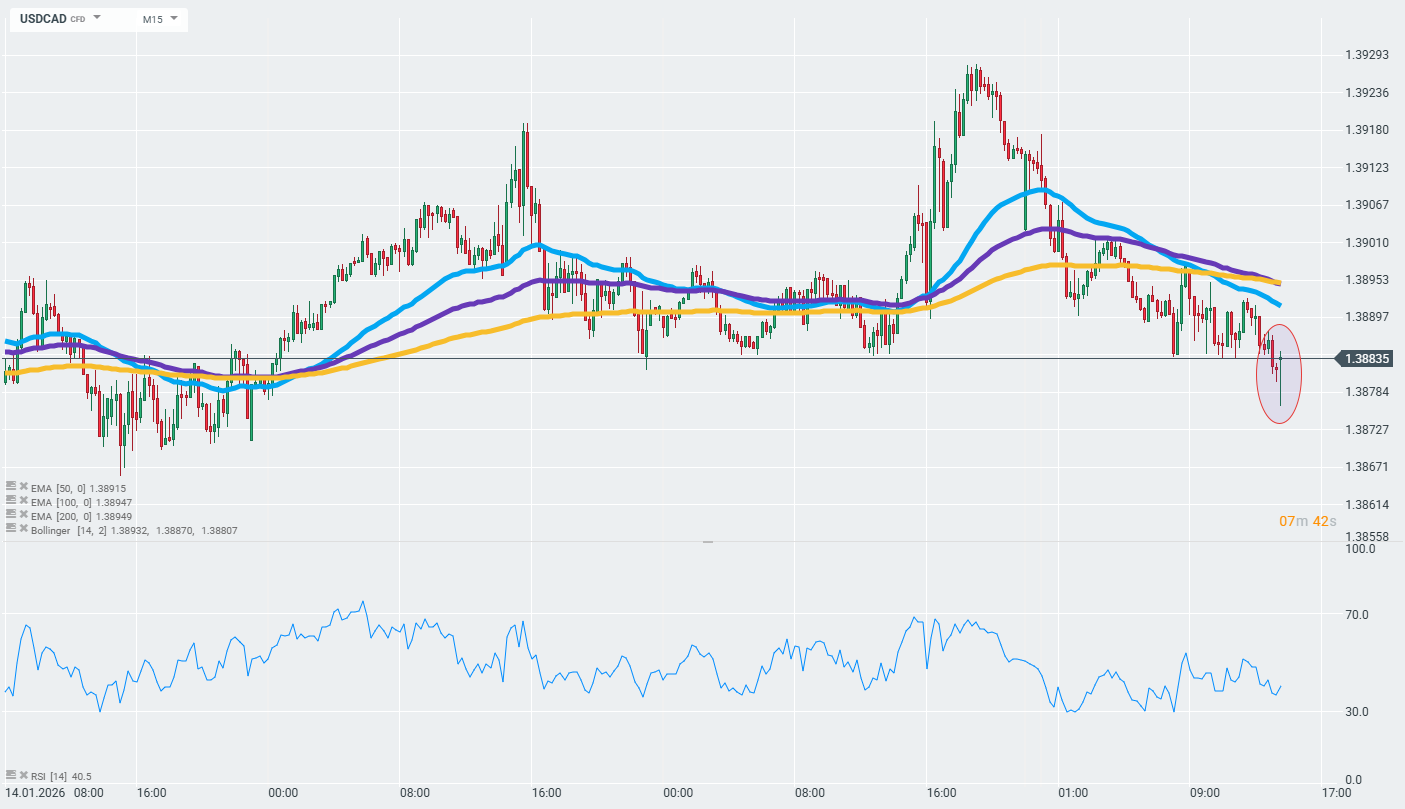
The USDCAD pair holds the intraday downowrd trend after the publication.


Three markets to watch next week (23.10.2026)
BREAKING: France slows down, Germany holds on. Euro falls below 1.12
Chart of the Day: Is USDJPY running out of road? Inflation forces the BoJ to act, but the Fed could spoil the Yen’s rally


Macro Calendar: Preliminary PMI Readings and Earnings Ahead