


The main factor driving today’s volatility in financial markets is a sharp rebound in the tech sector following last week’s sell-off, which was driven by concerns about the profitability of investments in artificial intelligence. Investors decided to buy the dip ahead of a key week of earnings reports from giants such as SpaceX, Tesla, and Meta Platforms. Sentiment is also being bolstered by calm in the bond market and recent remarks by Federal Reserve Chair Kevin Warsh, which suggest there is no rush to raise interest rates further. Although the market is now taking a more selective approach to companies taking on debt to develop new technologies, optimism surrounding the upcoming quarterly reports is effectively stabilizing sentiment on Wall Street.
On the geopolitical front, market attention is focused on the massive and violent protests in France, which prompted Prime Minister Sébastien Lecornu to call on local authorities to impose a partial curfew. These riots are fueling concerns about the French government’s ability to reduce its high budget deficit and are boosting Marine Le Pen’s chances in next year’s presidential election. At the same time, investors are anxiously monitoring the escalation of tensions in the Middle East, including attacks on ships in the Persian Gulf, as well as Sunday’s Ukrainian strike on a Russian oil terminal in St. Petersburg. Another political development in the West is today’s non-binding referendum in the oil-rich province of Alberta on its possible secession from Canada.
On the macroeconomic front, data from China stood out positively, with gross domestic product in the third quarter rising by 4.5 percent year-over-year, rebounding from three-year lows. Meanwhile, in Canada, September’s consumer price index came in at 3.1 percent, slightly below economists’ expectations, easing pressure on the country’s central bank to raise interest rates next week. In Japan, Central Bank Governor Kazuo Ueda assessed that core inflation is already very close to the 2 percent target due to a tight labor market and strong global demand related to artificial intelligence. Meanwhile, futures prices in the United States indicate that rates will remain unchanged at the end of October, but they assign a 92 percent probability of a rate hike in December.
In the stock index market, we are seeing a clear divide between the rising markets of the U.S. and Asia and the falling European market, which is weighed down by the political and fiscal crisis in France. The US100 technology index futures contract is up more than one percent, reaching around 29,740 points, while the broad US500 index is up just under half a percent to 7,739 points. The Japanese JP225 index had an excellent session, rising by nearly 1.7 percent, while semiconductor indices broke the longest streak of eight consecutive sessions of declines since 2008. In Europe, however, declines exceeding one percent are dominating the German DE40, the British UK100, the Italian ITA40, and the French CAC40, with the Polish W20 following suit, losing nearly nine-tenths of a percent and falling to 4,236 points.
Among individual companies, the top gainers are chip and memory manufacturers such as Marvell, SanDisk, Micron, Intel, and AMD—which are up between 3 and 7 percent—as well as Amazon, which is up 5 percent and has been named the top pick by Morgan Stanley analysts. Shares of steelmaker Cleveland Cliffs soared 16 percent following the release of quarterly results that significantly exceeded consensus estimates, while CoreWeave and Datadog shares are rising after Goldman Sachs and Bernstein upgraded their recommendations. Investors are also buzzing with speculation about a potential acquisition of Tesla by SpaceX ahead of the December shareholders’ meeting, as well as the announcement of Apple’s October launch of new computers, including its first touchscreen laptop. On the other hand, pressure is evident in the financial and real estate sectors, where Ameriprise Financial shares are down nearly 4 percent following a downgrade by Bank of America, and the REM mortgage-backed securities fund has fallen to its lowest level in over six years.
Volatility in the foreign exchange market is moderate, and the dollar index is edging higher above the 101.70 level thanks to capital flowing back into the U.S. stock market. The euro is facing pressure from the widening spread between French and German bonds to 144 basis points, causing the EUR/USD pair to hover around $1.12 after a failed attempt to move higher. The Australian dollar has emerged as a clear beneficiary of the improved data from the Chinese economy, while the Japanese yen is losing about one-third of a percent, pushing the USDJPY exchange rate to around 158.45 yen. The Polish zloty remains very stable today, with the USDPLN exchange rate at around three zlotys and ninety groszy, and one euro costing four zlotys and thirty-seven groszy on the EURPLN pair.
Crude oil prices are stabilizing after last week’s rally to multi-month highs, as investors weigh profit-taking and U.S. exemptions from some sanctions on Russian exports against the risk of prolonged supply disruptions extending into 2027. On the trading platform, a barrel of Brent crude is priced at over 110 dollars, up more than half a percent, while WTI is up about one-third of a percent and trading at over 99 dollars. Mixed sentiment is evident in the precious metals market, where gold is correcting its recent moves by just under half a percent to $4,145 per ounce, while silver is gaining nearly half a percent and exceeding the $57 mark. The weakest performer in the energy sector today is U.S. natural gas (NATGAS), whose price is falling by more than 1.7 percent to around $3.06.
Improved sentiment toward risky assets and investors’ return to the tech sector are also having a positive impact on the cryptocurrency market. The leading cryptocurrency, Bitcoin, is gaining nearly one percent during today’s trading session, allowing it to maintain a high valuation above eighty-one thousand six hundred eighty dollars. Digital assets are moving in clear correlation with the US100 index, benefiting from the subsiding of last week’s panic over the costs of funding artificial intelligence. The stabilization of sentiment on Wall Street ahead of this season’s most important quarterly reports is allowing buyers to defend recent support levels in the crypto market.
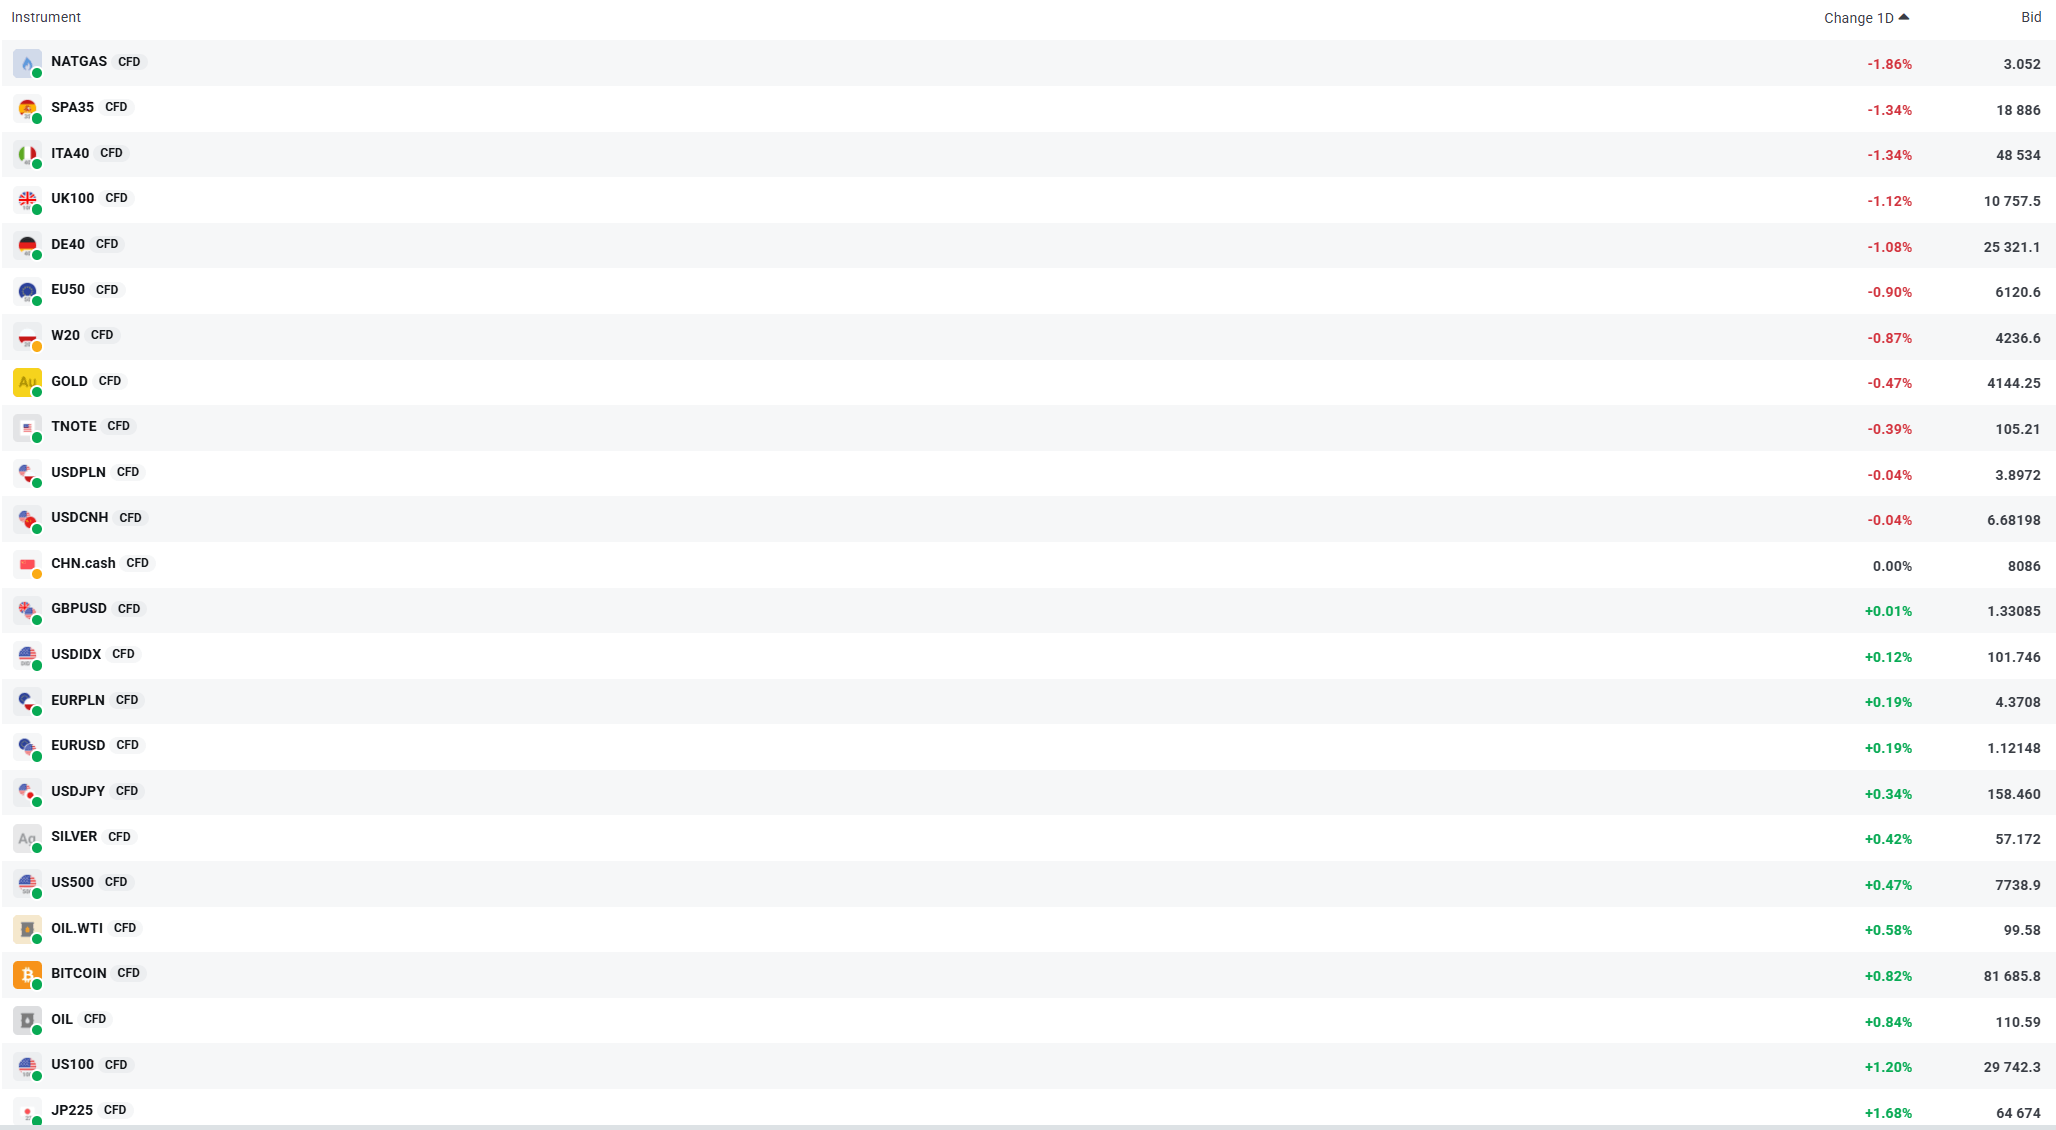
Current volatility in selected key instruments. Source: XTB


Wall Street rebounds🚨


Market Wrap: Rebound in China and Falling Oil Prices, France Leads EU Declines


Chart of the Day: What’s next for tech stocks after the deepest sell-off since April 2025? (19.10.2026)


Optimism Returns to Asia❔