


US indices are posting solid gains on Friday, with the S&P 500 up 0.7% and the Nasdaq 100 rebounding 1.7%, led by technology stocks that were heavily sold off yesterday, particularly semiconductor names. The stronger-than-expected NFP report has not derailed the rebound, although given the scale of Thursday’s sell-off, when the Nasdaq suffered its steepest decline in 19 months, the recovery remains relatively modest. On the earnings front, markets reacted positively to reports from Vistra Energy and Moderna, whose shares are up around 10% and 5%, respectively, while semiconductor giant Lam Research is gaining 8% after management announced a $25 billion share repurchase program.
The October NFP report clearly beat expectations, with employment rising by 165,000 versus the 65,000 forecast, including 159,000 new jobs in the private sector. The unemployment rate fell to 4.1% from 4.2%, while the labor force participation rate increased to 61.9%. The data confirm that the US labor market remains more resilient than expected. The strong report reduces the case for rapid policy easing by the Fed, while at the same time lowering recession concerns, although for equities the positive fundamental impulse may be partly offset by more hawkish expectations for the future path of interest rates.
EURUSD is down almost 0.6% today and has fallen below 1.115 following a series of stronger-than-expected US data, while the US Dollar Index futures contract (USDIDX) is trading close to local highs despite a pullback in US Treasury yields. At the same time, euro-area retail sales for September disappointed, falling 0.7% month over month versus a 0.1% decline expected and 0.1% growth previously. On an annual basis, sales increased by just 0.4%, below the 0.6% forecast and 0.8% previously.
Brent crude futures (OIL) are pulling back today after approaching $100 per barrel. According to The Times of Israel, Iran is reviewing proposals to limit its nuclear program, including measures related to its stockpile of highly enriched uranium, in exchange for potentially significant US sanctions relief. The fact that Tehran is considering such proposals is itself notable, as Iran had previously resisted discussions over restrictions on its nuclear program. Any progress could reduce the geopolitical risk premium in oil markets and support risk assets, although a formal agreement remains uncertain.
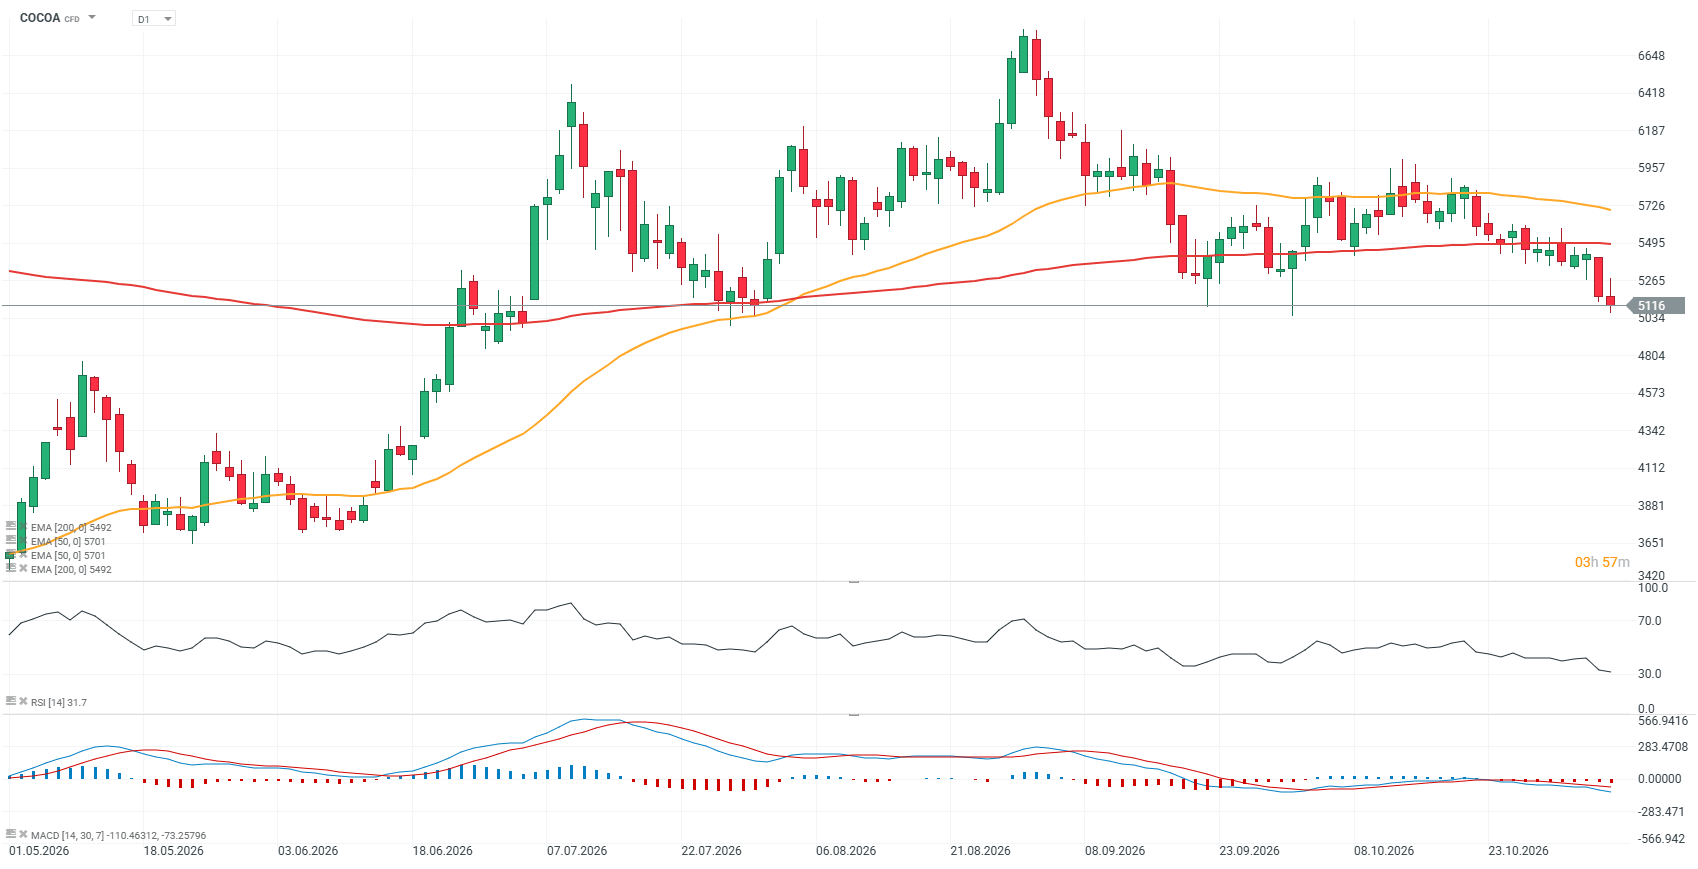
Gold is posting a modest decline but remains above $4,050 per ounce, while Bitcoin has failed to stage a meaningful rebound and is trading near $75,500. US Henry Hub natural gas futures (NATGAS) are slightly lower, while European natural gas futures (NATGAS.EU) are attempting to rebound after falling from around €100 to €84/MWh. Agricultural futures remain under pressure, with CBOT wheat and soybean contracts continuing their strong downtrend. ICE cocoa futures (COCOA) are retreating toward roughly $5,100 per tonne, an area that previously generated strong price reactions, while Arabica coffee futures (COFFEE) are attempting to stabilize after several very weak sessions.
Fed’s Mary Daly said the labor market remains solid, wage growth is not accelerating excessively, and the latest jobs report is good news that gives the Federal Reserve room to continue fighting inflation. At the same time, she stressed that services inflation is not declining as the central bank would expect and that her confidence in a sustained disinflationary process is still not high enough, meaning further policy tightening may be necessary. Daly also said that holding rates unchanged at the previous meeting was appropriate given the uncertainty, while the current repricing in the AI sector has so far remained orderly.
The preliminary University of Michigan consumer sentiment index rose in November to 51.0 points versus 48 expected and 48 previously. The expectations subindex improved to 50.9 from 48.8, while the current conditions index rose to 51.0 from 46.7, also clearly beating forecasts. At the same time, inflation expectations declined, with the one-year measure falling to 4.3% from 4.7% versus 4.6% expected, while the five-year measure eased to 3.4% from 3.5%, compared with expectations for no change. Overall, the data are relatively supportive for markets, combining an improvement in consumer sentiment with somewhat softer inflation expectations.
OpenAI intends to continue aggressive investment in AI infrastructure despite concerns over growing social and political opposition to data center development in the US. CFO Sarah Friar stressed that the midterm election results do not change the company’s strategy, as OpenAI still plans to rapidly expand computing capacity, deepen cooperation with hyperscalers and continue raising capital. The announcement was received positively by markets, although the future pace of investment will increasingly depend on local regulation, energy costs and access to financing.
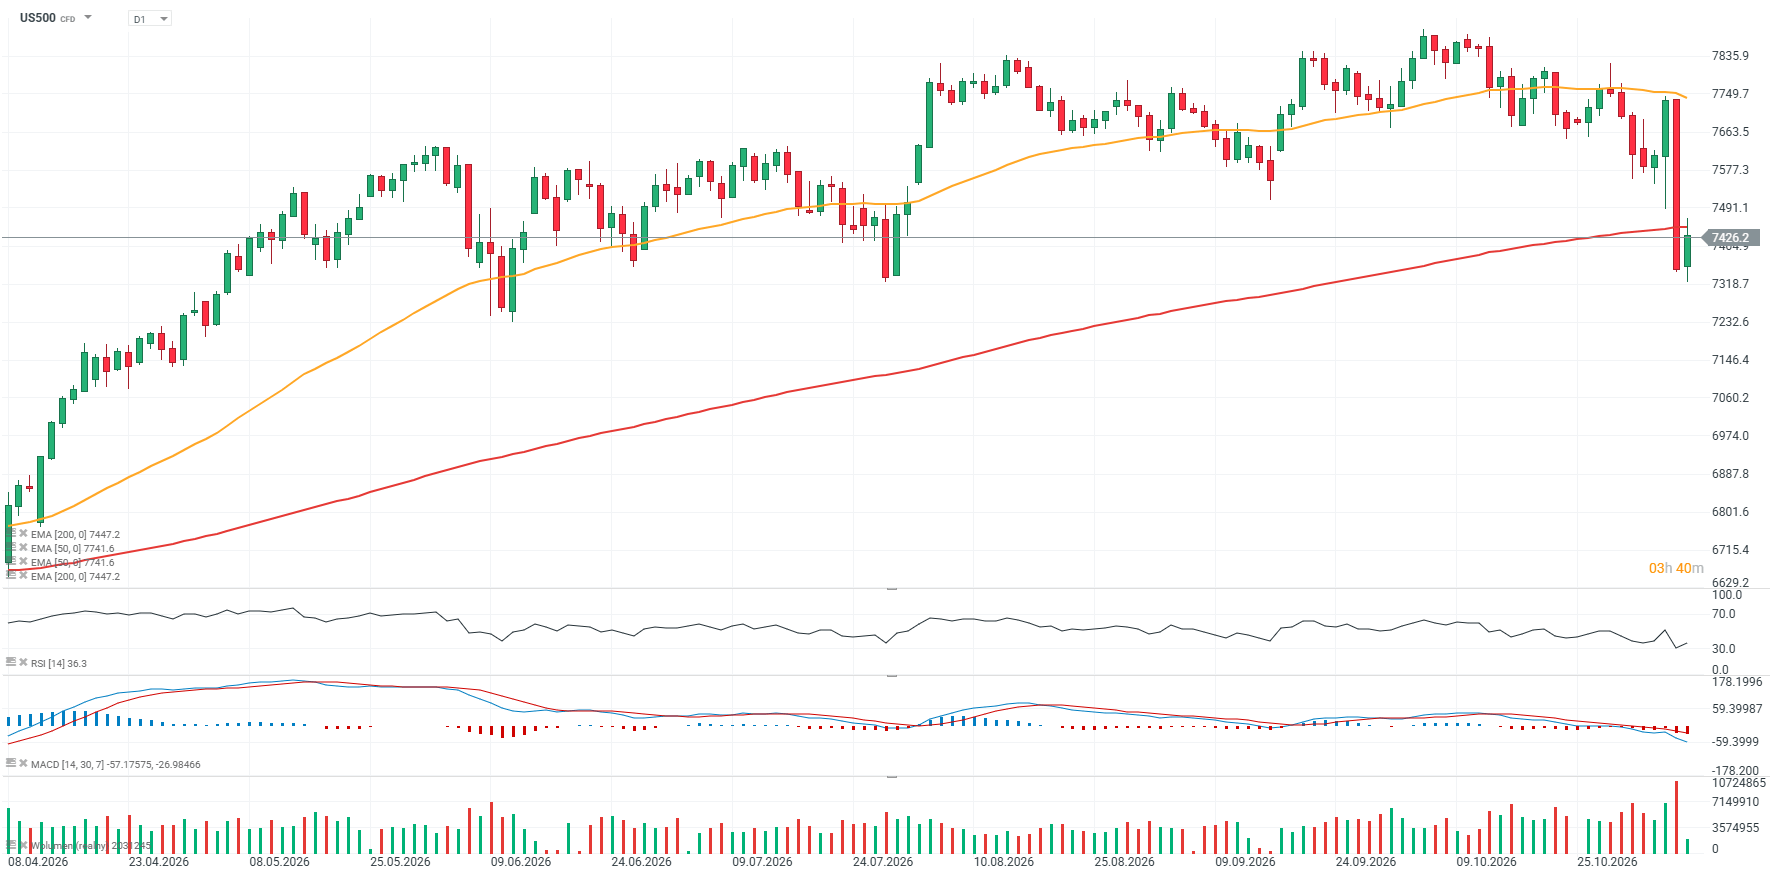
US500, COCOA (D1 interval)
As we can see on the technical chart below, US500 gains but struggle to rise above a major resistance zone near EMA200 (the red line). If the conctract close today US session below 7500 pts, we can expect that investors may become nervous again, in the beginning of the next week. On the other hand 7300 pts level is the major support zone now.
Source: xStation5
Source: xStation5


Vistra shares surge nearly 10% after earnings, driven by strong AI power demand


3 markets to watch next week: GBPUSD, US500, OIL (06.11.2026)

OpenAI plans to continue investment in AI data centers 📈 Nasdaq rebound continues

US Open: Nasdaq rebounds after the largest decline since 19-month 🔼 Lam Research surges 12%