


- Revenue fell this quarter to $10.60 billion, which was in line with consensus. Year over year, the company still records noticeable growth.
- Where the results shine the brightest is profitability, with EPS reaching $1.28, beating market expectations by over 30%.
- LfL sales increased by 4%.
- Gross margin rose to as much as 29.9%, representing a 1% year-over-year increase.
- Nominally, net profit increased by as much as 43.8% year over year, amounting to $282.7 million.
The management boasted about opening 196 new stores, modernizing 1,100 existing ones, and announced a dividend of $0.59. The management stated that next year they want to maintain the pace and achieve net sales growth of 4.7-4.9 percent, which is an increase from the previous forecasted level of 4.3-4.8.
Investors in the unassuming company seem to be on the verge of euphoria. The company presented very good results and even better forecasts despite market concerns about the condition of the American consumer. Concerns about the job market and consumer or broadly defined recession may, however, start to work in favor of companies like Dollar General. The store belongs to the budget segment. In times of weak economic conditions, such stores do not lose customers or revenue because their customers have no reason to limit their consumption, but they gain new customers who, in better times, would dine in restaurants or buy better products in more expensive stores.
DG.US (D1)
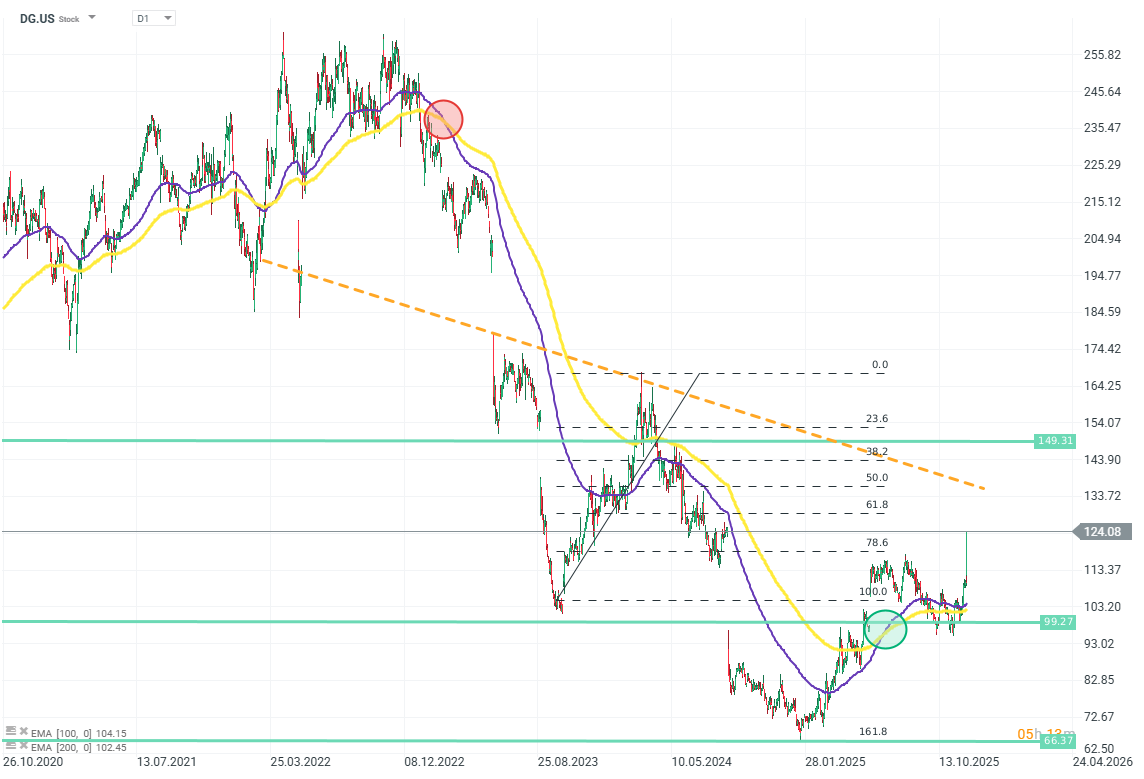
Source: xStation5



US Open: Nasdaq 100 rises nearly 2% as CoreWeave and Nvidia rebound 📈 EURUSD hits its lowest level since May 12, 2026

Market wrap: Siemens Energy gains 9% after earnings 📈 European earnings season in focus


Nvidia shares suffer their biggest drop since 2025 🚩 What’s next for the AI giant?

Chart of the day 🚩 Cocoa sell-off continues. Record ICE inventories and index rebalancing in focus (11.11.2026)