


Thursday will be heavy with U.S. macroeconomic data releases, which could potentially shift investors’ focus from geopolitical issues to economic momentum.
The highlight will be the final reading of U.S. GDP for the third quarter of 2025, which according to the Bloomberg consensus is expected to show growth of 4.3% (previously: 3.8%). Private consumption played a particularly important role in Q3, so a continuation of this trend and a potentially stronger-than-expected reading could significantly push market expectations for the Fed toward less willingness to continue cutting interest rates.
Alongside GDP, reports on PCE inflation for October and November will also be released, including the Fed’s preferred Core PCE measure. The picture will be complemented by weekly jobless claims, which have been in a strong downward trend for weeks, thereby easing concerns about the U.S. labor market.
For the Euro Area the key release will be the minutes from the latest ECB meeting.
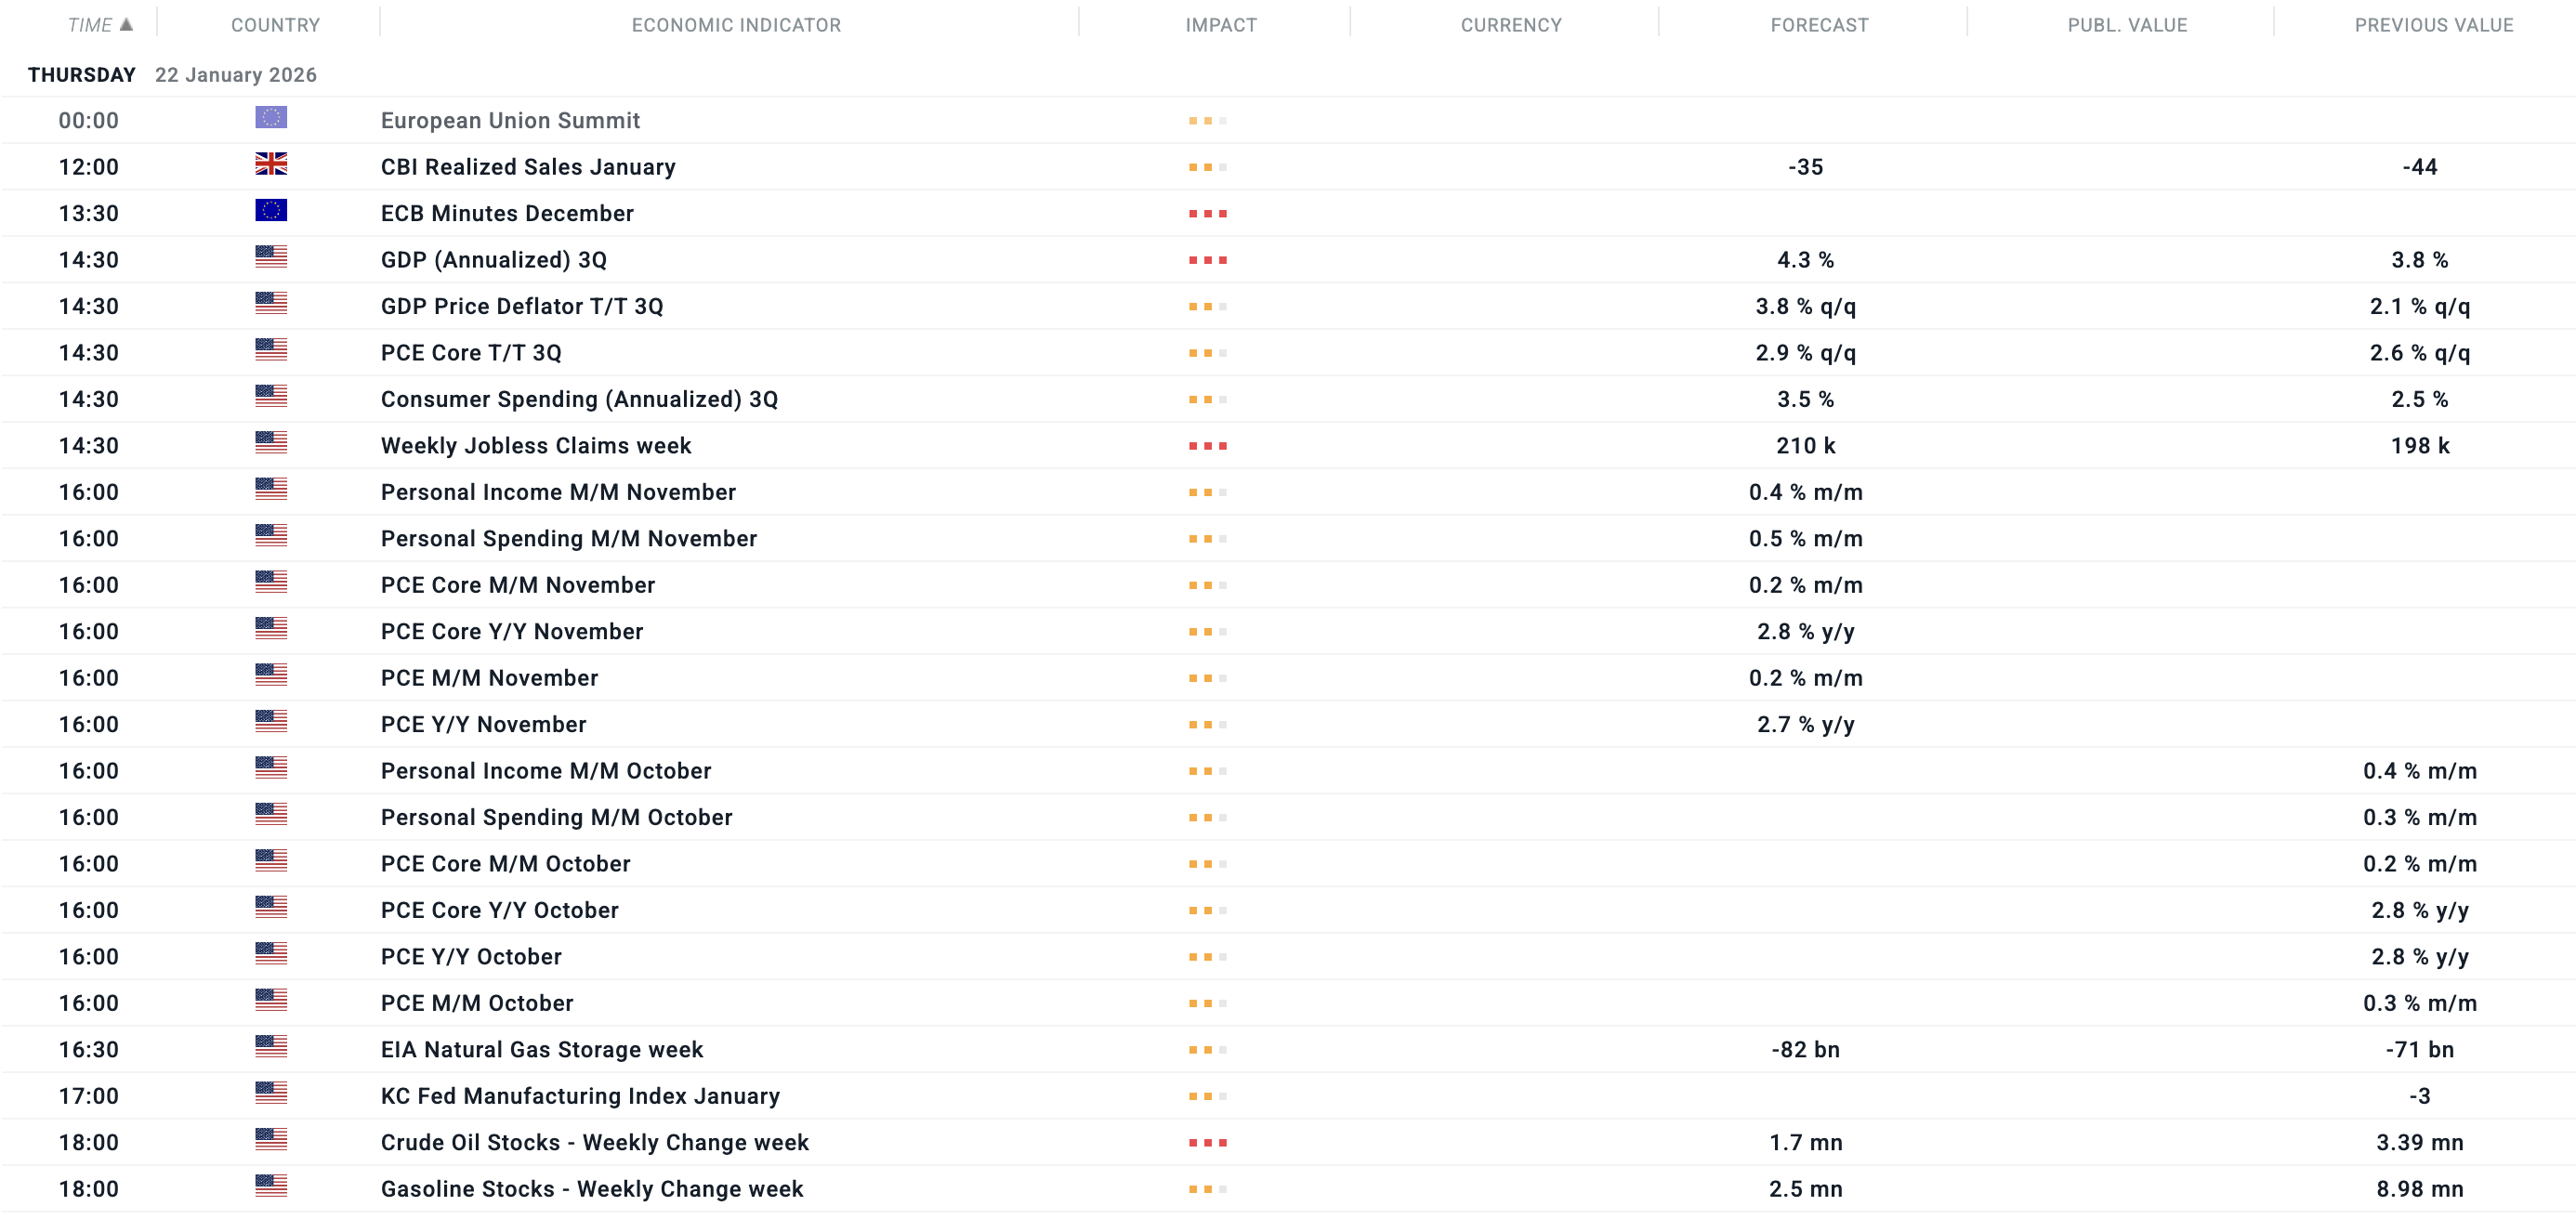
All times CET; filtered by: US, UK, Eurozone, Germany. Source: xStation5


BREAKING: US NFP much stronger than expected 📈 US Dollar and treasuries yields surge


Market Wrap: Weak Europe, AI Debt, and Awaiting US Data


Copper hits lowest level since late July 📉 Markets price in AI concerns and a shift in US trade policy?
EURUSD loses ground ahead of NFP