

- The Reserve Bank of Australia raised the cash rate by 25 basis points to 4.60%.
- Australian household spending stagnated at 0.0% MoM amidst persistent inflation pressures.
- Upcoming US labor market data and central bank speeches can drive higher market volatility.
- AUDUSD is testing the psychological support level of 0.70 after a sharp sell-off.
The Asian session brought a key decision from the Reserve Bank of Australia (RBA), which raised interest rates as expected by 25 basis points to 4.60%, citing elevated inflation risks and geopolitical tensions in the Middle East.
Accompanying data on household spending in Australia showed stagnation (0.0% MoM vs 0.3% consensus), confirming an economic slowdown amidst persistent price pressures.
In the UK, the BRC Shop Price Index fell to 1.4% YoY. The calendar for the rest of the day is dominated by speeches from central bank representatives (Fed, ECB, RBA, Bank of England) as well as key US labor market data (JOLTS) and the Conference Board Consumer Confidence Index, which could trigger elevated volatility in foreign exchange and debt markets.
Key Releases from the Asian Session
- UK BRC Shop Price Index (YoY): actual 1.4% vs 1.5% previously.
- Australian Household Spending (MoM): actual 0.0% vs 0.3% consensus and 1.1% previously.
- RBA Interest Rate (Cash Rate): actual 4.60% (25 bps hike) in line with consensus, supported by a hawkish statement on inflation risks.
Macroeconomic Calendar (CET time zone)
- 06:30 Australia - RBA Interest Rate Decision.
- 07:30 Australia - RBA Press Conference.
- 09:00 Switzerland - KOF Economic Barometer. Consensus: 106.0. Previous: 106.7.
- 09:00 Spain - Flash CPI (YoY). Consensus: 4.6%. Previous: 4.3%.
- 10:30 United Kingdom - Mortgage Approvals. Consensus: 56k. Previous: 56k.
- 12:00 Eurozone - Speech by Bundesbank President Nagel.
- 13:00 Eurozone - Speech by ECB President Lagarde.
- 14:30 Canada - GDP (MoM). Consensus: 0.0%. Previous: 0.3%.
- 15:00 USA - HPI House Price Index (MoM). Consensus: 0.1%. Previous: 0.0%.
- 15:00 USA - S&P/CS Composite-20 House Price Index (YoY). Consensus: 2.2%. Previous: 2.1%.
- 16:00 USA - Conference Board Consumer Confidence. Consensus: 89.2. Previous: 89.4.
- 16:00 USA - JOLTS Job Openings. Consensus: 7.23M. Previous: 7.27M.
- 17:00 United Kingdom - Speech by MPC Member Mann.
- 17:00 USA - Speech by FOMC Member Bowman.
- 17:30 United Kingdom - Speech by MPC Member Taylor.
- 18:40 USA - Speech by FOMC Member Barr.
- 19:00 USA - Speech by FOMC Member Goolsbee.
- 19:30 USA - Speech by FOMC Member Musalem.
- 20:00 USA - Speech by FOMC Member Williams.
- 21:00 USA - Speech by FOMC Member Waller.
- 22:30 USA - Weekly API Crude Oil Stock Report.
Markets to Watch
- AUD (Australian Dollar): The reaction to the RBA's hawkish statement and rate hike is causing increased volatility in commodity currencies.
- USD (US Dollar): A series of afternoon releases from the US (including JOLTS and consumer confidence) along with numerous speeches from FOMC members will determine the sentiment around the US currency.
- Debt Markets (Government Bonds): Scheduled bond auctions in Italy and the UK, alongside close monitoring of yields in Asia and Europe, place the debt market at the center of investor attention.
AUDUSD — Technical Analysis (D1)
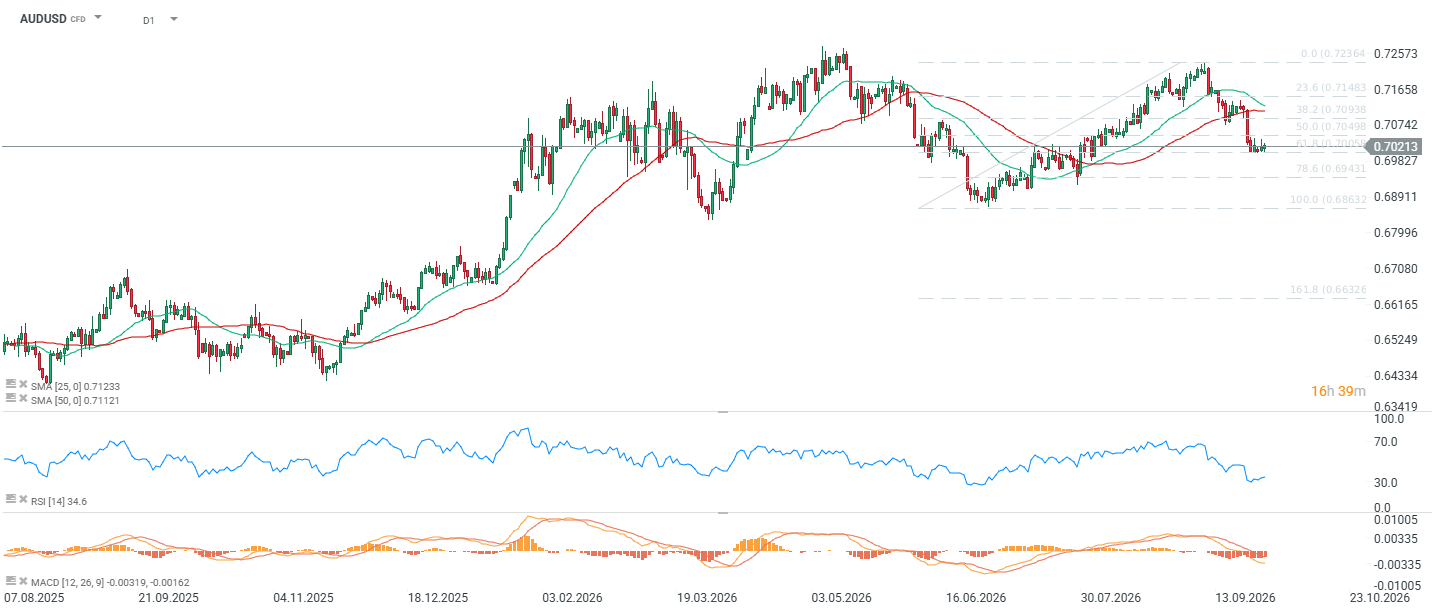
The Australian dollar exchange rate is testing an important round level of 0.70 after a sharp sell-off in recent sessions. The movement was impulsive, with one large bearish candle erasing the gains of several sessions and crossing below the important 50-period moving average.
The moving average layout has significantly deteriorated. Price is trading below the SMA25 (0.71233) and SMA50 (0.71121), and the averages themselves are beginning to converge, which, under sustained supply pressure, opens the door to a bearish cross. As long as the rate does not reclaim the 0.7112–0.7123 area, initiative remains on the side of the bears.
The reaction at Fibonacci retracements is key. Quotes stopped precisely between the 61.8% level (0.70065) and 50% (0.70498) — a natural first support zone. Breaking below this area would expose the market to a test of the 78.6% level at 0.69431, and subsequently the June low of 0.68632. To the upside, the nearest resistance lies at 38.2% in the 0.70938 region, reinforced by the presence of the moving averages.
Indicators confirm weakness while also signaling exhaustion of the move. RSI at 34.6 is approaching oversold territory — historically, in this setup, the rate has halted momentum multiple times. MACD (-0.00319) crossed below the signal line (-0.00162) from above, and the histogram remains negative, indicating an active bearish impulse without signs of divergence.
In the base-case scenario, an attempt to stabilize within the 0.7000–0.7050 range and a technical correction toward 0.7094 can be expected. A sustained move below 0.7000, breaking both the 61.8% retracement and psychological level simultaneously, would signal a continuation toward the June lows.



Morning Briefing: Higher Rates in Australia and Further Rise in Oil Prices


Daily Summary: Lack of progress in negotiations weighs on Wall Street and precious metals (28.09.2026)


US Open: Wall Street starts the week in red (28.09.2026)

📊Market Wrap: Oil drives yields higher and gold lower (28.09.2026)