

- The BLS publishes the October CPI inflation reading today at 14:30.
- Bloomberg consensus expects monthly price growth of 0.3%.
- Lower fuel prices and slowing services can pull inflation down.
- A core reading around 0.2% can weaken the dollar and challenge December Fed moves.
- Higher core inflation can seal a rate hike and strengthen rate expectations.
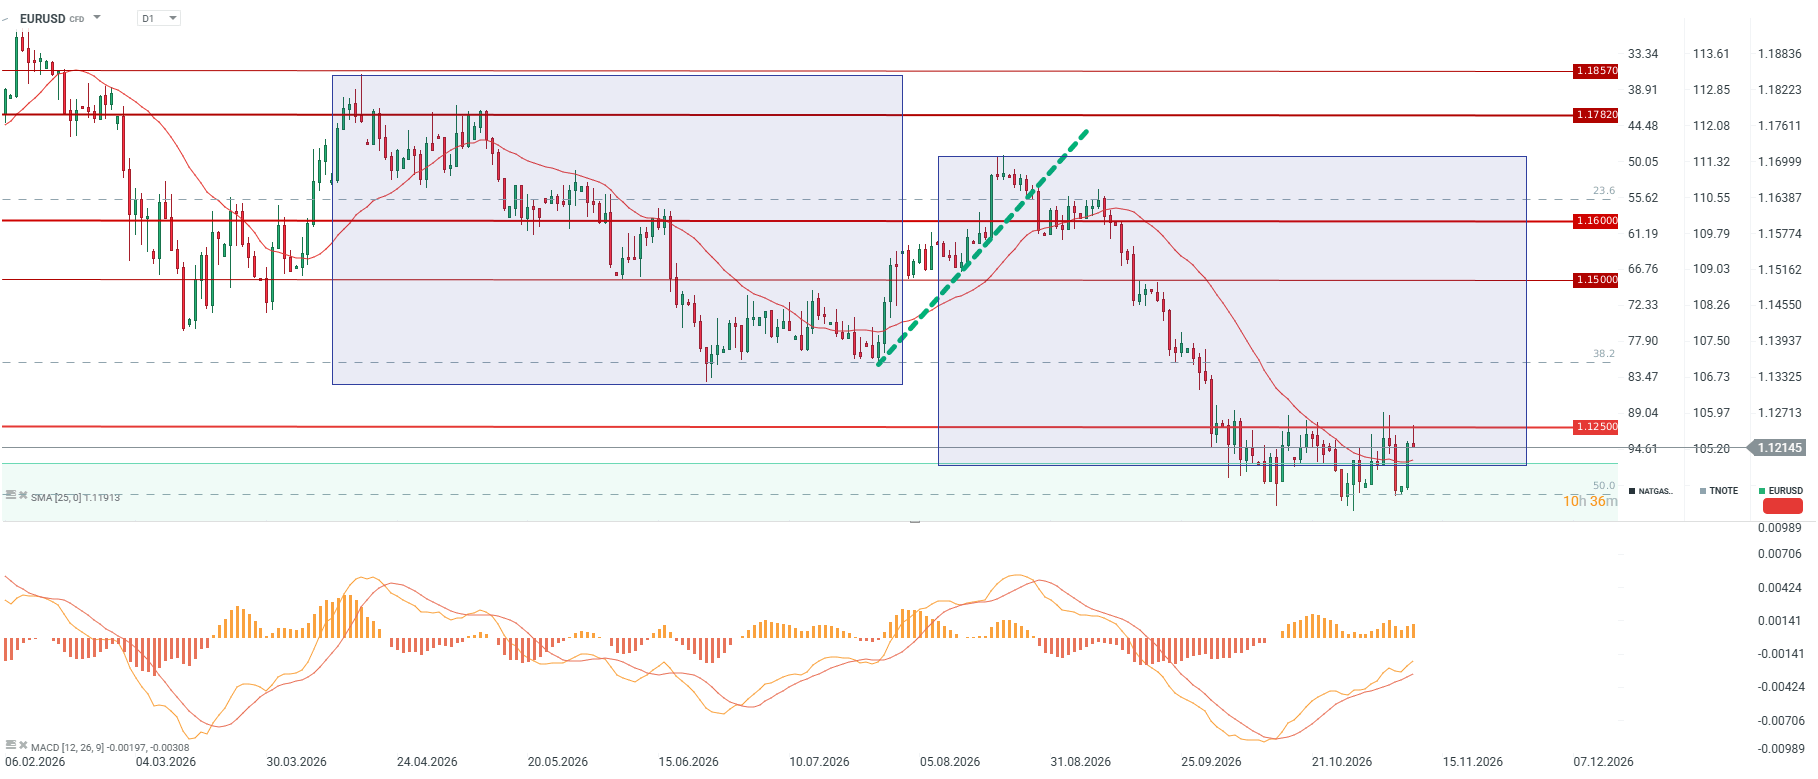
- EURUSD holds above SMA25 at 1.1191 while testing resistance near 1.1250.

- The BLS publishes the October CPI inflation reading today at 14:30.
- Bloomberg consensus expects monthly price growth of 0.3%.
- Lower fuel prices and slowing services can pull inflation down.
- A core reading around 0.2% can weaken the dollar and challenge December Fed moves.
- Higher core inflation can seal a rate hike and strengthen rate expectations.
- EURUSD holds above SMA25 at 1.1191 while testing resistance near 1.1250.
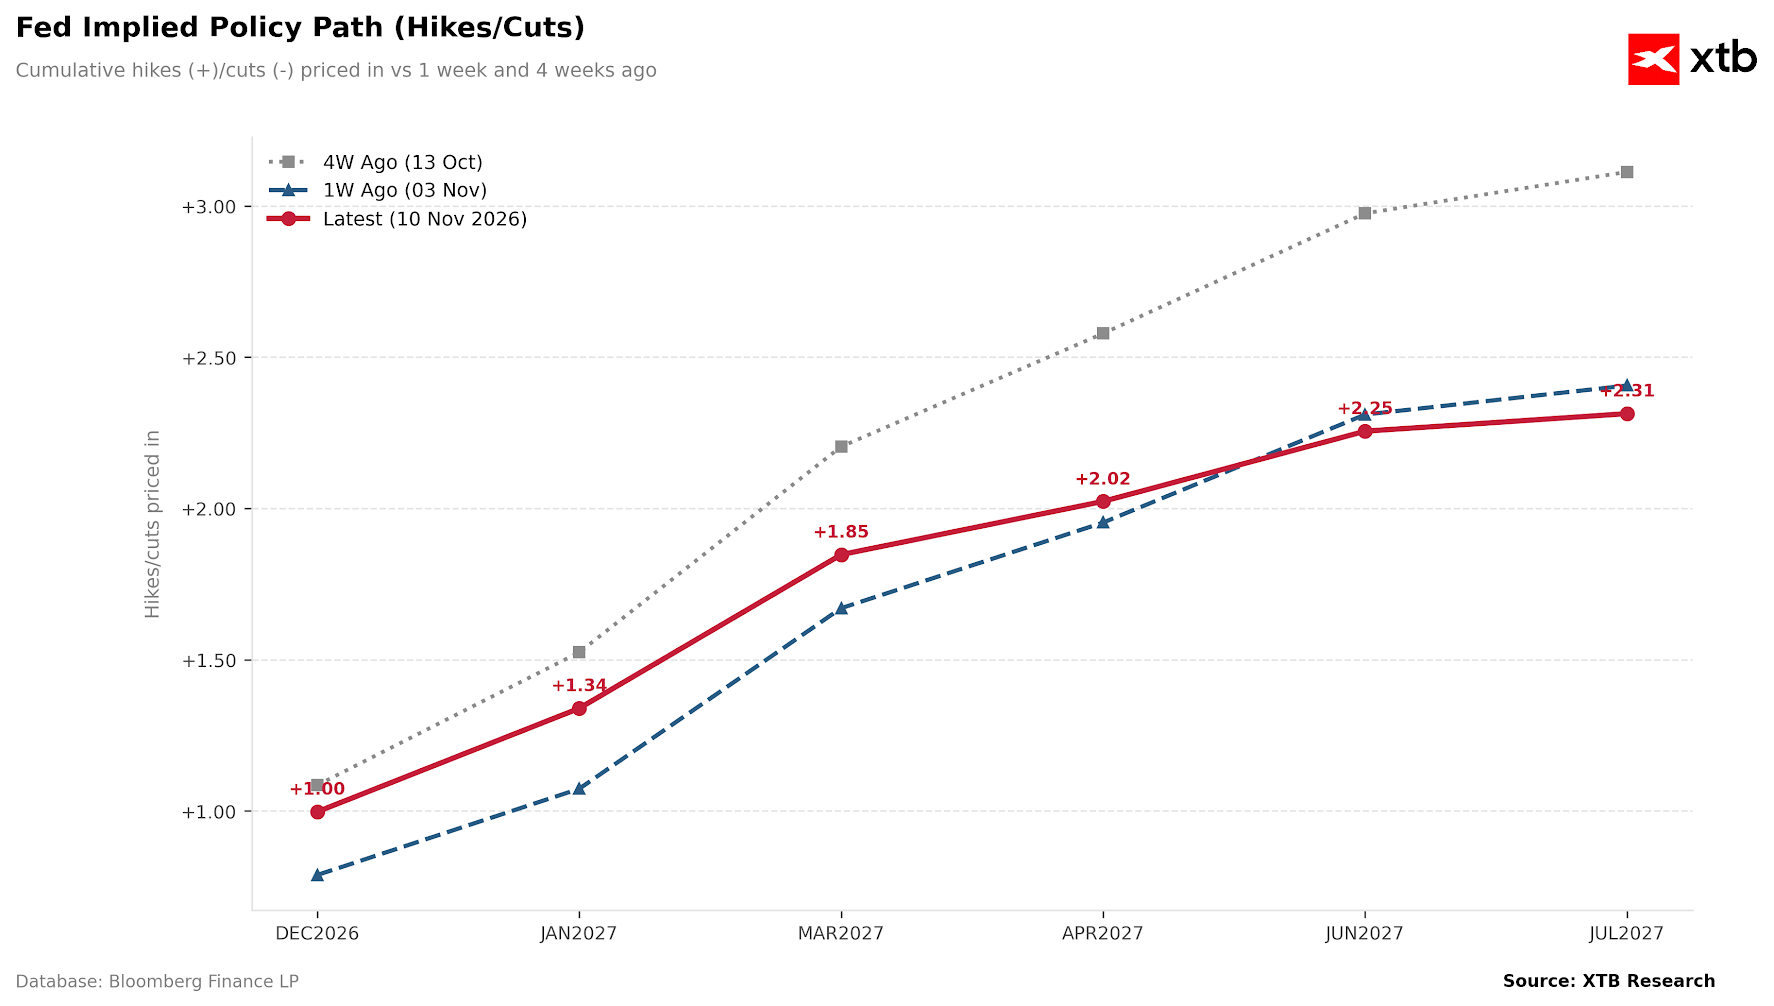
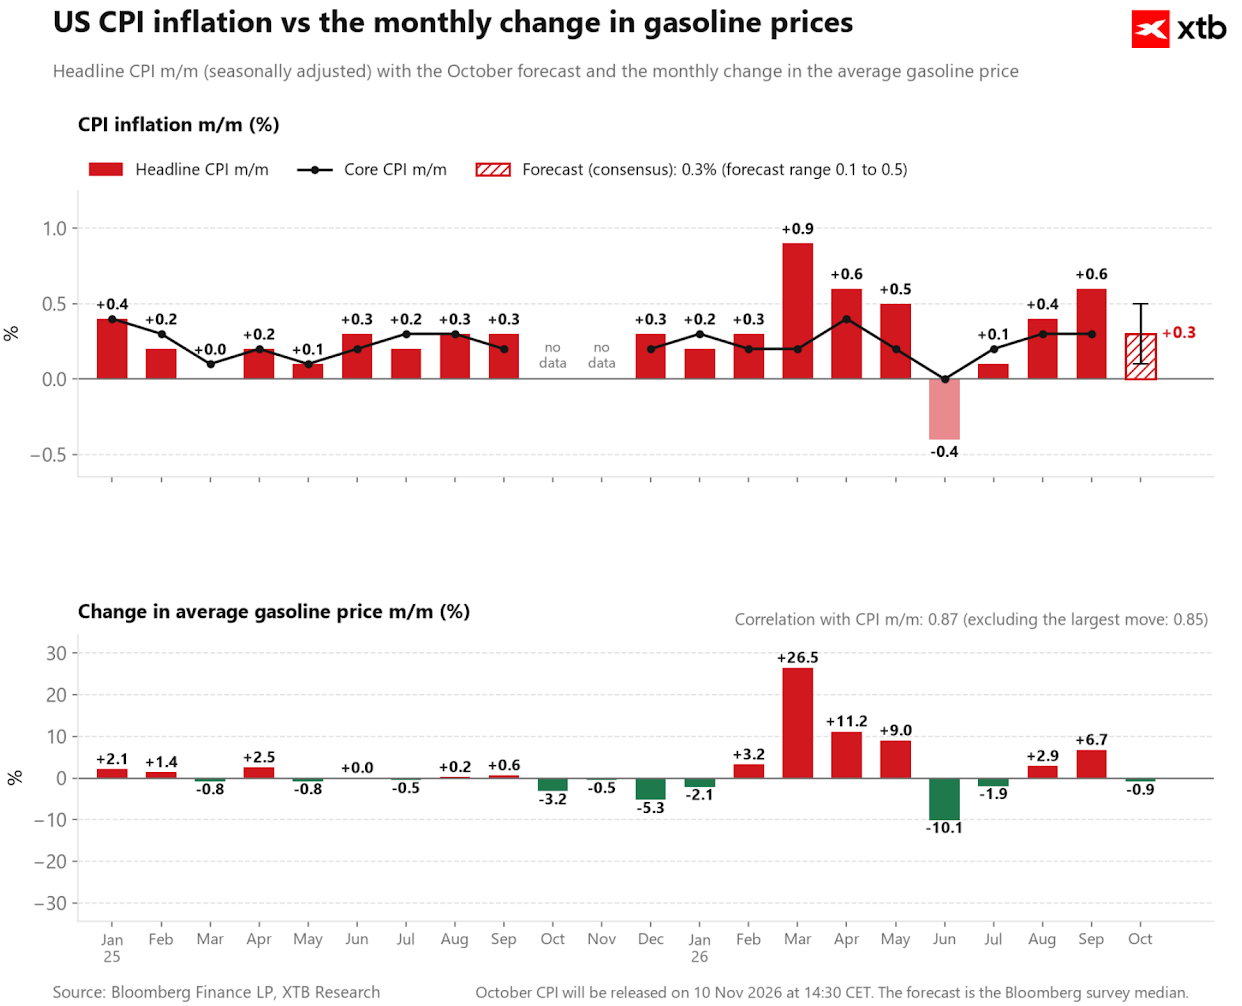
Today at 02:30 pm CET, the BLS will publish the October CPI inflation reading. This is the last inflation report before the FOMC meeting on December 8–9, and the market has almost fully priced in a rate hike. It will be a rather specific report. Due to last year's government shutdown, we will only learn the perceived monthly inflation. Bloomberg consensus assumes price growth of 0.3% m/m (forecast range from 0.1% to 0.5%), down from 0.6% in September. Bloomberg in its forecasts is even more dovish and points to lower fuel prices, which could lead to a reading closer to 0.2%. Such a reading would not rule out a rate hike, but it would not guarantee it either. On the other hand, rate hike valuations are already certain, but questions regarding US monetary policy should concern the future rate path for next year.
Key Takeaways:
- Fuels stop pushing inflation up. Gasoline fell in price by 0.9% m/m in October, after a 6.7% increase in September. The contribution of energy to overall inflation is expected to drop from 39 to approx. 4 bps.
- Core inflation is expected to slow down. Goods prices are stagnating as used cars and clothing become cheaper. Services are slowing to 0.3% m/m thanks to OER normalization.
- BLS will not provide annual dynamics due to a data gap following last year's shutdown. Bloomberg estimates point to 3.8% y/y for headline inflation and 2.5% y/y for core inflation.
What does this mean for the market?
Since the rate hike is already almost fully priced in, the market will react asymmetrically. A core reading around 0.2% m/m could challenge the Fed's December move, or at least reduce the prospects for further moves, especially amid tightening financial conditions and a correction in AI stocks, ultimately weakening the dollar. Core inflation at 0.4% m/m or higher would seal the hike and could prompt the market to price in further ones.
How does EURUSD look?
The pair is pulling back ahead of the release from resistance near 1.1250, which has regularly stopped buyers since mid-October. The rate (1.1215) is still holding above the SMA25 (1.1191), and MACD is rising with a positive histogram, indicating a gradual rebuilding of momentum following the September–October sell-off. A weaker CPI and a breakout above 1.1250 would open the way towards 1.1390 (38.2% retracement) and further to 1.1500. Higher-than-expected core inflation, on the other hand, risks a move below SMA25 and a test of the lower boundary of the consolidation range around 1.1150–1.1170.



📈Morning Wrap: Tech Bounce and Oil Price Collapse Following Signals of De-escalation Around Iran


Daily Summary: From Panic to Euphoria. The Market Recoups Losses.

EURUSD loses ground ahead of NFP


Norges Bank keeps rates unchanged, but leaves the door open to rate hikes. Is this really the end of the NOK strengthening, though?