


European indices are attempting to recover part of Thursday’s technology-led losses, with sentiment supported by stabilisation in bond markets and a weaker U.S. dollar. Investors nevertheless remain cautious about valuations across AI-related companies, particularly where infrastructure expansion relies on high leverage and aggressive assumptions about future profitability. Today’s rebound therefore looks more like a recovery after a sharp move than a full easing of concerns around interest rates, AI investment financing and the quality of future earnings.
- The Euro STOXX 600 is up around 0.6%, the Euro Stoxx 50 nearly 0.8%, Germany’s DAX around 1%, and France’s CAC 40 around 0.1%, while the FTSE 100 remains close to flat. In Poland, the WIG20 is gaining more than 0.8% and climbing to record highs.
- U.S. index futures are also pointing to another rebound attempt after yesterday’s session, when markets began to stabilise following sharp losses, although technology and AI infrastructure-related stocks remain the main source of uncertainty.
- European defense stocks rose sharply as European leaders gathered in Brussels to show support for President Volodymyr Zelenskiy. Rheinmetall gained 4.4%, Leonardo 3.9%, Thales 2.6%, Saab 3.5%, and BAE Systems 1.8%. Hensoldt was the strongest performer, with its shares rising by around 6%.
- Brent crude is trading around $105.2 per barrel, but remains higher on the week amid risks of further supply disruptions in the Middle East. The growing number of incidents around the Strait of Hormuz continues to support a geopolitical risk premium in oil prices and limits the scale of today’s decline.
- The market is increasingly focusing not only on the pace of revenue growth across the AI sector, but also on data-centre financing structures, returns on invested capital and companies’ ability to monetise massive capital expenditures.
- Concerns over persistent inflation had previously increased expectations for higher U.S. interest rates, while subsequent inflows into government bonds pushed yields lower and provided some temporary relief for risk assets.
- The U.S. Dollar Index is down around 0.4% to 101.68 and is heading for its first weekly decline after three consecutive weeks of gains, as lower U.S. Treasury yields reduce the relative attractiveness of the dollar.
- EURUSD is rebounding from its recent 17-month low and has risen to around 1.1255, benefiting primarily from the weaker U.S. dollar.
- European bond yields are edging slightly higher today, but remain lower on the week; Germany’s 10-year Bund yield is trading around 3.4%. It is also worth noting the shift in the correlation between bonds and equities: German government bonds are once again beginning to play a clearer safe-haven role, suggesting a return of the more traditional flow of capital from risk assets into sovereign debt.
- Most Asian equity markets rebounded, but Indonesia was a notable exception, suffering its sharpest decline since 1998 after MSCI signalled that the country could lose its emerging-market status. Such a decision could trigger billions of dollars in passive outflows from funds tracking MSCI indices.
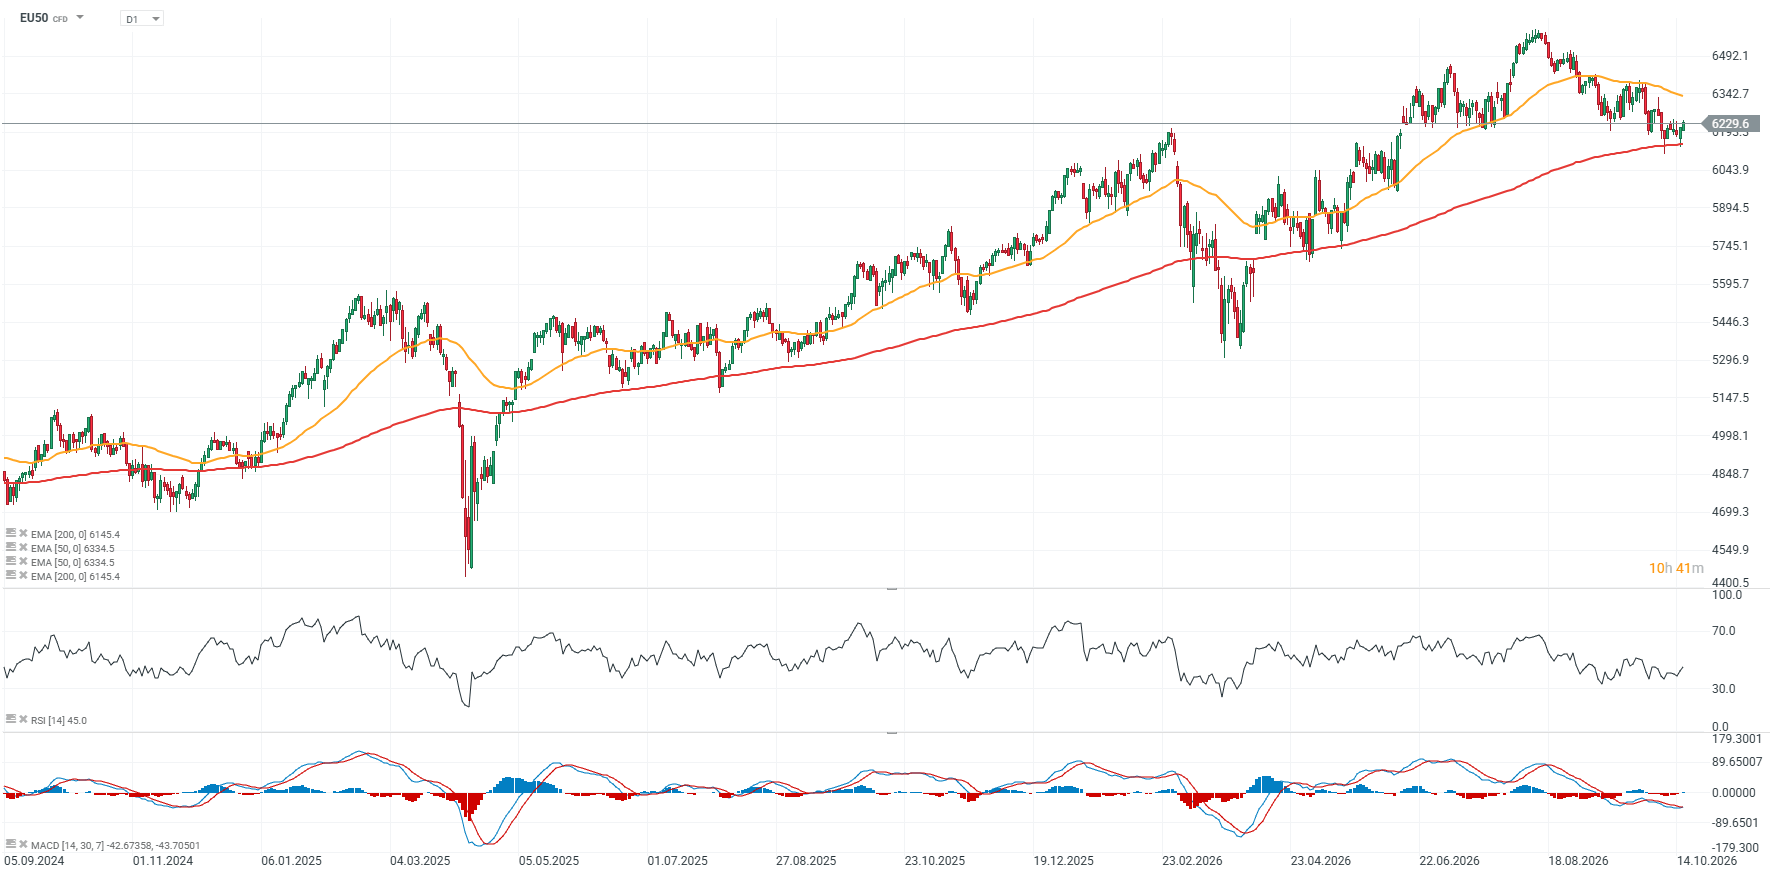
EU50 chart (D1 interval)
The Euro Stoxx 50 futures contract is attempting to halt the sell-off after retreating toward the 200-session EMA (red line). The 6,150–6,200 point area remains the key support zone for the contract. The main resistance is located around 6,300 points, defined by the 50-session EMA (orange line) and previous price reactions.
Source: xStation5
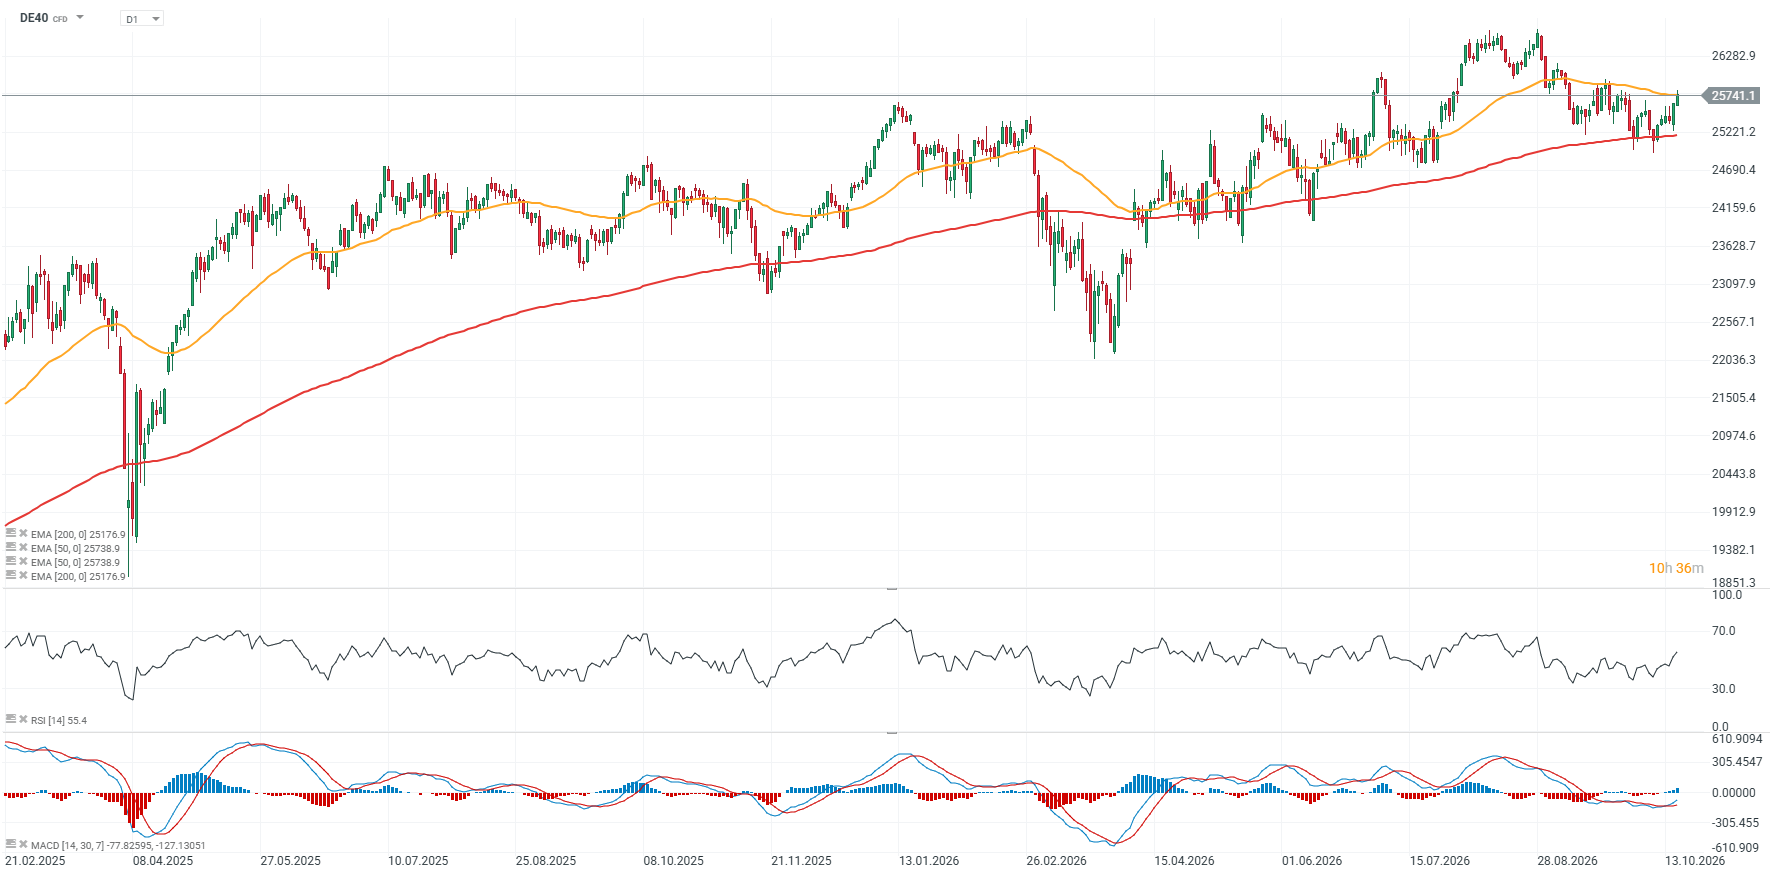
The DAX futures contract has resisted the recent sell-off and is posting a second consecutive session of gains, returning to levels not seen since the beginning of October. The index has repeatedly found support at the 200-session EMA (red line) this year, and a similar scenario appears to be unfolding again. The nearest resistance is around 26,000 points, and a breakout above this level could open the way for a test of the all-time highs over the coming weeks. Important support is located around 25,200 points, where the EMA200 and previous price reactions converge.
 Source: xStation5
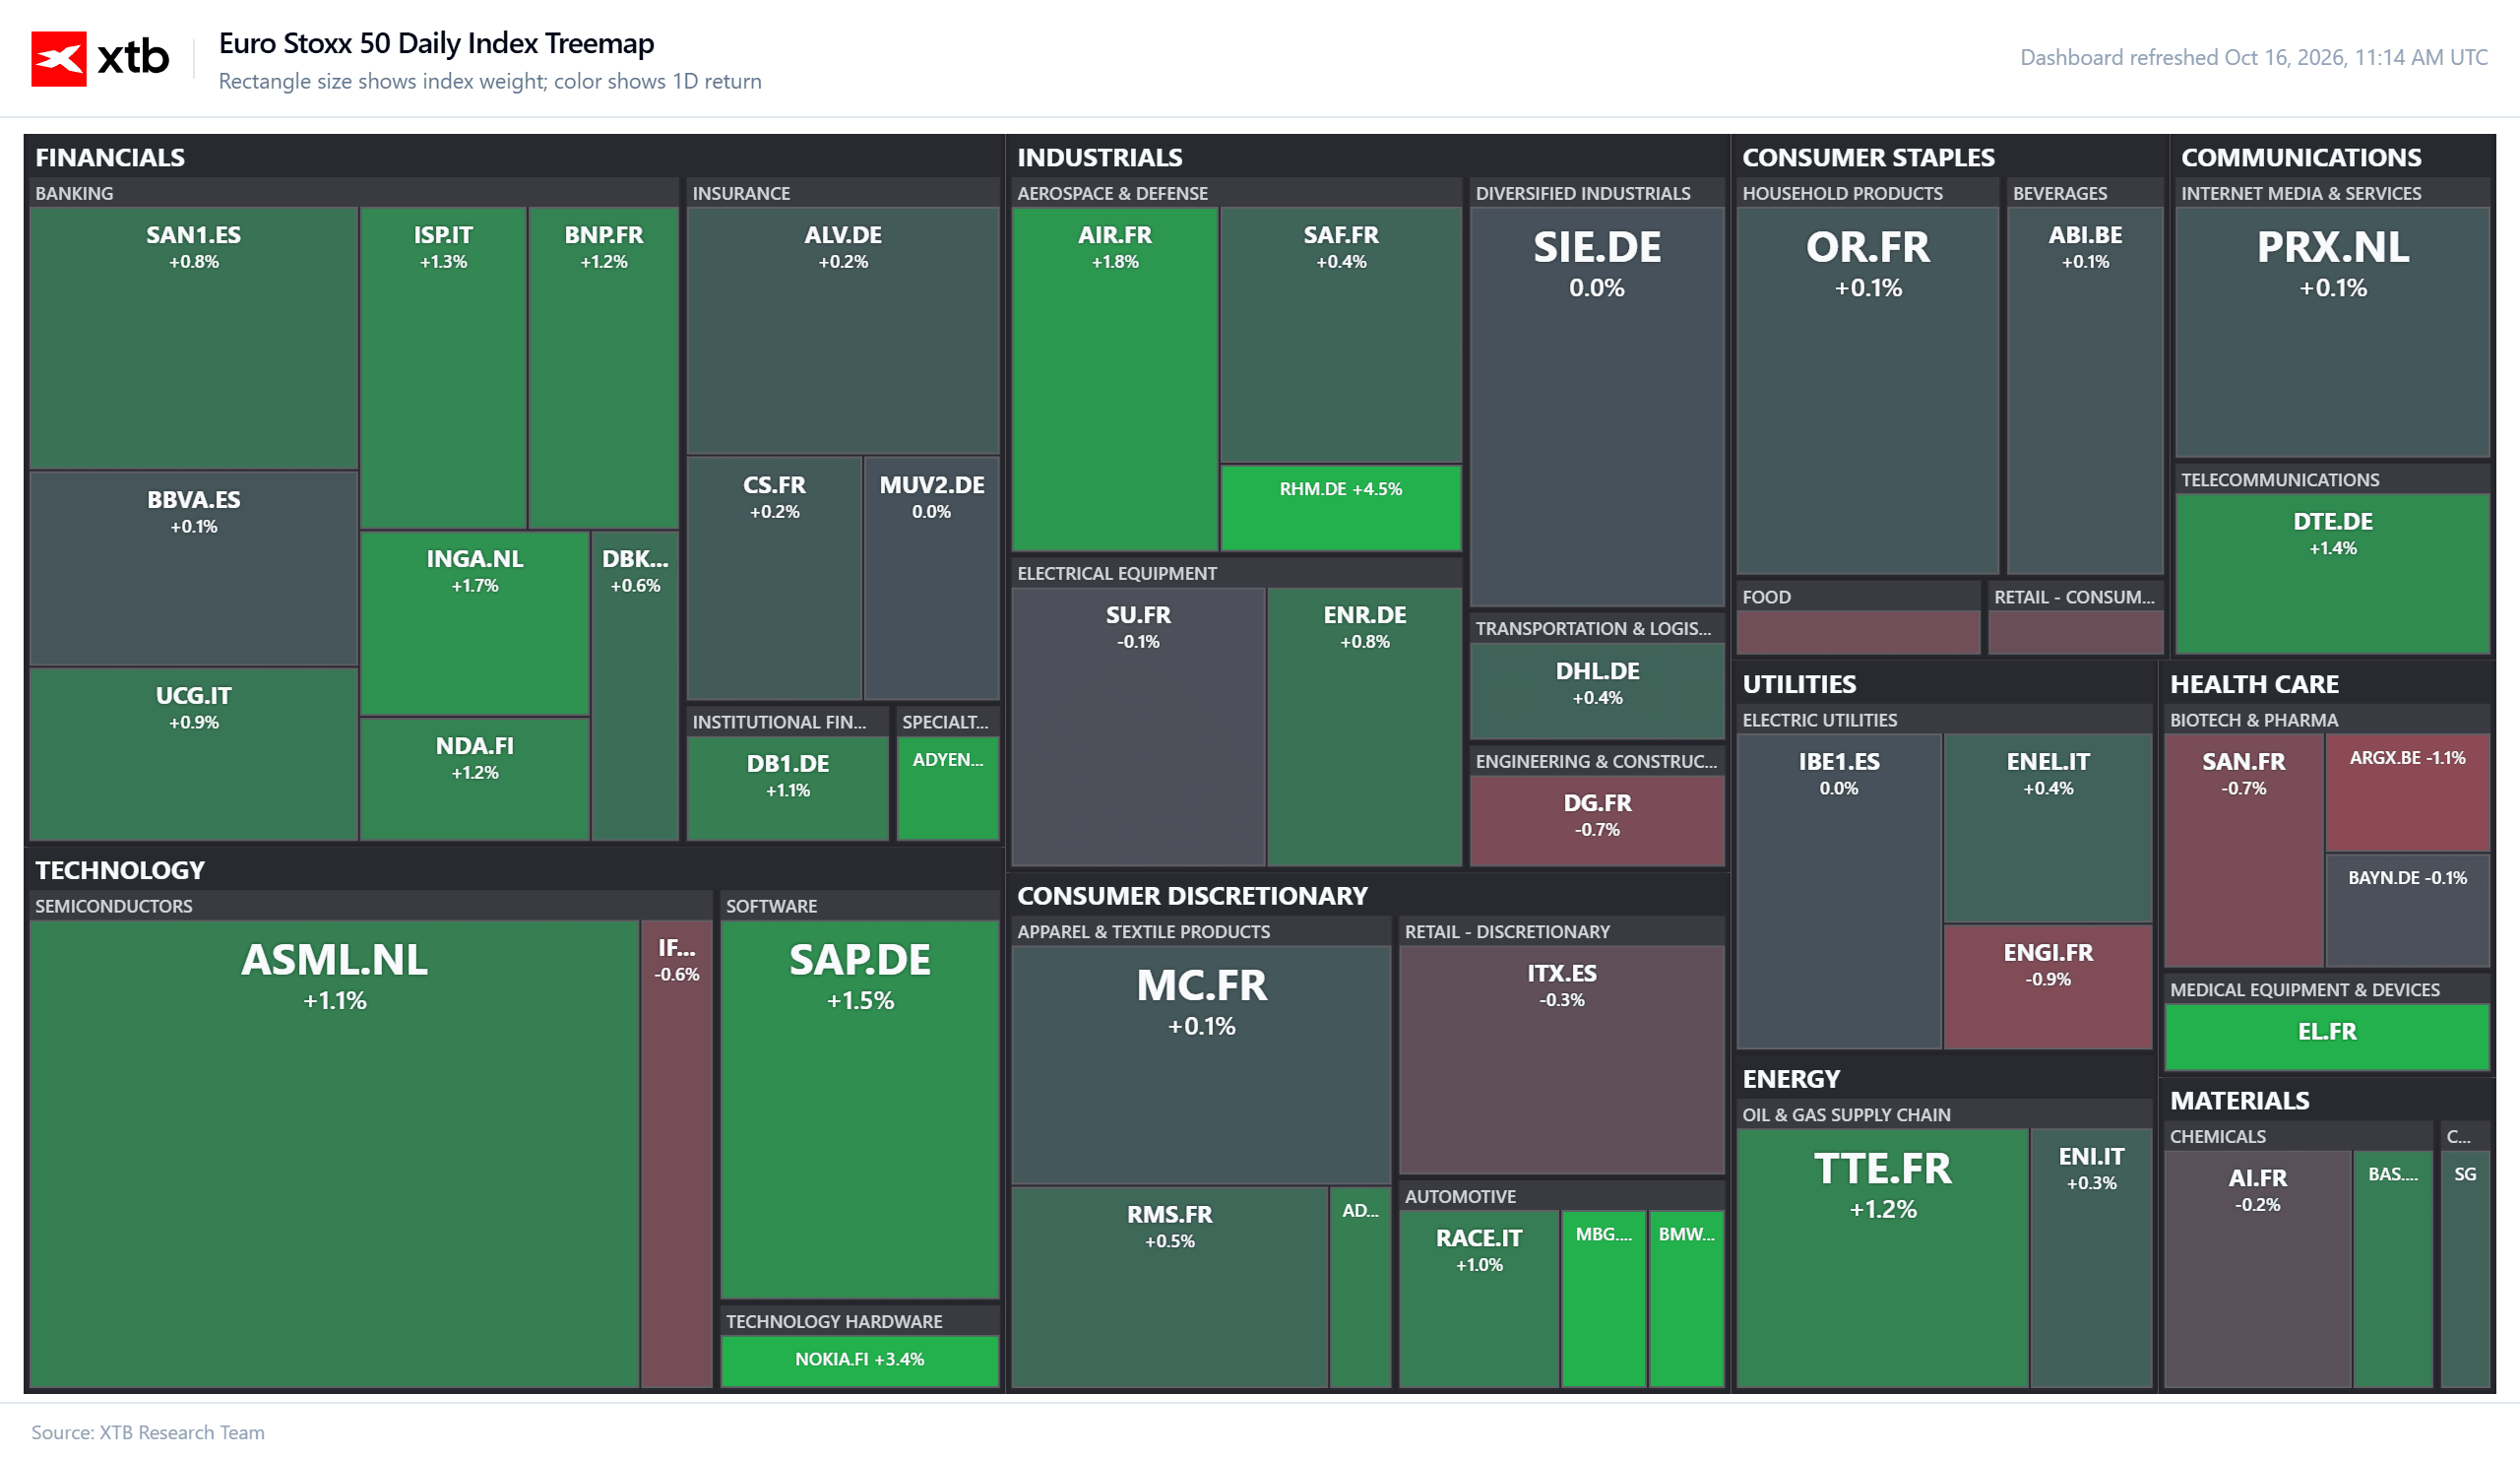
Euro Stoxx 50: sector map
Today’s Euro Stoxx 50 structure shows a broad-based rebound, with gains concentrated mainly in financials, industrials and parts of the technology sector. Banks are performing strongly, while among the major technology components, ASML and SAP are both higher, helping the index maintain positive momentum despite weaker performance from some semiconductor names. The industrial sector is also performing relatively well, supported by Airbus and Rheinmetall, while weakness remains visible in parts of health care and utilities. Overall, the map suggests that the rebound is relatively broad and is not being driven solely by a handful of the largest companies.
Source: XTB
Euro Stoxx 50: strongest and weakest stocks
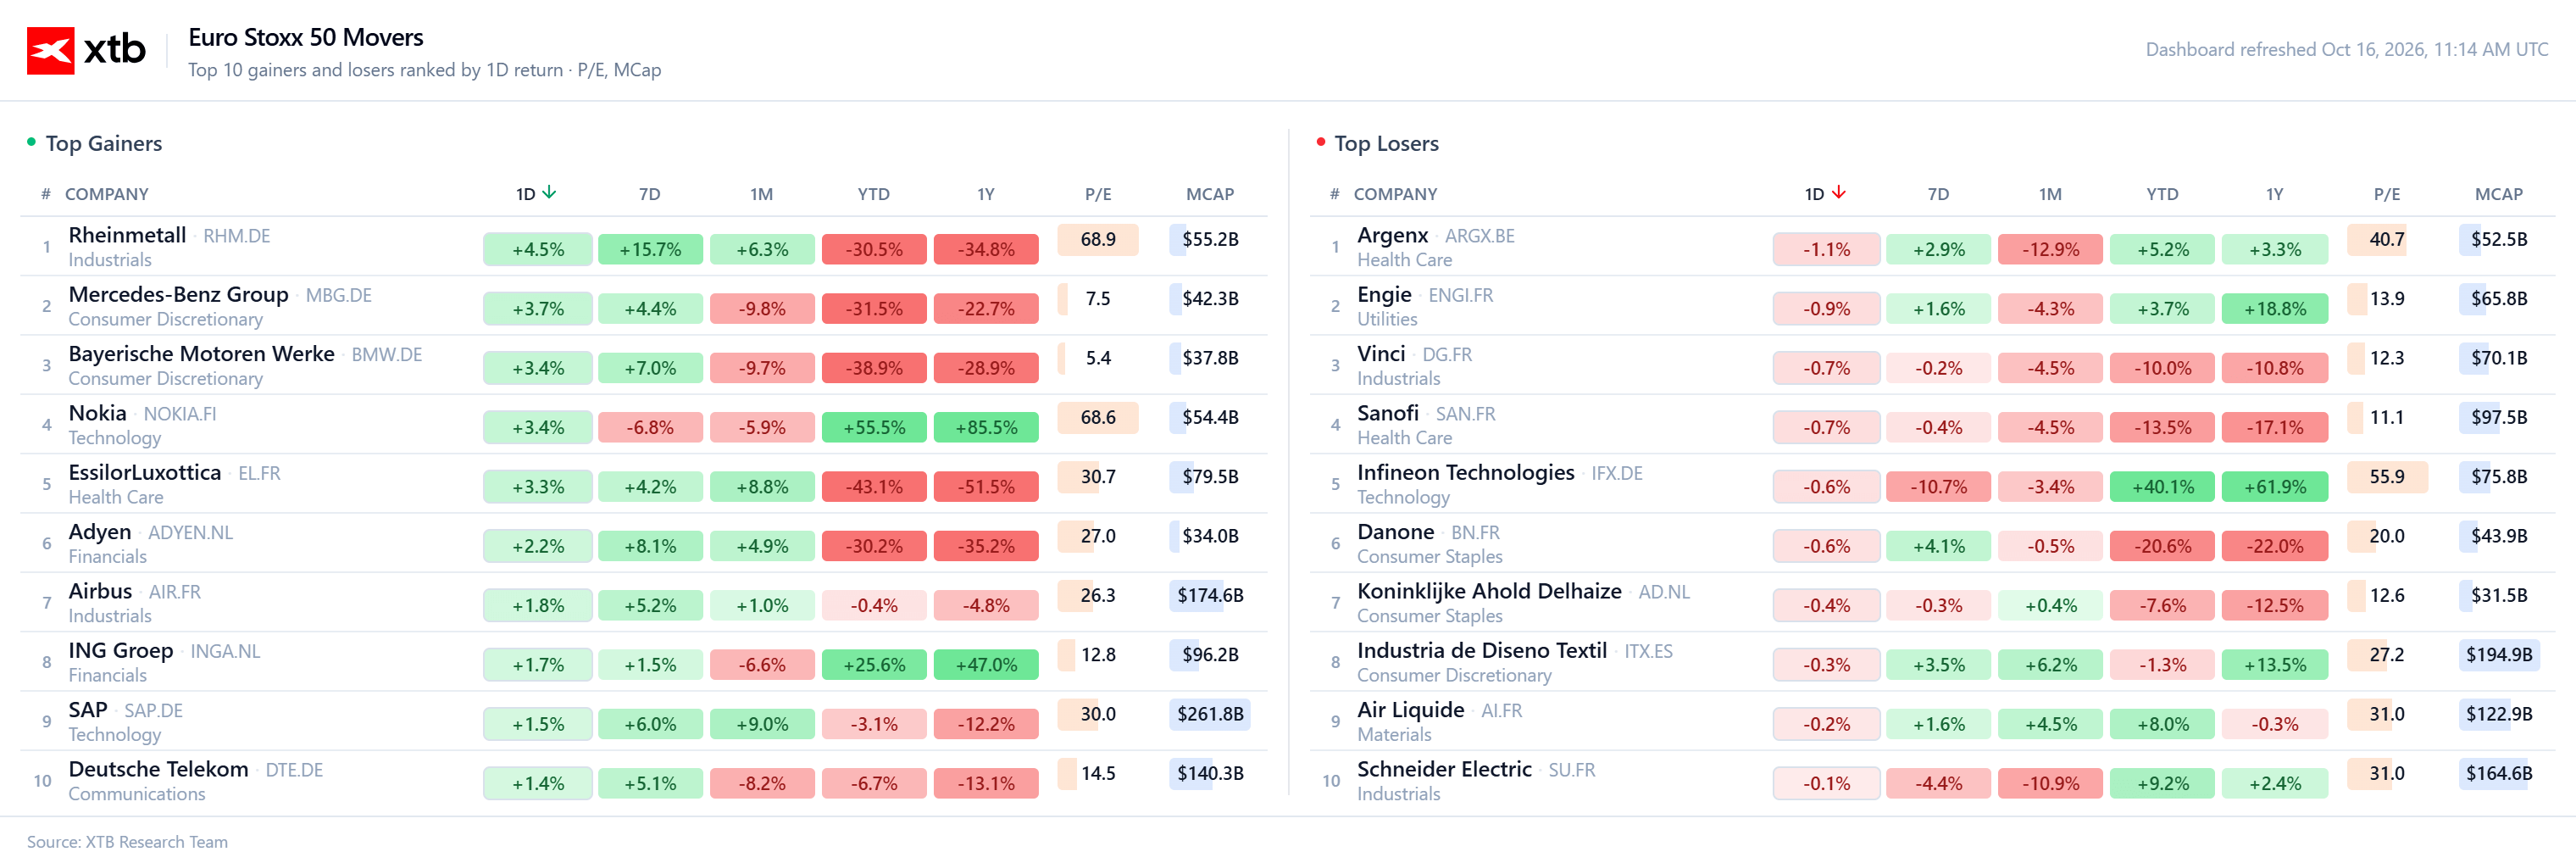
Rheinmetall is leading today’s gains, rising around 4.5%, while Mercedes-Benz (+3.7%), BMW (+3.4%), Nokia (+3.4%) and EssilorLuxottica (+3.3%) are also posting strong rebounds. It is worth noting, however, that some of today’s strongest performers remain clearly negative on a year-to-date basis, suggesting that the move is more consistent with a short-term recovery than a full reversal of earlier weakness. On the downside, moves are significantly smaller — Argenx is down 1.1%, Engie 0.9%, while Vinci and Sanofi are each lower by around 0.7%, confirming the broader dominance of buyers across the index. The structure of the session therefore points to a rotation of capital toward previously oversold cyclical and industrial stocks, while selling pressure among the biggest laggards remains relatively limited.
 Source: XTB


🔼 EURUSD continues to rebound


TSMC in Talks with Elon Musk Over Terafab


Chart of the Day: NATGAS - Are there chances for a seasonal rebound amid warm weather?

Daily summary 📈 Precious metals and stock indices rebound as Treasury yields fall