


14.10.2026 - US CPI [September]
- CPI Y/Y: 3,7% (Expected: 3,6%; Previously: 3,4%)
- CPI M/M: 0,6% (Expected: 0,6; Previously: 0,4%)
- Core CPI y/y: 2,6% (Expected: 2,5%; Previously: 2,4%)
- Core CPI m/m: 0,3% (Expected: 0,2%; Previously: 0,3%)
September’s US CPI report delivered a modest but important hawkish surprise, with headline inflation accelerating to 3.7% YoY, above the 3.6% consensus and up from 3.4% in August.
More importantly, core inflation rose to 2.6% YoY, exceeding forecasts of 2.5%, while the monthly core reading of 0.3% also came in above expectations.
The data suggest that disinflationary momentum remains fragile, with underlying price pressures proving more persistent than anticipated.
The report reinforces concerns that inflation could remain above the Federal Reserve’s target for longer. This potentially strengthens the case for a more cautious monetary policy stance, increasing the lieklyhood of continous hikes even more.
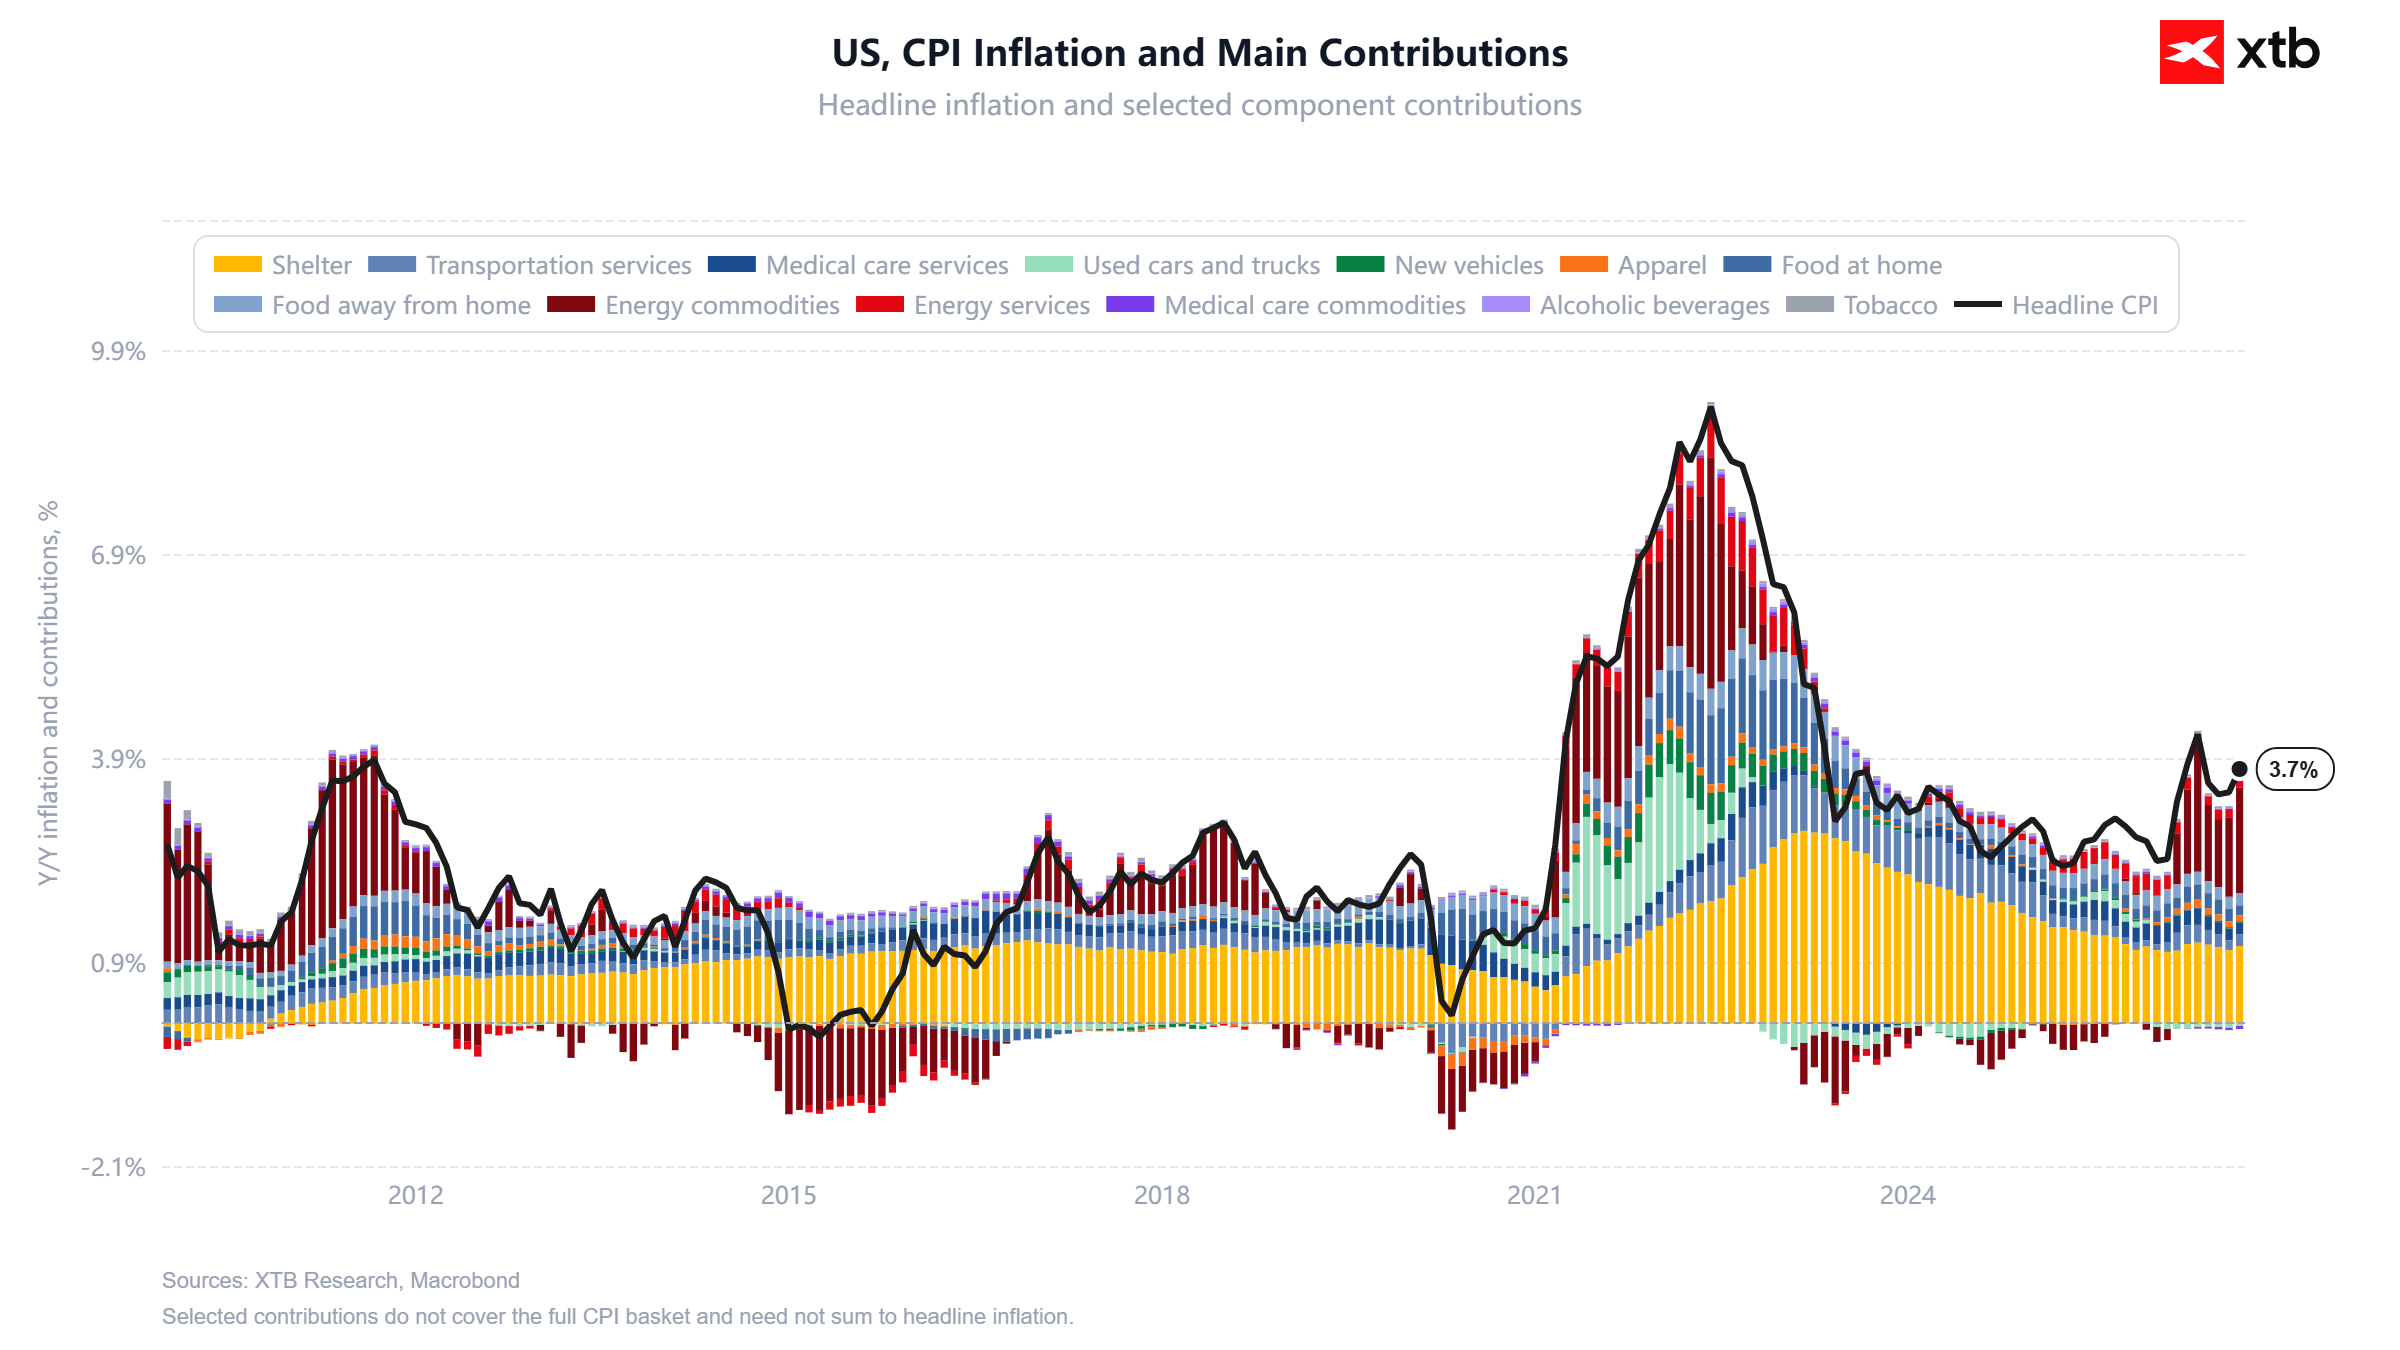
As expected, almost entierty of up-side Inflation contribution (CPI-U) was limited to Fuel and Energy Costs, contributing aprox. 9% and 15% price increase respectivly.
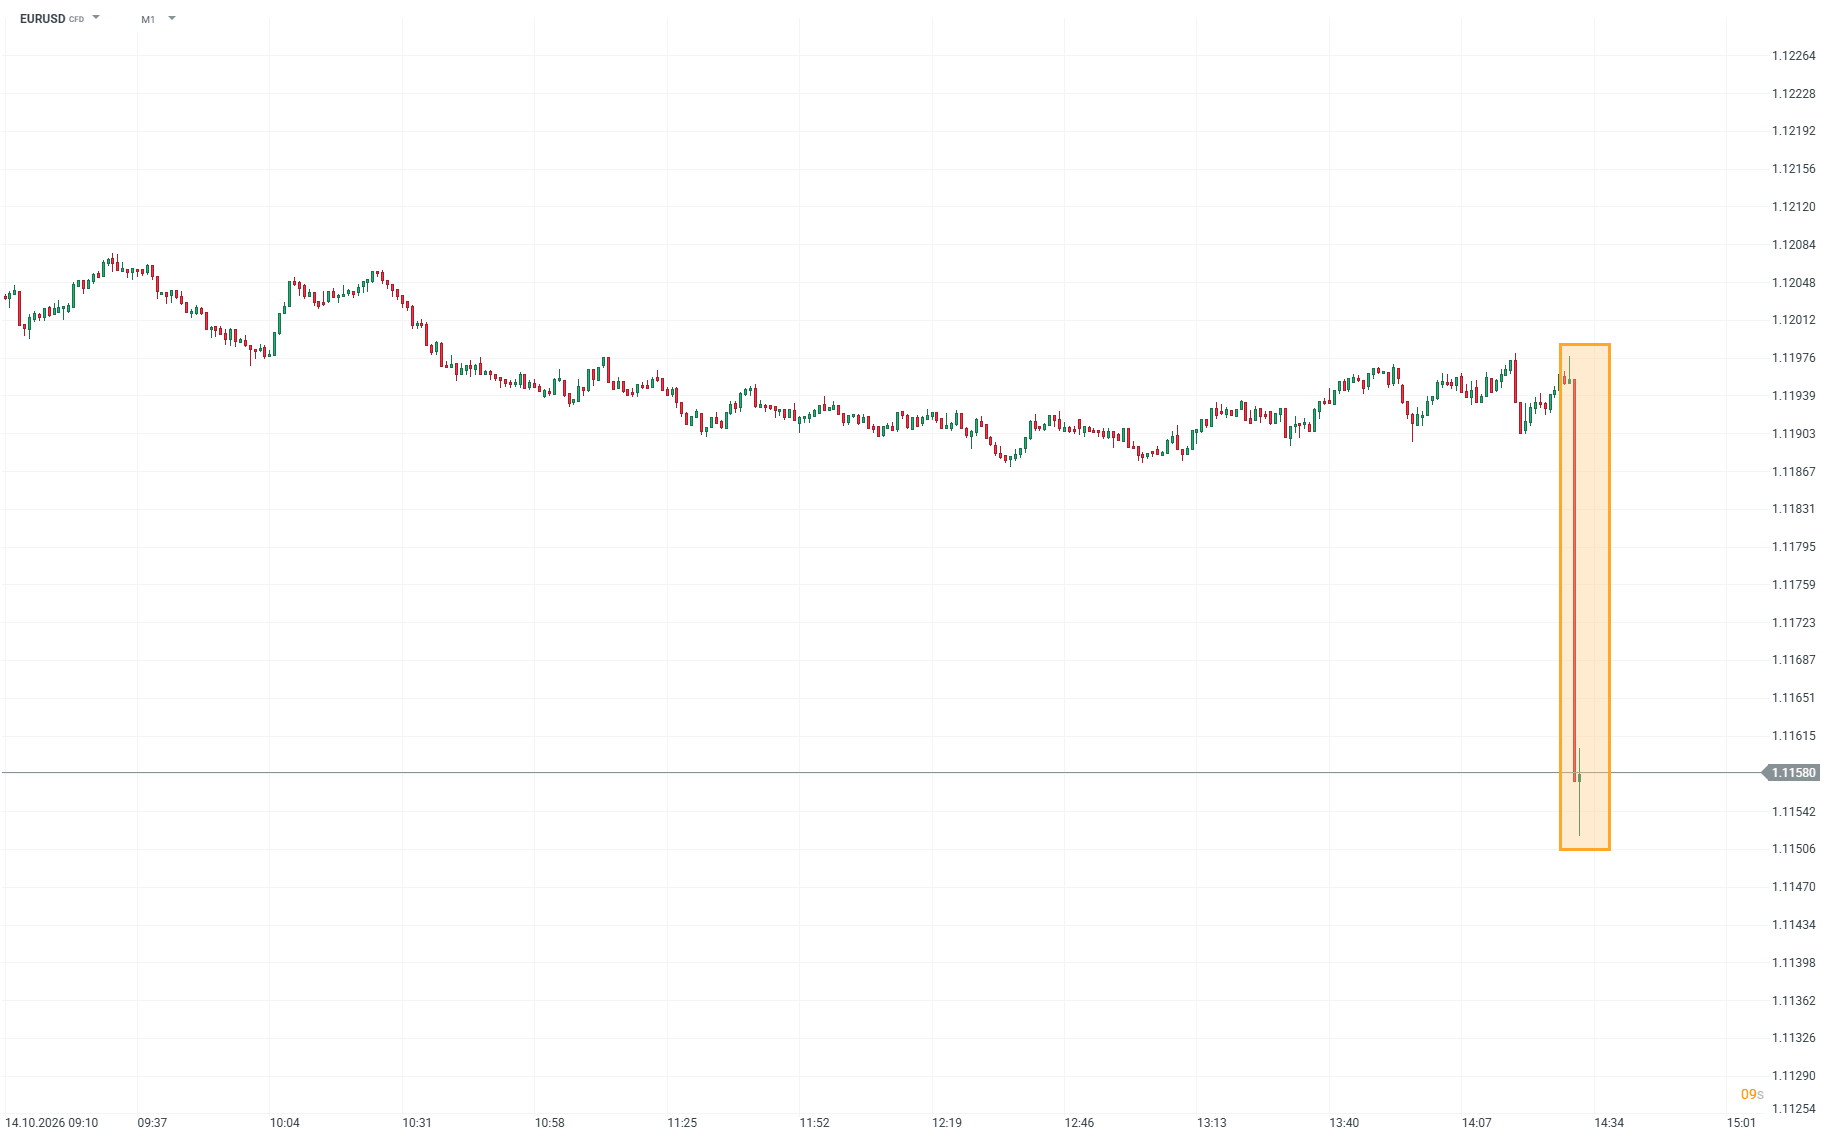
US Dollar experiances powerful apprciation after the publication. US Indices change direction and turn negative.
EURUSD (M1)


Market Wrap: ASML lifts tech sentiment, EU yields pull back


Dollar in Limbo Ahead of CPI 🚨


Economic Calendar: US CPI Inflation Data in Focus (14.10.2026)
Chart of the Day 📈 EURUSD attempts to rebound ahead of US inflation data (14.10.2026)