This article explains how to calculate net worth by subtracting total liabilities from total assets. It explores the key components of net worth, provides a simple calculation method, and highlights the importance of tracking net worth to monitor financial progress and make informed financial decisions.
This article explains how to calculate net worth by subtracting total liabilities from total assets. It explores the key components of net worth, provides a simple calculation method, and highlights the importance of tracking net worth to monitor financial progress and make informed financial decisions.
Net worth is the total value of everything you own minus everything you owe. The net worth formula requires subtracting your total liabilities from your total assets. Knowing how to calculate your net worth provides a clear picture of your financial health and guides your future financial decisions. This guide will show you exactly what to include and how to calculate your personal net worth step by step.
Key Takeaways:
-
The net worth formula is simple: assets minus liabilities. Tracking your net worth regularly helps measure long-term financial progress.
- Your assets include cash, investments, real estate, and retirement accounts.
- Your liabilities include all debts, such as mortgages, student loans, and credit card balances.
- A negative net worth means your debts exceed your assets, which is a common starting point for many young people.
What is net worth?
Net worth is the value of everything you own (assets) minus everything you owe (liabilities). This metric functions much like a personal balance sheet explained in plain terms, revealing your exact financial standing at a specific point in time. Individuals calculate net worth to track financial progress, prepare for retirement, or evaluate their overall economic stability.
The meaning of net worth goes beyond just your monthly income; it reflects the wealth you actually retain. What does net worth mean in practice? It's the amount of cash you would be left with if you sold all your assets and paid off all your debts at the same time. According to financial institutions, this comprehensive view prevents people from confusing high income with actual wealth accumulation.
A high salary does not guarantee a high net worth if your spending matches or exceeds that income. Consistently monitoring your personal net worth helps you understand if your daily financial habits are successfully building long-term security.
What is the net worth formula?
The net worth formula is your total assets minus your total liabilities (Net Worth = Assets - Liabilities). This equation underlies most personal finance and wealth-tracking calculations. Applying this formula correctly requires listing the current market value of all your assets and the exact payoff amounts of all your liabilities.
Net Worth = Assets - Liabilities
The result of this calculation falls into one of three categories: positive, negative, or zero. A positive net worth indicates that your assets hold more value than your debt obligations. Conversely, a negative result means your total debt currently exceeds the total value of your assets.
How do you calculate your net worth step by step?
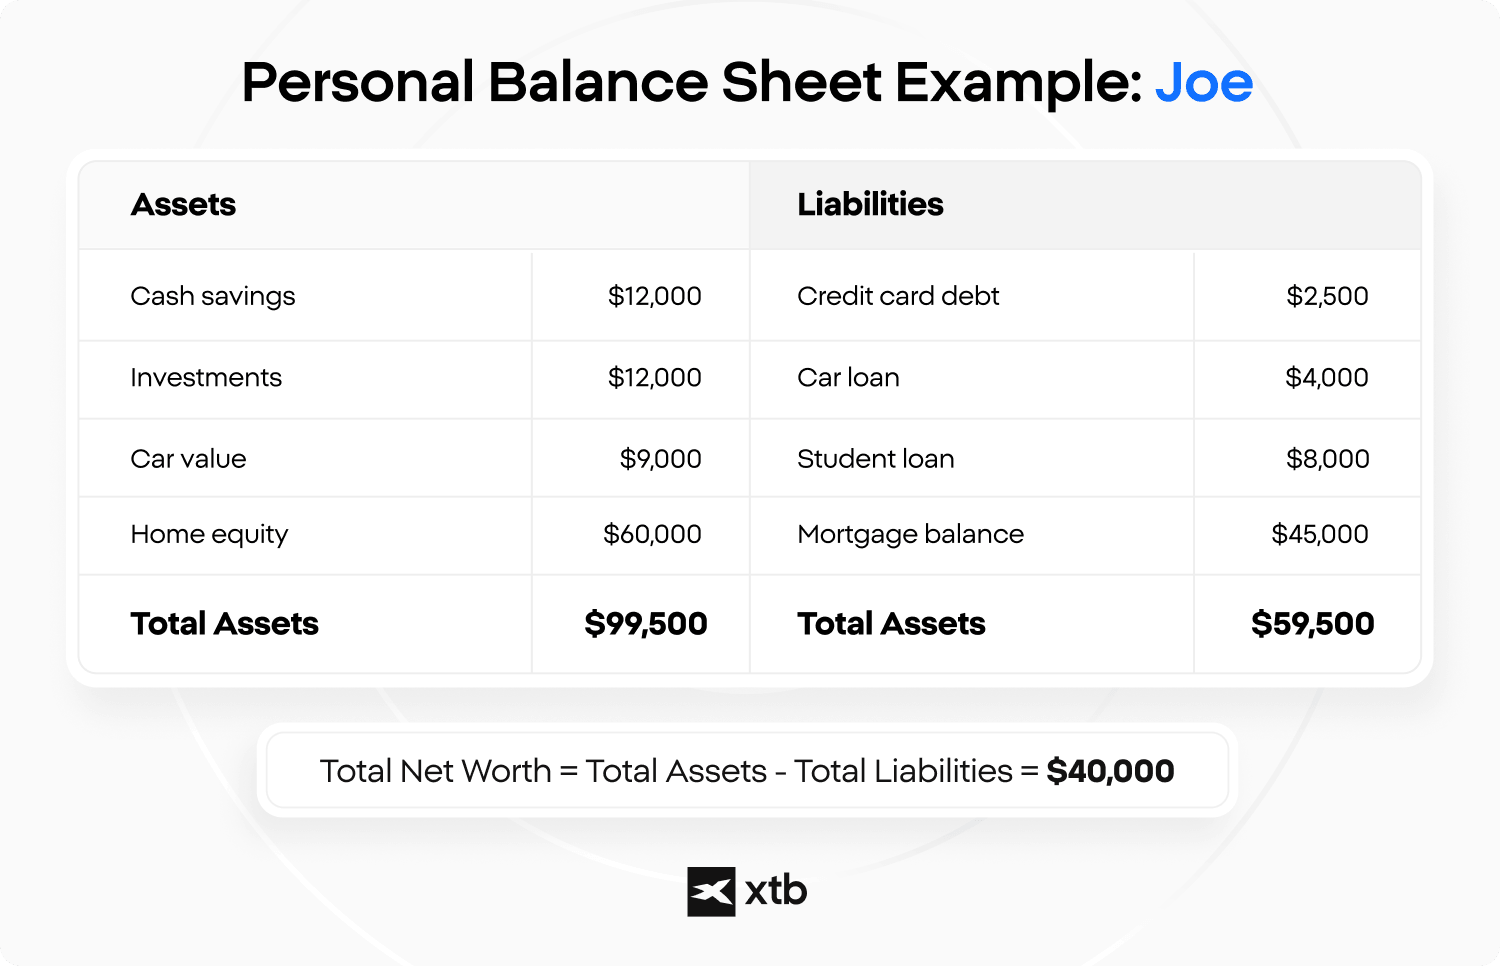
You calculate your net worth in three steps: sum up all your assets, sum up all your liabilities, and then subtract the liabilities from the assets. Gathering accurate, up-to-date statements for all your financial accounts ensures your calculation reflects reality. Knowing how to calculate your net worth correctly prevents financial blind spots and gives you full control over your wealth-building strategy.
To determine your exact financial standing, follow these fundamental steps to complete your personal balance sheet:
- List and value your assets: Gather current statements for your bank accounts, investment portfolios, and appraisals for physical property.
- List and value your liabilities: Record the exact payoff balances for every loan, mortgage, and line of credit you currently owe.
- Subtract your liabilities from your assets: Apply the net worth formula by deducting your total debt from your total assets.
- Review and update regularly: Revisit these calculations annually or quarterly to track your financial trajectory over time.
What counts as assets?
Assets include everything with monetary value: cash, savings accounts, investments, retirement accounts, real estate, and valuable personal property. When calculating what you own, using accurate, up-to-date values is essential to determining your true net worth. Does a retirement savings account count as net worth? Yes, retirement accounts and other investment plans are core components of your financial assets. Financial and tax authorities classify these as assets because they hold realizable monetary value, even if you cannot access them penalty-free until retirement.
Assets generally fall into liquid and illiquid categories, or "liquid net worth" versus illiquid net worth. Liquid assets, or your liquid net worth, include cash and standard brokerage accounts that you can convert to cash quickly without losing value. Illiquid assets include real estate or long-term business equity, which take more time and effort to sell on the open market.
When building your personal balance sheet, categorize your assets to ensure you do not miss any valuable holdings:
- Cash and cash equivalents: Checking accounts, savings accounts, emergency funds, and physical cash.
- Investments: Stocks, bonds, mutual funds, and exchange-traded funds (ETFs) held in taxable brokerage accounts.
- Retirement accounts: Your retirement savings accounts and the vested value of any pensions.
- Real estate and property: The current market value of your primary residence, investment properties, and vehicles.
\What counts as liabilities?
Liabilities include all outstanding debts: mortgages, student loans, car loans, credit card balances, and personal loans. A liability is any money you owe to another person or institution. Recording the exact payoff balance, not the original loan amount or your monthly payment, is essential for an accurate net worth calculation.
Liabilities directly reduce your overall wealth in the net worth formula. While some debts, like a mortgage, are tied to appreciating assets (like real estate), others, such as high-interest consumer debt, drain financial resources without building any underlying value.
To ensure accuracy when deducting what you owe, include these common liability categories:
- Mortgages: The total remaining principal balance on your primary home and any investment property loans.
- Student loans: All outstanding federal and private educational debt.
- Vehicle loans: The exact payoff amount for cars, boats, or other financed vehicles.
- Credit card debt: The current revolving balances on all your credit cards, regardless of the interest rate.
What should you not include when calculating net worth?
You should not include income, unused credit, or expected future earnings when calculating net worth. Net worth measures the value of what you currently own minus what you currently owe, not money you may receive later.
You should also avoid using outdated or unrealistic asset values, as this can overstate your financial position. Include only assets and liabilities that can be reasonably valued at the time of calculation.
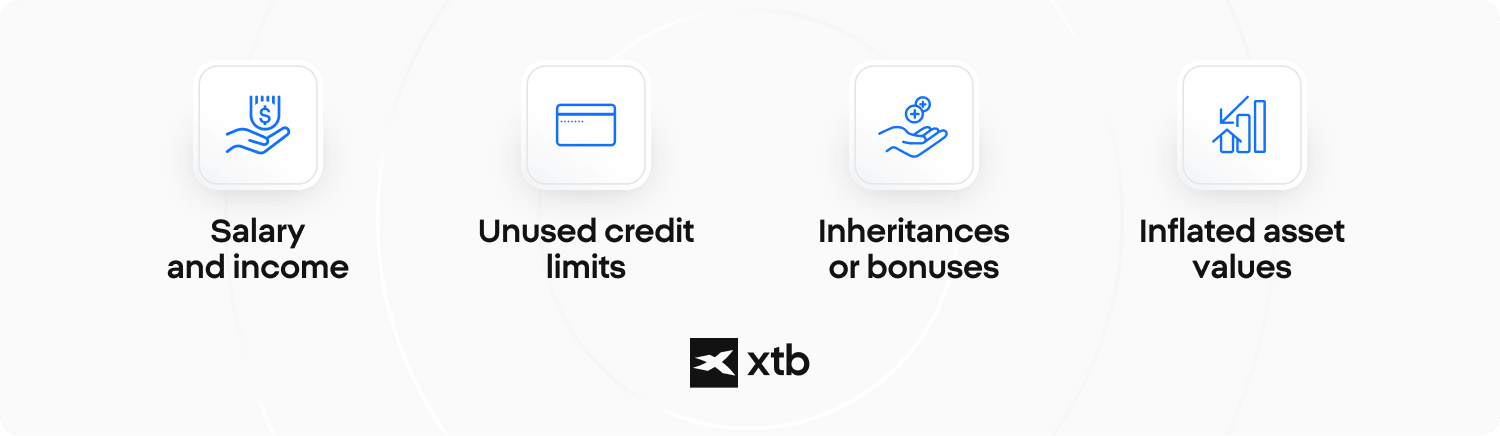
Common items to exclude include:
- Salary and future income: These are cash flows, not existing assets.
- Unused credit limits: Available credit is not your money.
- Expected inheritances or bonuses: Future payments are uncertain until received.
- Inflated asset values: Use realistic current market values rather than original purchase prices.
What does your net worth tell you, and how can you grow it?
Your net worth reveals your financial health at a specific moment, and you grow it by either increasing your assets or reducing your liabilities. Understanding how to calculate your net worth gives you a baseline for lifelong financial planning. Many people ask, "what should my net worth be at 40?" According to government banking statistics, the median net worth for households in their late 30s to early 40s is roughly $135,000. However, personal benchmarks depend entirely on your individual lifestyle and retirement goals.
A growing net worth often requires a strategy that goes beyond simply knowing how to save money. Over time, acquiring assets that appreciate, such as stocks or real estate, can significantly boost your overall wealth. Understanding what compound interest is helps explain how these long-term investments grow exponentially over decades.
Keep in mind that when relying on financial markets to build wealth, past performance does not guarantee future results. If you are ready to expand your asset column and take a more active role in your wealth generation, learning how to invest for beginners provides the foundational knowledge needed to navigate the markets responsibly.
FAQ
To calculate your net worth, add the current value of all your assets and subtract the total amount of your liabilities. The formula is: Net Worth = Total Assets - Total Liabilities.
Net worth includes assets you currently own, such as cash, investments, retirement accounts, real estate, vehicles, and other property with measurable value. It also includes liabilities such as mortgages, student loans, car loans, credit card debt, and personal loans.
Yes. Your home's current market value can be included as an asset, while the outstanding mortgage balance is included separately as a liability. The difference between the two contributes to your overall net worth.
Yes, a car can count as an asset when calculating net worth because it has a measurable resale value. Use a realistic current market value rather than the original purchase price, and record any remaining car loan as a liability.
A negative net worth means your liabilities are greater than the total value of your assets. This can occur when someone has large student loans, a mortgage, or other debts before accumulating substantial savings and investments.
No. Salary and other future income are not included directly in net worth because income is money you earn over a period of time, while net worth measures the assets and liabilities you have at a specific point in time. Income may affect net worth later if it is saved, invested, or used to reduce debt.
You should generally exclude future salary, unused credit limits, expected inheritances, and other money you do not currently own. You should also avoid using unrealistic or outdated valuations for assets, as this can overstate your financial position.
There is no single required schedule, but recalculating your net worth periodically helps you track changes in assets and debt. Quarterly or annual reviews can provide a useful long-term view, while some people may prefer more frequent updates when actively saving or paying down debt.
Calculating your net worth gives you a snapshot of your overall financial position by combining what you own and what you owe in one figure. Tracking that figure over time can help show whether your assets are growing, your liabilities are declining, or your overall financial position is changing.