Understand financial leverage, how to calculate it from a balance sheet, and whether it indicates efficient financing or excessive risk.
Understand financial leverage, how to calculate it from a balance sheet, and whether it indicates efficient financing or excessive risk.
Financial leverage is the strategic use of borrowed funds (debt) alongside shareholder equity to finance assets, aiming to multiply potential financial returns on corporate capital. Publicly traded companies across major global stock indices maintain average leverage ratios ranging from 2.0x to 3.5x or more. While borrowing increases total corporate purchasing power and corporate expansion capacity, fixed financial obligations simultaneously amplify losses when asset returns fall short of financing costs. Understanding this corporate balance sheet mechanism allows investors to assess solvency risk, capital efficiency, and earnings stability across different economic cycles.
Key Takeaways
-
Financial leverage uses borrowed capital (debt) to finance corporate assets and boost returns on shareholder equity.
- The financial leverage ratio measures total assets relative to shareholder equity on a corporate balance sheet.
- Borrowed capital acts as a symmetrical amplifier, magnifying positive returns during growth phases and deepening net losses during market downturns.
- Corporate balance sheet leverage is fundamentally distinct from margin borrowing used in leverage trading.
What is financial leverage?
Financial leverage is the use of debt (borrowed capital) to finance a company's assets in order to increase potential returns on equity. In corporate finance, leverage operates much like a physical lever, where a small amount of equity capital controls a significantly larger asset base. When corporate managers build a capital structure, they choose between issuing new equity shares or taking on corporate debt obligations. Using debt avoids diluting existing ownership, allowing equity holders to capture all profits generated above the fixed cost of borrowing.
Corporate financial leverage on a firm's balance sheet must not be confused with broker-provided margin in retail trading. In financial markets, brokers grant short-term position leverage directly to trading accounts, multiplying temporary market exposure on specific financial contracts. In contrast, corporate financial leverage reflects long-term structural debt—such as corporate bonds, bank loans, or credit facilities—issued by a corporation to fund plant expansions, acquisitions, or research projects. To explore retail trading mechanisms, review the guide on leverage trading.
It is equally important to distinguish corporate financial leverage from operating leverage. While operating leverage measures how fixed operating costs (such as factory rent and equipment depreciation) affect operating profit, corporate financial leverage arises strictly from fixed financing costs, specifically annual debt interest charges.
How does financial leverage work?
Debt magnifies both gains and losses on equity - the higher the leverage, the greater the amplification in both directions. When a business finances its operations using borrowed funds, it incurs a fixed financing cost in the form of regular interest payments. Because these interest payments remain constant regardless of how much operating revenue the firm generates, any increase in operating income flows directly to the bottom line, boosting net income and expanding the overall return on equity (ROE).
Corporate management teams deliberately employ financial leverage to increase shareholder value when the expected return on invested capital exceeds the cost of debt. When a company earns a 10% return on assets funded by debt carrying a 5% interest rate, the residual 5% spread accrues entirely to shareholders. This mechanism allows a firm with moderate operational growth to deliver accelerated equity gains.
However, this financial mechanism is perfectly symmetrical. If operational earnings drop or asset yields fall below the fixed interest rate, the firm must still satisfy its contractual debt service demands. The fixed interest payments absorb a larger percentage of declining revenues, rapidly eroding net income and resulting in magnified losses for equity investors.
How do you calculate financial leverage?
The most common financial leverage ratio is the ratio of total assets to equity (or debt to equity), calculated directly from the balance sheet. The primary metric used by financial analysts is the equity multiplier variant, which expresses how many dollars of total assets are controlled by each dollar of shareholder equity. The mathematical formula is expressed as:
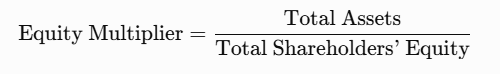
Alternatively, analysts frequently evaluate leverage using the debt-to-equity ratio, which compares total debt liabilities directly against shareholder equity.
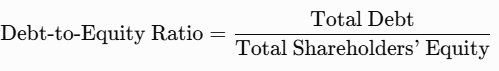
Both metrics express balance sheet leverage as a numerical multiplier (e.g., 2.5x) rather than a percentage figure. Detailed step-by-step instructions on locating these balance sheet line items are covered in how to read a balance sheet.
For instance, evaluating the published financial statements of Apple Inc. for fiscal year 2024 shows total reported assets of $364.98 billion against total shareholders' equity of $56.95 billion. Dividing total assets by equity yields an equity multiplier of approximately 6.41x.
To perform a complete financial leverage assessment on a corporate report, extract the following core financial metrics:
- Total assets representing the sum of current and non-current balance sheet holdings.
- Total equity representing residual shareholder ownership value after deducting liabilities.
- Total debt combining short-term obligations and long-term borrowing commitments.
- Interest charges itemized within the income statement to calculate annual coverage obligations.
Understanding these balance sheet inputs allows investors to calculate the standard debt-to-equity ratio and gauge overall capital structure stability.
What is the degree of financial leverage (DFL)?
Degree of financial leverage (DFL) measures the sensitivity of a company's earnings per share (EPS) to changes in operating income (EBIT). Specifically, it shows the percentage change in EPS resulting from a 1% change in EBIT. Unlike traditional balance sheet leverage ratios, which provide a static view of a company's debt position, DFL captures how fixed financing costs amplify the effect of changes in operating performance on shareholders' earnings.
The general definition of the degree of financial leverage is:
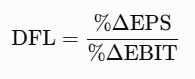
At a specific level of operating income, DFL is commonly calculated using EBIT and interest expense:
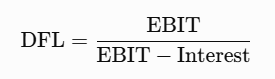
This simplified formula assumes the company has no preferred dividends and ignores the effects of taxes. More comprehensive versions may incorporate both when applicable.
A higher DFL indicates greater sensitivity of earnings to changes in operating profit. For example, if a company has a DFL of 2.0, a 10% increase in EBIT would be expected to result in an approximately 20% increase in EPS. Conversely, a 10% decline in EBIT would lead to an approximately 20% decrease in EPS, assuming all other factors remain unchanged.
A company with no interest-bearing debt has a DFL of 1.0, meaning that EPS changes proportionally with EBIT because there are no fixed financing costs to magnify changes in operating earnings.
Is financial leverage good or bad?
Financial leverage is not inherently good or bad — its evaluation depends on its level, company revenue stability, and industry benchmarks. When used prudently, borrowing allows efficient companies to fund capital projects, accelerate growth, and generate higher return on equity (ROE) without issuing dilutive shares. Furthermore, in many tax jurisdictions, corporate debt interest payments are tax-deductible, creating a corporate tax shield that reduces the effective cost of capital.
However, elevated debt levels increase long-term corporate risks. Excessive leverage leaves companies vulnerable during economic recessions, as fixed debt service costs must be paid even if revenues decline sharply. High debt levels can lead to credit downgrades, elevated interest rates on debt refinancing, or corporate bankruptcy. When conducting comprehensive valuation assessments, investors combine leverage metrics with tools like the P/E ratio and broader fundamental analysis frameworks.
Determining whether a specific financial leverage ratio is safe requires analyzing industry sector benchmarks:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Summary Overview
Evaluating corporate financial leverage requires balancing capital efficiency against financial solvency risk. When a firm generates returns on capital higher than its cost of debt, leverage effectively multiplies equity returns. However, because fixed debt burdens persist through all economic conditions, monitoring financial leverage ratios and interest coverage helps investors identify businesses with sustainable capital structures.
FAQ
FAQ
Financial leverage is the use of borrowed money (debt) to finance a company's assets instead of relying only on shareholders' equity. If the company earns a higher return on its investments than the cost of borrowing, leverage can increase shareholder returns. However, if profits decline, debt magnifies losses just as quickly.
The most common financial leverage ratio is:
Financial Leverage = Total Assets ÷ Total Equity
For example, if a company has $500 million in assets and $200 million in shareholders' equity, its financial leverage ratio is 2.5x. Investors can calculate this directly from the balance sheet.
There is no universal "good" ratio because leverage varies by industry. Utilities and banks often operate with much higher leverage than software companies. Instead of comparing companies across different sectors, investors should compare leverage with direct competitors and the industry's historical average.
No. Moderate leverage can improve returns and help companies finance expansion without issuing new shares. Problems arise when debt becomes too large relative to cash flow, making it difficult to pay interest during economic downturns or periods of higher interest rates.
Financial leverage comes from borrowing money and paying interest on debt. Operating leverage comes from fixed operating costs such as factories, equipment, or rent. A company may have high operating leverage, high financial leverage, both, or neither.
Everything needed to calculate financial leverage is available in the balance sheet. Investors should review total assets, total liabilities, shareholders' equity, and total debt. Interest expense can then be found in the income statement to evaluate how easily the company can service its borrowings.
The Degree of Financial Leverage (DFL) measures how sensitive earnings per share (EPS) are to changes in operating profit (EBIT). A higher DFL means even a small change in operating income can produce a much larger change in shareholder earnings, making the company more financially sensitive.
Many successful businesses intentionally use debt because borrowing can be cheaper than issuing new shares. Debt also allows existing shareholders to avoid ownership dilution while potentially increasing return on equity, provided the company earns more than its financing costs.
Financial leverage influences a company's risk profile, earnings stability, return on equity, and ability to survive economic downturns. Companies with excessive debt often experience larger share price swings during recessions because investors become concerned about refinancing and solvency.
Corporate financial leverage refers to long-term borrowing used by companies to finance business operations and investments. Trading leverage is provided by a broker and allows traders to control larger market positions with a relatively small margin deposit. Although both amplify gains and losses, they operate in completely different contexts.