


The US Dollar Index (USDIDX) came out today at its highest levels in a fortnight. The broad-market appreciation of the world's reserve currency was directly attributable to incoming macro data from the US today, namely a higher-than-consensus reading for US GDP (2.0%; expected: 1.4%; prior: 1.3%) and private consumption (4.2%; expected: 3.8%; prior: 3.8%). These data, combined with lower unemployment claims (239,000; expected: 265,000; prior: 265,000), laid a very strong foundation for a narrative supporting further US rate rises.
As Jerome Powell said at an international conference in Sintra, Portugal, these hikes are expected by most Fed bankers to be two more, which was not in line with market predictions.
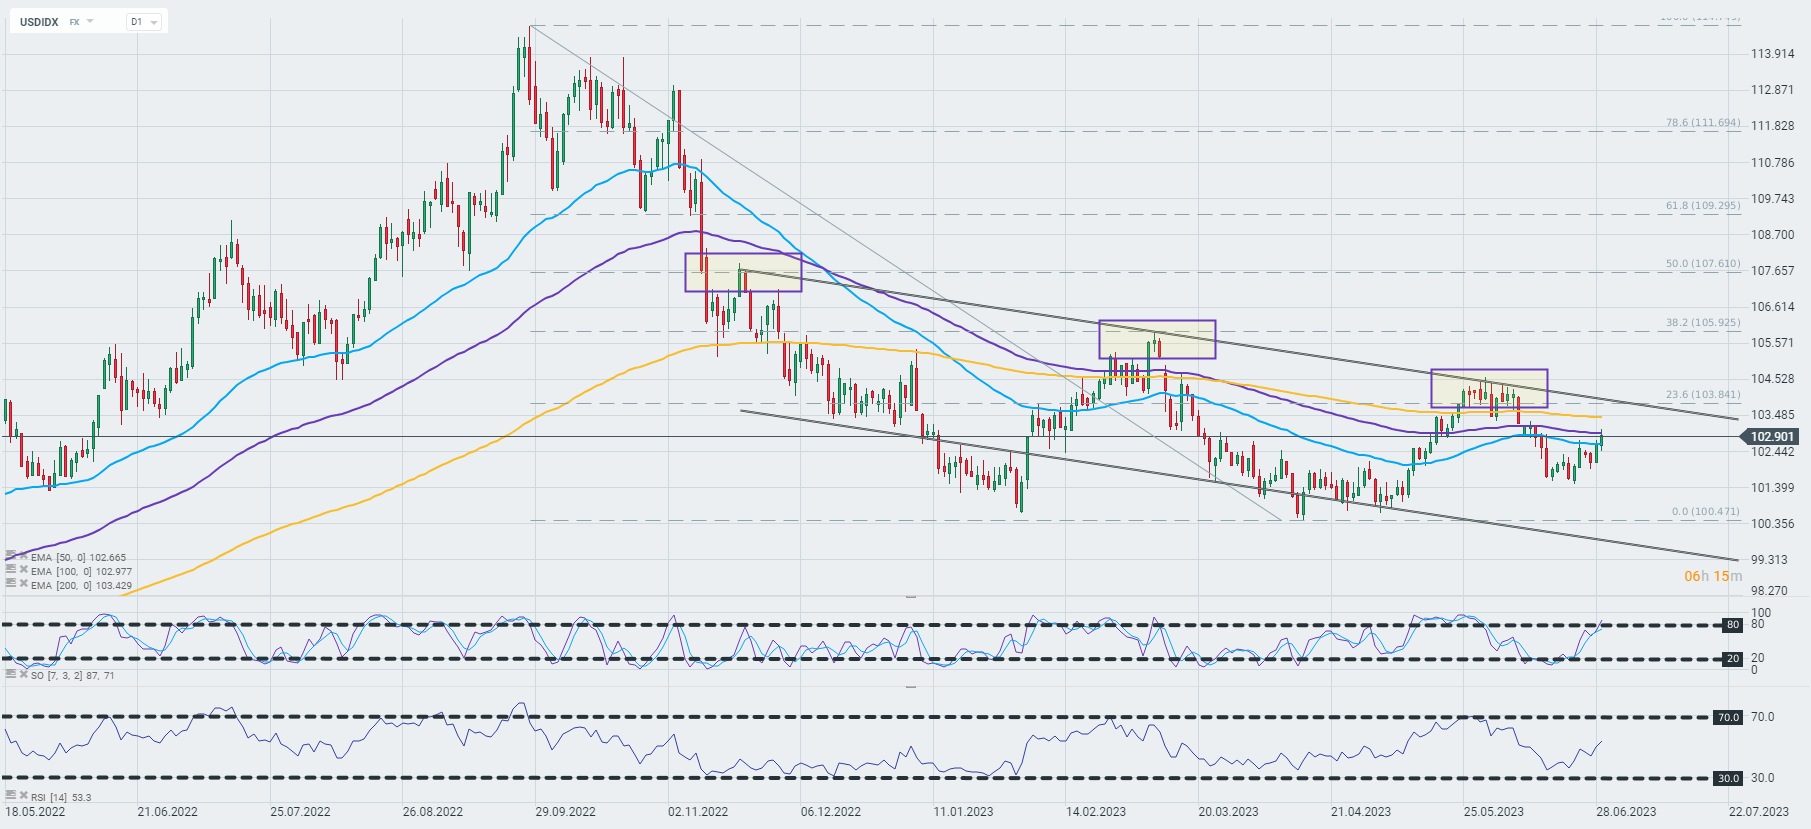 The USDIDX index price is currently testing the resistance set by the 100-day exponential moving average (purple curve on the chart). Source: xStation 5


🟢Morning Wrap: Lack of escalation lowers oil prices. Unexpected Lula victory hurts Brazilian stock market


Three markets to watch next week (23.10.2026)
BREAKING: France slows down, Germany holds on. Euro falls below 1.12
Chart of the Day: Is USDJPY running out of road? Inflation forces the BoJ to act, but the Fed could spoil the Yen’s rally