


Bank of Japan Governor Kuroda commented on Japan's monetary situation insisting on a dovish macro outlook although markets have recently seen a chance for a hawkish turn in BoJ policy. The yen weakened most since June 2022. At the same time, Japan's Trade and Industry Minister Yasutoshi Nishimura indicated that the country is approaching the point at which further monetary easing can be halted. The minister asked Japan's state-owned enterprises to raise wages by at least 5% this year. BoJ's real interest rate was kept at -0.100% level:
- BoJ Governor Kuroda indicated that real interest rates in Japan were falling, reinforcing the effect of monetary easing. Kuroda sees no problem with the bank's recent increased bond buying, and further negative interest rates remain likely;
- The governor continues that he sees no need to widen the yield range further, and does not expect 10-year bond yields to remain above 0.5%. Nevertheless, 4 days in a row their yields are above the 0.5% ceiling;
- According to the BoJ, Japan's economy is strengthening, and the bank 'will not hesitate to use more easing measures' if necessary. Governor Kuroda expects core inflation to fall in mid-2023;
- The bank will continue easing until prices rebalance, and will continue to conduct flexible market operations; in addition, it is expanding lending to banks to strengthen bonds;
- The BoJ's inflation forecasts for 2023 and 2024 have increased slightly although they remain well below 2% with next year being the year of greater concern for the bank. Chairman Kuroda is expected to step down in April, and it is uncertain whether his successor will share the dovish outlook of the current BoJ chief.
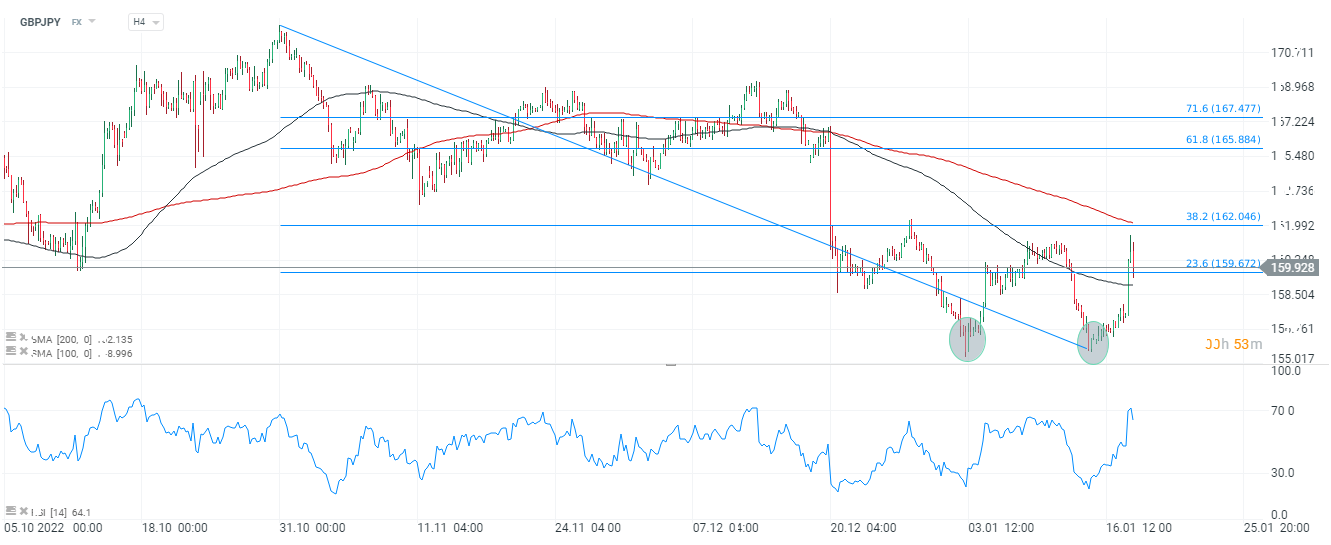 GBPJPY chart, H4 interval. Looking at the chart we can see the weakening of the yen, the price broke out a bullish double-bottom formation near 155 - 156 points. The upward movement weakened and now we see a correction, which stopped near the 23.6 Fibonacci retracement from where next upward impulse towards 162 points could potentially be launched. It is at these levels that the SMA200 (red line) runs, which coincides with the 38.2 Fibo abolition of the downward wave that began in October. These levels may provide further resistance for the bulls. Source: xStation5


Economic Calendar: จับตาตัวเลข GDP เบื้องต้นของยุโรป และเงินเฟ้อเยอรมนี

เศรษฐกิจสหรัฐฯ เติบโตแข็งแกร่ง ขณะที่เงินเฟ้อชะลอตัวลง
วันนี้ไม่มีปัจจัยบวกที่เอื้อต่อค่าเงินยูโรเลย


🎃รับโบนัสเพื่อเริ่มต้นเทรดในตลาดได้ทันที