


Silver has tested the area of $29 per ounce today after gold reached new historic highs above $2,400 per ounce. For precious metals, we are talking about a bull market driven by concerns over the situation in the Middle East. The United States indicated this week that there is a very high probability of a retaliatory attack by Iran against Israel, following an earlier attack on an Iranian diplomatic facility in Damascus, Syria. On the other hand, Iran itself has indicated that it will limit its retaliatory actions against Israel so as not to escalate an overly tense situation.
Silver found its highest since January 2021, when it tested the area around $30 per ounce. It's worth noting that on silver we very often see around $7-8 down and up waves. At the moment, such a range has been filled from the local low in February. On the other hand, in the medium term, seasonality continues to point to increases, while net speculative positions are still far from the extreme overbought of 2016 or 2019. It is also worth mentioning the recent inflows of funds into silver ETFs.
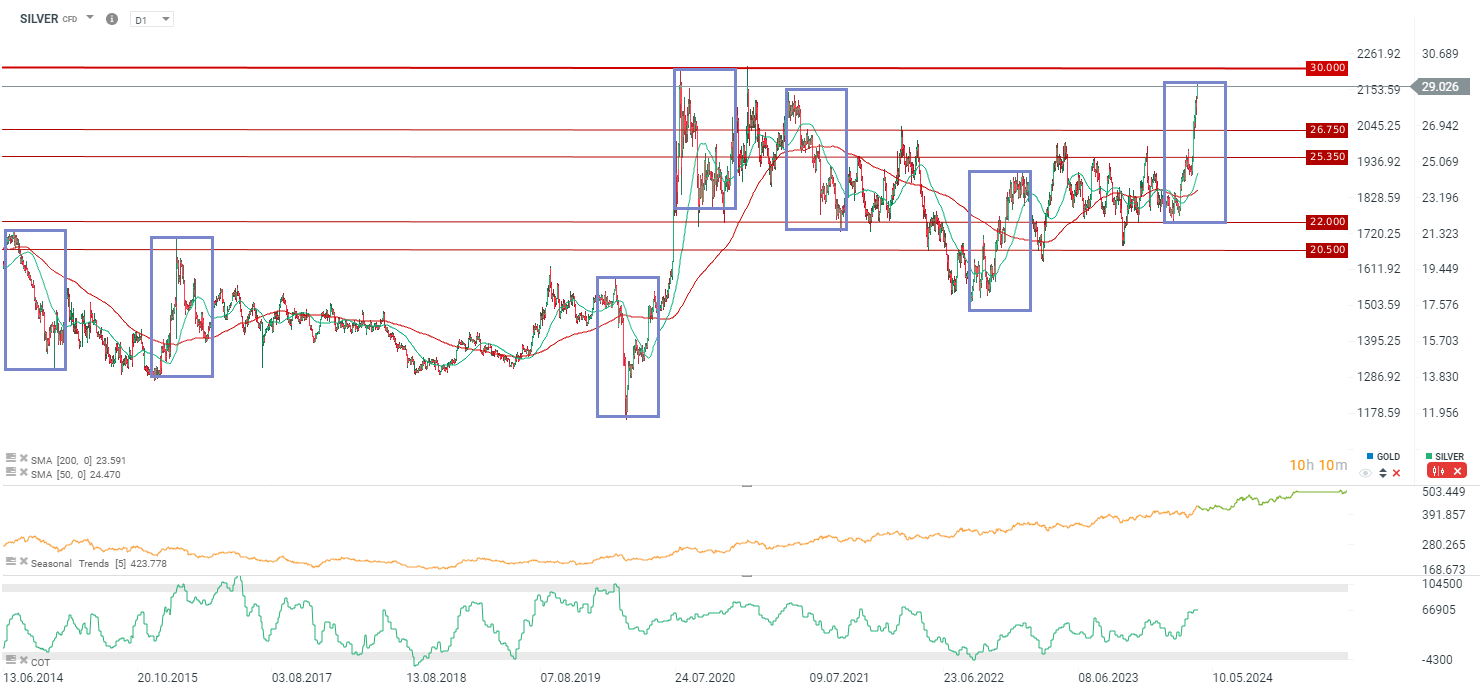
Source: xStation5
Analyzing the historical situation, it is worth noting that we may be experiencing a short-term overbought condition. We observe a 3.5 times standard deviation from the 100-session average, which seems extremely high, looking at the history of the last 20-25 years. In addition, we observe a 4.5 times standard deviation from the 1-year average, which has generated signals of short-term overboughtness over the past 20 years. At the same time, if we look at the deviation from the 5-year average, here it is far from extreme levels. In view of this, if there is no escalation of the conflict in the Middle East over the weekend, a gap down at the opening on Monday cannot be ruled out, but in the long term, gains are further possible, looking also at the fundamental situation, which suggests one of the largest deficits in the silver market in history.
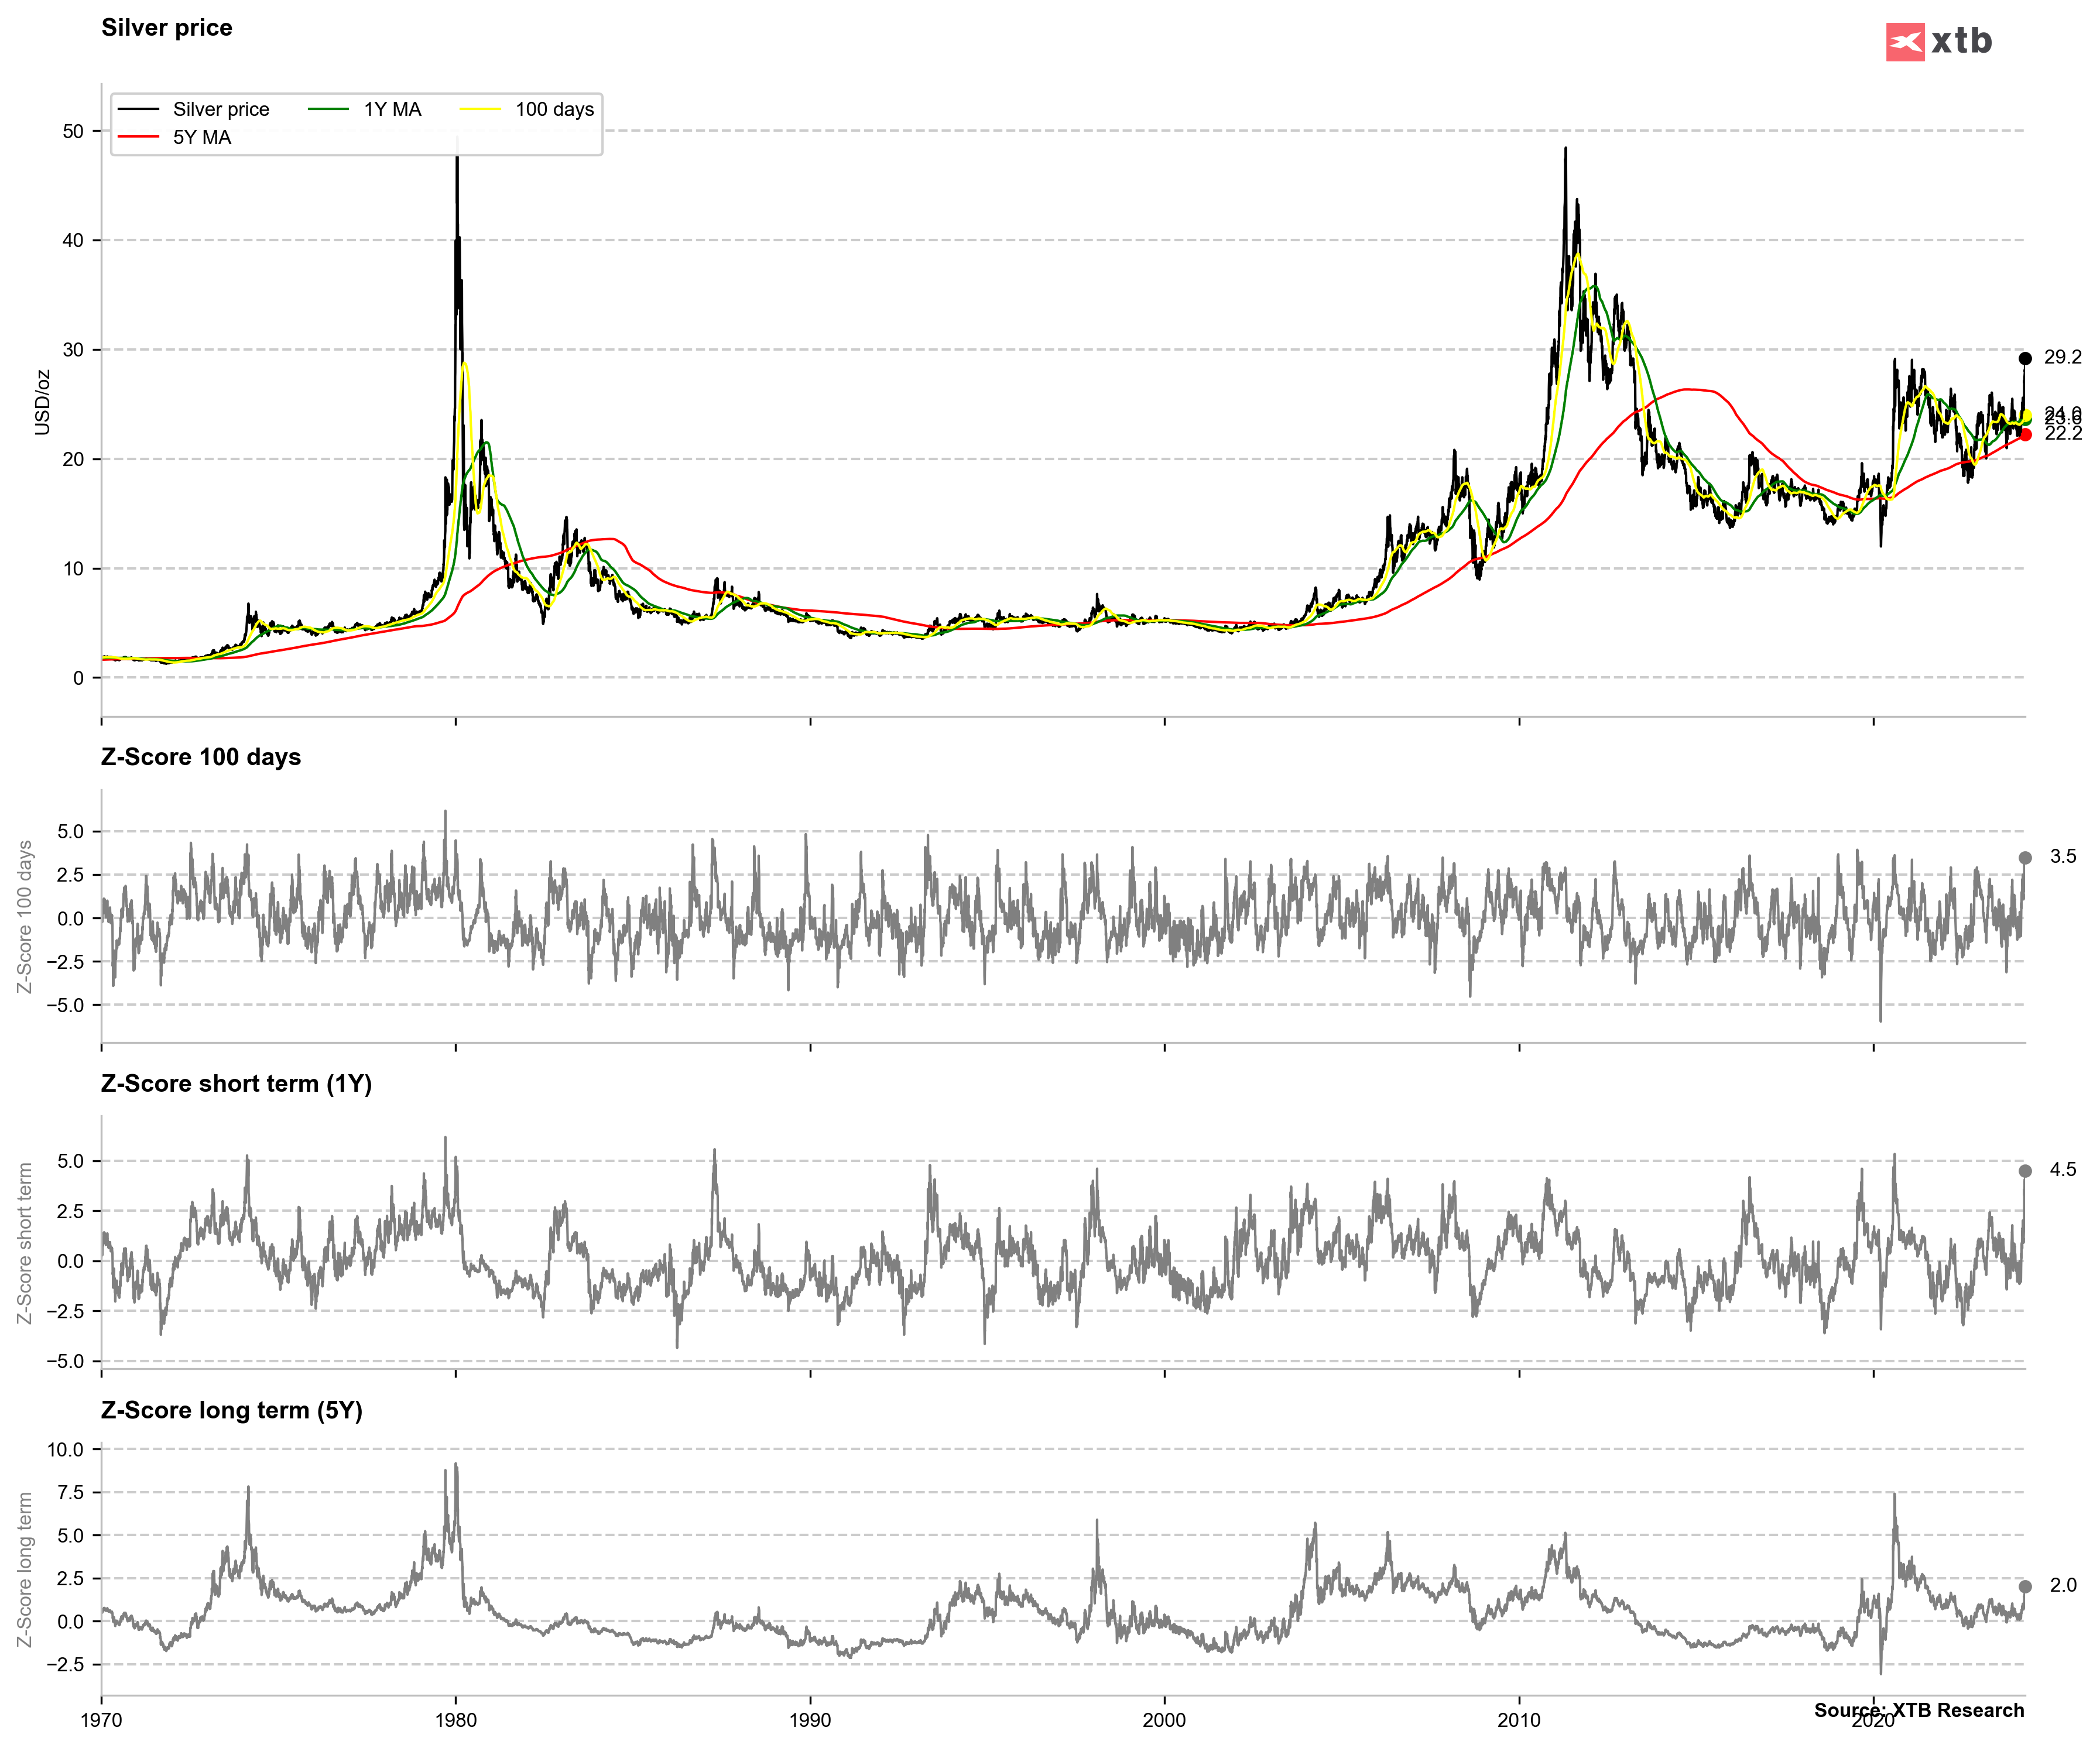
Source: Bloomberg Finance LP, XTB


Wall Street ร่วงหนักเป็นสีแดง
ECB เตือนความเสี่ยงฟองสบู่ AI จากกระแส IPO และหนี้มหาศาลของ Big Tech

ราคาทองคำร่วงลงหนึ่งในสาม ปัจจัยกดดันมาจากสภาพคล่องและ Fed ไม่ใช่สันติภาพในเซินเจิ้น

ราคาทองคำร่วงลง 2% แตะระดับ $3,550