00:04 · 2 āļĄāļĩāļ™āļēāļ„āļĄ 2024

Goolsbee speculated that January's CPI was an anomaly; see other comments from Fed bankers 🔎

Fed's Waller, Logan, and Goolsbee presented perspectives that collectively leaned towards a cautious approach to monetary policy adjustments, indicating a generally dovish stance. Overall, the bankers' remarks reflected a preference for a careful, measured approach to monetary policy, aligning more with dovish sentiments. Below are the highlights from each of the speeches:

Waller:

  • Emphasized that the pace of balance sheet reductions will be independent of policy rate changes.
  • Noted that the current overnight repo usage of around $500 billion indicates that the Fed can continue reducing its holdings for some time.
  • Expressed a preference for the Fed's Treasury holdings to shift towards a larger share of shorter-dated securities.

Logan:

  • Advised that moving more slowly in the current environment could reduce the risk of a premature stop in monetary policy adjustments.
  • Hasn't observed a reduction in reserves yet under the current Fed Quantitative Tightening (QT).
  • Pointed out that after draining the Overnight Reverse Repo (ON RRP), QT will reduce reserves on a one-for-one basis.

Goolsbee:

  • Stated uncertainty about where interest rates will settle.
  • Noted that if inflation continues to fall, the Fed should consider the impact on employment.
  • Believes the current Fed funds rate is quite restrictive.
  • Emphasized the need to monitor housing inflation.
  • Speculated that January's inflation might have been an anomaly.
  • Commented on the unusual nature of housing inflation.


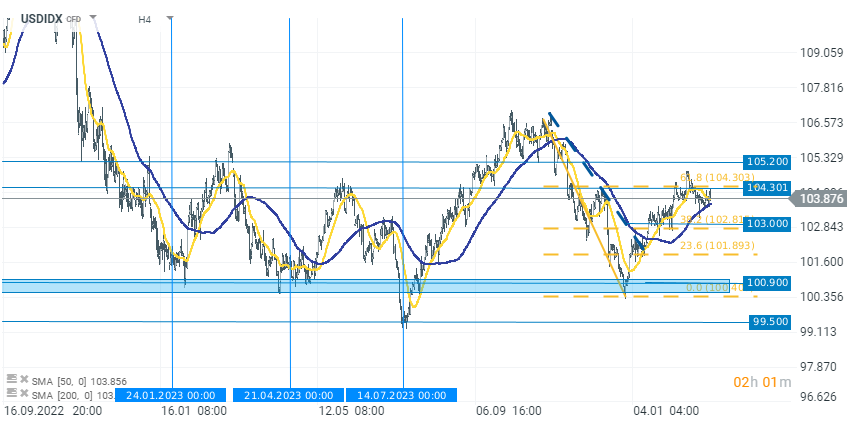
The US dollar index halted its rise at the 61.8% Fibonacci, retracement of its most recent downward move. Today, the USDIDX is losing almost 0.20%. The declines accelerated after the publication of the ISM data, which were significantly worse than expected and revived speculations about faster interest rate cuts.
Source: xStation 5
āļĢāļąāļš Welcome Bonus 10% āđ€āļĄāļ·āđˆāļ­āđ€āļĢāļīāđˆāļĄāđ€āļ—āļĢāļ”āļāļąāļš XTB

āļĢāļąāļš Welcome Bonus 10% āđ€āļĄāļ·āđˆāļ­āđ€āļĢāļīāđˆāļĄāđ€āļ—āļĢāļ”āļāļąāļš XTB

āđ€āļĢāļīāđˆāļĄāļ•āđ‰āļ™āļ‡āđˆāļēāļĒ āđ† āđ€āļžāļĩāļĒāļ‡āđ€āļ›āļīāļ”āļšāļąāļāļŠāļĩāđāļĨāļ°āļāļēāļāđ€āļ‡āļīāļ™āļ„āļĢāļąāđ‰āļ‡āđāļĢāļ āļāđ‡āļĢāļąāļšāđ‚āļšāļ™āļąāļŠāļŠāļđāļ‡āļŠāļļāļ” 10 USD āđ€āļ‚āđ‰āļēāļšāļąāļāļŠāļĩāđ€āļ—āļĢāļ”āļ‚āļ­āļ‡āļ„āļļāļ“āđ‚āļ”āļĒāļ•āļĢāļ‡ āļžāļĢāđ‰āļ­āļĄāđ€āļ—āļĢāļ” āļŸāļ­āđ€āļĢāđ‡āļāļ‹āđŒ āļ—āļ­āļ‡āļ„āļģ āļ”āļąāļŠāļ™āļĩāđāļĨāļ°āļŠāļīāļ™āļ—āļĢāļąāļžāļĒāđŒāļ­āļ·āđˆāļ™ āđ†Â āļ­āļĩāļāļĄāļēāļāļĄāļēāļĒ 

āļĢāļąāļšāđ‚āļšāļ™āļąāļŠ 10% āļĢāļąāļšāđ‚āļšāļ™āļąāļŠ 10% āļĢāļąāļšāđ‚āļšāļ™āļąāļŠ 10% āļĢāļąāļšāđ‚āļšāļ™āļąāļŠ 10%
20 āļžāļĪāļĻāļˆāļīāļāļēāļĒāļ™ 2026, 14:38

āļ›āļāļīāļ—āļīāļ™āđ€āļĻāļĢāļĐāļāļāļīāļˆ: āļ•āļąāļ§āđ€āļĨāļ‚āļ„āļ§āļēāļĄāđ€āļŠāļ·āđˆāļ­āļĄāļąāđˆāļ™āļœāļđāđ‰āļšāļĢāļīāđ‚āļ āļ„āļŠāļŦāļĢāļąāļāļŊ āļ‚āļąāđ‰āļ™āļŠāļļāļ”āļ—āđ‰āļēāļĒ āđāļĨāļ°āļ–āđ‰āļ­āļĒāđāļ–āļĨāļ‡āļˆāļēāļāđ€āļˆāđ‰āļēāļŦāļ™āđ‰āļēāļ—āļĩāđˆ Fed

20 āļžāļĪāļĻāļˆāļīāļāļēāļĒāļ™ 2026, 14:34

āļĢāļēāļ„āļēāļ—āļ­āļ‡āļ„āļģāļĢāđˆāļ§āļ‡āļĨāļ‡āļŦāļ™āļķāđˆāļ‡āđƒāļ™āļŠāļēāļĄ āļ›āļąāļˆāļˆāļąāļĒāļāļ”āļ”āļąāļ™āļĄāļēāļˆāļēāļāļŠāļ āļēāļžāļ„āļĨāđˆāļ­āļ‡āđāļĨāļ° Fed āđ„āļĄāđˆāđƒāļŠāđˆāļŠāļąāļ™āļ•āļīāļ āļēāļžāđƒāļ™āđ€āļ‹āļīāļ™āđ€āļˆāļīāđ‰āļ™

20 āļžāļĪāļĻāļˆāļīāļāļēāļĒāļ™ 2026, 08:34

Market Wrap: Anthropic āļŦāļ™āļļāļ™āļ„āļ§āļēāļĄāđ€āļŠāļ·āđˆāļ­āļĄāļąāđˆāļ™āļ•āļĨāļēāļ” āđāļ•āđˆ Fed āļĒāļąāļ‡āđ€āļ‚āđ‰āļĄāļ‡āļ§āļ” āļ”āļąāļ™āļ”āļ­āļĨāļĨāļēāļĢāđŒāđāļ‚āđ‡āļ‡āļ„āđˆāļē

20 āļžāļĪāļĻāļˆāļīāļāļēāļĒāļ™ 2026, 08:24

Chart of the Day: āļĢāļēāļ„āļēāļ—āļ­āļ‡āđāļ”āļ‡āļĢāđˆāļ§āļ‡āļŦāļ™āļąāļāļ—āļĩāđˆāļŠāļļāļ”āđƒāļ™āļĢāļ­āļšāļ§āļąāļ™ āļ™āļąāļšāļ•āļąāđ‰āļ‡āđāļ•āđˆāđ€āļ”āļ·āļ­āļ™āđ€āļĄāļĐāļēāļĒāļ™ 2025

āļœāļĨāļīāļ•āļ āļąāļ“āļ‘āđŒāļ—āļēāļ‡āļāļēāļĢāđ€āļ‡āļīāļ™āļ—āļĩāđˆāđ€āļĢāļēāđƒāļŦāđ‰āļšāļĢāļīāļāļēāļĢāļĄāļĩāļ„āļ§āļēāļĄāđ€āļŠāļĩāđˆāļĒāļ‡ āđ€āļĻāļĐāļŦāļļāđ‰āļ™ (Fractional Shares) āđ€āļ›āđ‡āļ™āļœāļĨāļīāļ•āļ āļąāļ“āļ‘āđŒāļ—āļĩāđˆāđƒāļŦāđ‰āļšāļĢāļīāļāļēāļĢāļˆāļēāļ XTB āđāļŠāļ”āļ‡āļ–āļķāļ‡āļāļēāļĢāđ€āļ›āđ‡āļ™āđ€āļˆāđ‰āļēāļ‚āļ­āļ‡āļŦāļļāđ‰āļ™āļšāļēāļ‡āļŠāđˆāļ§āļ™āļŦāļĢāļ·āļ­ ETF āđ€āļĻāļĐāļŦāļļāđ‰āļ™āđ„āļĄāđˆāđƒāļŠāđˆāļœāļĨāļīāļ•āļ āļąāļ“āļ‘āđŒāļ—āļēāļ‡āļāļēāļĢāđ€āļ‡āļīāļ™āļ­āļīāļŠāļĢāļ° āļŠāļīāļ—āļ˜āļīāļ‚āļ­āļ‡āļœāļđāđ‰āļ–āļ·āļ­āļŦāļļāđ‰āļ™āļ­āļēāļˆāļ–āļđāļāļˆāļģāļāļąāļ”
āļ„āļ§āļēāļĄāļŠāļđāļāđ€āļŠāļĩāļĒāļŠāļēāļĄāļēāļĢāļ–āđ€āļāļīāļ™āļāļ§āđˆāļēāđ€āļ‡āļīāļ™āļ—āļĩāđˆāļāļēāļ