


Yesterday's decision by Fitch to downgrade the US rating to AA+ has so far not caused a very powerful reaction in the markets although the prevailing trend of risk aversion is evident. The US dollar is benefiting from this - the USDIDX index extends the rally. The U.S. private sector employment report by ADP came in much stronger than forecast at 324,000 versus 190,000 expected. It indicated a further increase in wages without a significant increase in unemployment - US household spending is likely to remain at fairly high levels. The U.S. dollar is considered one of the 'safe haven' assets, where cash withdrawn from exchange-traded funds and equities, among others, goes. In addition, BofA Research raised its forecast for U.S. real GDP growth for 2023 to 2% from 1.5% previously.
Comments from Fed members Bostic and Goolsbee fairly mixed - but the base case scenario is to maintain Fed policy restrictive.
Fed Bostic
- We are in a phase where there is a risk of excessive monetary tightening. The Fed should be cautious, patient but also decisive.
- If progress on inflation unexpectedly stalls, I would quietly consider a rate hike.
- Inflation is unacceptably high, but there has been significant progress, and recent data are promising.I expect unemployment to rise as inflation falls, but perhaps only to 4%.
- I will be determined not to change the direction of policy until I am confident that we will bring inflation down to 2%.
- My baseline outlook is for no rate cuts until the second half of 2024 at the earliest. I do not expect a rate hike in September.
Fed Goolsbee
- I will not pre-commit to a September FOMC vote, I want more evidence of easing inflation to end the cycle
- I am closely watching how core goods inflation is evolving. The JOLTS data looked consistent with a strong labor market moving into a more balanced phase.
- How long the Fed will have to hold interest rates or when it will cut them depends on whether it can bring inflation down without causing a recession
- We need to see sustained and steady progress on inflation, I am moderately optimistic.
- The path to lowering inflation without a serious recession is a narrow line, but so far it's working.
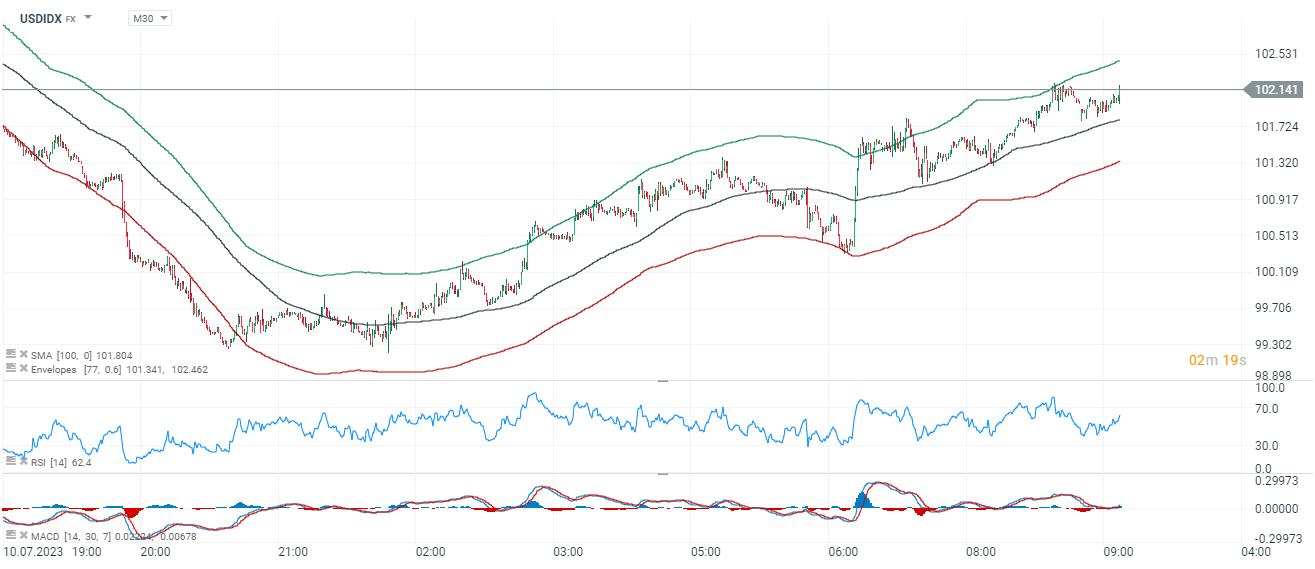 USDIDX dollar index, M30 interval. Source: xStation5


เศรษฐกิจฝรั่งเศสชะลอตัว ขณะที่เยอรมนียังประคองตัวได้ ยูโรร่วงหลุดระดับ 1.12

Chart of the Day: USDJPY ใกล้หมดแรงขึ้นแล้วหรือยัง? เงินเฟ้อกดดัน BoJ ให้ลงมือ แต่ Fed อาจสกัดการฟื้นตัวของเงินเยน

US100: แตะจุดต่ำสุดในรอบ 1 เดือน จะมีอะไรพลิกความคาดหมายเกิดขึ้นหรือไม่?


ปฏิทินเศรษฐกิจ: จับตาตัวเลข PMI เบื้องต้นและผลประกอบการบริษัท